
Financial Accounting Libby 6e Test bank ch.9
Chapter 009: Reporting and Interpreting Liabilities 9-1
True / False Questions
1. The mixture of debt and equity for a business is called its capital structure. TRUE
AACSB Tag: Relative Thinking Difficulty: Easy L.O.: 1
2. A current liability is always a short-term obligation expected to be paid within one year of the balance sheet date. FALSE
AACSB Tag: Relative Thinking Difficulty: Medium L.O.: 1
3. A current ratio that is high according to an industry average might mean the company may have excessive inventory levels or slow moving inventory items. TRUE
AACSB Tag: Relative Thinking Difficulty: Easy L.O.: 2
4. A current ratio can be manipulated by management through paying off current liabilities before the end of the accounting period. TRUE
AACSB Tag: Relative Thinking Difficulty: Medium L.O.: 2
©2009 McGraw-Hill Inc. Test Bank to accompany Libby Financial Accounting 6/e
To download more slides, ebook, solutions and test bank, visit http://downloadslide.blogspot.comTo download more slides, ebook, solutions and test bank, visit http://downloadslide.blogspot.comChapter 009: Reporting and Interpreting Liabilities
9-2 5. A liability, to be reported on the balance sheet, must have a fixed, known amount to be paid in the future. FALSE
AACSB Tag: Relative Thinking Difficulty: Hard L.O.: 3
6. The FICA (social security) tax is a matching tax with a portion paid by both the employer and the employee. TRUE
AACSB Tag: Relative Thinking Difficulty: Medium L.O.: 3
7. The accounts payable turnover ratio is computed by dividing sales by average accounts payable. FALSE
AACSB Tag: Relative Thinking Difficulty: Medium L.O.: 3
8. Interest is a function of the amount borrowed times the interest rate. FALSE
AACSB Tag: Relative Thinking Difficulty: Medium L.O.: 4
©2009 McGraw-Hill Inc. Test Bank to accompany Libby Financial Accounting 6/e
To download more slides, ebook, solutions and test bank, visit http://downloadslide.blogspot.comTo download more slides, ebook, solutions and test bank, visit http://downloadslide.blogspot.comChapter 009: Reporting and Interpreting Liabilities
9-3 9. A company borrowed $100,000 at 6% interest on September 1, 2009. Assuming no adjusting entries have been made during the year, the entry to record interest accrued on December 31, 2009 would include a debit to interest expense and a credit to interest payable for $3,000. FALSE
AACSB Tag: Analytic Difficulty: Medium L.O.: 4
10. All contingent liabilities should be classified as either current or long-term liabilities on the balance sheet for the current period. FALSE
AACSB Tag: Communication Difficulty: Medium L.O.: 5
11. A contingent liability that is "probable" and can be "reasonably estimated" must be accrued and reported as a liability. TRUE
AACSB Tag: Communication Difficulty: Medium L.O.: 5
12. When current liabilities decrease during the year, then we create a positive effect on cash flow from operating activities. FALSE
AACSB Tag: Relative Thinking Difficulty: Medium L.O.: 6
©2009 McGraw-Hill Inc. Test Bank to accompany Libby Financial Accounting 6/e
To download more slides, ebook, solutions and test bank, visit http://downloadslide.blogspot.comTo download more slides, ebook, solutions and test bank, visit http://downloadslide.blogspot.comChapter 009: Reporting and Interpreting Liabilities
9-4 13. Excessive or slow moving inventory could be the reason working capital is low. FALSE
AACSB Tag: Relative Thinking Difficulty: Easy L.O.: 6
14. A secured debt is where the borrowing company pledges specific assets as collateral for the loan. TRUE
AACSB Tag: Relative Thinking Difficulty: Medium L.O.: 7
15. As corporations have expanded globally, it has become common to borrow money in foreign currencies as a way to lessen exposure to exchange rate risk. TRUE
AACSB Tag: Relative Thinking Difficulty: Medium L.O.: 7
16. For the present value of a single amount, the compounding period may only be once a year. FALSE
AACSB Tag: Relative Thinking Difficulty: Medium L.O.: 8
©2009 McGraw-Hill Inc. Test Bank to accompany Libby Financial Accounting 6/e
To download more slides, ebook, solutions and test bank, visit http://downloadslide.blogspot.comTo download more slides, ebook, solutions and test bank, visit http://downloadslide.blogspot.com
财务会计学6东北财经大学罗伯特莉比

财务会计学6第1章 财务报表和企业决策Maxidrive 公司了解公司参与者企业经营活动会计系统四张基本财务报表:一个概述资产负债表利润表留存收益表现金流量表报表之间的关系附注四张基本财务报表的总结会计信息传递程序的责任公认会计准则管理责任和审计要求道德、声誉和法律责任结语第2章 投资、筹资决策和资产负债表PapaJohn's 国际公司了解企业会计概念概述本章 中强调的基本概念什么样的经济业务引起了财务报表金额的变化7企业经济业务的性质账户经济业务如何影响账户?经济业务分析的原则Papa John ’s 公司经济业务的分析公司如何记录账户余额?经济业务影响的方向分析工具经济业务分析说明如何编制和分析资产负债表?资产负债表的分类第3章 经营决策和利润表Papa John's 国际公司了解企业企业经济活动如何影响利润表?经营循环利润表要素如何确认和计量经营活动?权责发生制会计经济业务分析扩展模型经济业务分析规则Papa John's 经济业务的分析如何编制和分析财务报表?利润表分类留存收益表资产负债表分类第4章 调整、财务报告和收益质量Papa John's 公司了解企业收入和费用的调整会计循环调整的目的和类型调整程序编制财务报表利润表股东权益变动表资产负债表结账会计循环终点结账后试算表第5章 会计信息的传递和解释Callawav 高尔夫公司了解企业会计信息传递程序的参与者规制者(证券交易委员会,美国财务会计准则委员会,上市公司会计监管委员会,证券交易所)管理层(执行总裁,首席财务官,会计职员)董事会(审计委员会)审计师信息中介者:财务分析师和信息服务商使用者:机构和个人投资者,债权人以及其他传递有用性信息的指导性原则披露程序新闻公报年度报告季度报告证监会报告——10-K ,10-Q ,8-K 细观财务报表形式和附注资产负债表分类利润表分类股东权益变动表现金流量表财务报表的附注自愿性披露权益收益率分析:评价公司绩效的框架净资产收益率利润驱动分析利润驱动和企业策略结语第6章 销售收入、应收款项及现金的报告和解释Deckers Outdoor 公司了解企业销售收入会计处理对顾客的信用卡销售企业销售折扣销售退回和折让净销售收入的报告计量和报告应收款项应收款项的分类坏账的会计处理应收账款和坏账的报告坏账的估计对应收账款的控制现金的报告及安全保护现金及现金等价物的定义现金管理现金的内部控制现金日记账和银行对账单的调节结语第7章 商品销售成本和存货的报告与解释Harlev-Davidson 摩托车公司了解企业存货和销售成本的性质存货包括的项目存货采购成本存货成本的流转商品销售成本的性质存货成本计算方法个别辨认法成本流转假设存货计算方法对财务报告的影响管理层对存货计算方法的选择成本与市价孰低估价法存货评估管理存货管理中的效率计量存货和现金流量存货计算方法和财务报表分析存货控制存货的内部控制永续盘存制和实地盘存制期末存货计量错误第8章 土地、厂房、设备以及自然资源和无形资产的报告与解释西南航空公司了解企业厂房和设备的购置与维护长期资产的分类取得成本的计量和报告修理、维护和更新厂房和设备的使用、毁损与处置折旧概念可供选择的折旧计算方法经理如何选择?第9章 负债的报告和解释第10章 债务的报告和解释第11章 所有者权益的报告和解释(美)莉比(Libby.R.).(美)莉 出 版社: 东北财经大学出版社会计词汇Account 账户Accounting 会计学Account payable 应付账款Annual report 年度报告Assets 资产Audit 审计Auditor 审计人员Auditors’opinion 审计意见Balance sheet 资产负债表Balance sheet equation 会计恒等式Capital stock certificate 股份证明Certified public accountant 注册会计师Common stock 普通股Compound entry 复合分录Corporation 公司Creditor 债权人Debtor 债务人Entity 主体Financial accounting 财务会计Independent opinion 独立意见Inventory 存货Liabilities 负债Limited liability 有限责任Management accounting 管理会计Notes payable 应付票据Open account 往来账户Owners’equity 所有者权益Paid-in capital 实收资本Paid-in capital in excess of par value 资本公积Partnership 合伙企业Par value 票面价值Private accountants 私立会计Privately owned 私人持有Public accountants 公共会计Publicly owned公共持有Shareholders’equity 所有者权益Sole proprietorship 个人独资企业Stated value 票面价值Statement of financial condition 财务状况表Statement of financial position 财务状况表Stock certificate 股份证明Stockholders’equity 所有者权益Transaction 交易Accounting: The process of identifying, recording, summarizing, and reporting economic information to decision makers.会计:识别,记录,汇总,并报告经济信息给决策者的程序。
financial accounting第七章PPT课件

$8
(现金盈亏账户)
Cr sales
$3150
Change fund,求解释
2020/10/13
4
Internal control of cash payments
A voucher system is a set of procedures
for authorizing and recording liabilities and cash payments.
2020/10/13
7
Cash balance according to depositor’s records …...........$xxxx ③Add :addtions by bank not recorded by depositor…$xx Depositor errors……………………………………xx xx $xxxx ④Deduct:deductions by bank not recorded by depositor.$xx Depositor errors……………………………………xx xx
from cash sales
in the mail
2020/10/13
3
eg:the entry records a clerk’s cash sales of
$3,150 when the actual cash on hand is
$3,142
Dr Cash
$3142
Cash Short and Over
many transactions either directly or indirectly affect the receipt or the payment of cash.
Financial accounting theory chapter9新会计体系-社会和环境因素影响下的外部呈报
Copyright © 2000 McGraw-Hill Book Co. Aust. PPT t/a Financial Accounting Theory by Deegan 9.9
Chapter 9: New systems of accounting
– not a view held universally
Copyright © 2000 McGraw-Hill Book Co. Aust.
PPT t/a Financial Accounting Theory by Deegan
9.5
Chapter 9: New systems of accounting
Copyright © 2000 McGraw-Hill Book Co. Aust. PPT t/a Financial Accounting Theory by Deegan 9.6
Chapter 9: New systems of accounting
Accountability
• The duty to provide an account (not necessarily financial) or reckoning of those action for which one is held responsible • two responsibilities or duties
• Moves to provide information about social and environmental performance implies management of these organisations consider they have an accountability for social and environmental performance, as well as economic performance
financial accounting第七章课件
Bank reconciliation
A bank reconciliation is a listing of the items and amounts that cause the cash balance reported in the bank statement to differ from the balance of the cash account in the ledger. A bank reconciliation is usually divided into two setions.(表 )
$2549.99 $408 $2957.99
$2630.99
Ending
Financial accounting
Chapter 7 Cash
会计113班第二小组
Cash coins,currency(papermoney),checks,money orders,and money on deposit that is available for unrestricted withdrawal from banks and other financial institutions. The Controls Over Cash First,because of the ease with which money can be transferred ,cash is the asset most likely to be diverted and used improperly by employees;second, many transactions either directly or indirectly affect the receipt or the payment of cash.
罗斯公司理财第9版ch01配套练习题及答案
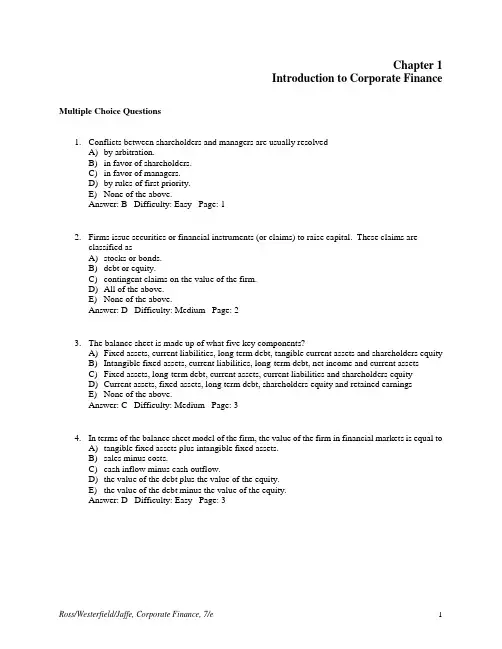
3. The balance sheet is made up of what five key components? A) Fixed assets, current liabilities, long term debt, tangible current assets and shareholders equity B) Intangible fixed assets, current liabilities, long-term debt, net income and current assets C) Fixed assets, long-term debt, current assets, current liabilities and shareholders equity D) Current assets, fixed assets, long term debt, shareholders equity and retained earnings E) None of the above. Answer: C Difficulty: Medium Page: 3
TestBank-Ch01

Management Information Systems Test BankChapter 1 Information Systems in Global Business Today1 True-False Questions1) Developing a new product, fulfilling an order, and hiring a new employee are examples of business processes.Answer: TRUE2) A fully digital firm produces only digital goods or services.Answer: FALSE3) A business model describes how a company produces, delivers, and sells a product or service to create wealth.Answer: TRUE4) Information technology (IT) consists of all the hardware that a firm needs to use in order to achieve its business objectives, whereas information systems consist of all the software and business processes needed.Answer: FALSE5) Computers are only part of an information system.Answer: TRUE6) Information systems literacy describes the behavioral approach to information systems, whereas computer literacy describes the technical approach.Answer: FALSE7) The dimensions of information systems are management, organizations, and information technology.Answer: TRUE8) In order to understand how a specific business firm uses information systems, you need to know something about the hierarchy and culture of the company.Answer: TRUE9) Business processes are logically related tasks for accomplishing tasks that have been formally encoded by an organization.Answer: FALSE10) There are four major business functions: Sales and marketing; manufacturing and production; finance and accounting; and information technology.Answer: FALSE11) A substantial part of management responsibility is creative work driven by new knowledge and information.Answer: TRUE12) An IT infrastructure provides the platform on which the firm can build its information systems.Answer: TRUE13) Government and private sector standards are examples of complementary social assets required to optimize returns from IT investments.Answer: TRUE14) A firm that invests in efficient business processes is making an investment in organizational complementary assets.Answer: TRUE15) The behavioral approach to information systems focuses on changes in attitudes, management and organizational policy, and behavior.Answer: TRUE2 Multiple-Choice Questions1) The six important business objectives of information technology are new products, services, and business models; customer and supplier intimacy; survival; competitive advantage; operational excellence; andA) improved flexibility. B) improved decision making.C) improved business practices. D) improved efficiency.Answer: B2) The use of information systems because of necessity describes the business objective ofA) survival. B) improved business practices.C) competitive advantage. D) improved flexibility.Answer: A3) Which of the following choices may lead to competitive advantage: (1) new products, services, and business models; (2) charging less for superior products; (3) responding to customers in real time?A) 1 only B) 1 and 2C) 2 and 3 D) 1, 2, and 3Answer: D4) An information system can be defined technically as a set of interrelated components that collect, process, store, and distribute information to supportA) decision making and control in an organization.B) communications and data flow.C) managers analyzing the organization's raw data.D) the creation of new products and services.Answer: A5) The three activities in an information system that produce the information organizations use to control operations areA) information retrieval, research, and analysis.B) input, output, and feedback.C) input, processing, and output.D) data analysis, processing, and feedback.Answer: C6) Order data for baseball tickets and bar code data are examples ofA) raw input. B) raw output.C) customer and product data. D) sales information.Answer: A7) The average number of tickets sold daily online is an example ofA) input. B) raw data.C) meaningful information. D) feedback.Answer: C8) OutputA) is feedback that has been processed to create meaningful information.B) is information that is returned to appropriate members of the organization to help them evaluate the input stage.C) transfers data to the people who will use it or to the activities for which it will be used.D) transfers processed information to the people who will use it or to the activities for which it will be used.Answer: D9) Converting raw data into a more meaningful form is calledA) capturing. B) processing.C) organizing. D) feedback.Answer: B10) The field that deals with behavioral issues as well as technical issues surrounding the development, use, and impact of information systems used by managers and employees in the firm is calledA) information systems literacy.B) information systems architecture.C) management information systems.D) information technology infrastructure.Answer: C11) The fundamental set of assumptions, values, and ways of doing things that has been accepted by most of a company's members is called itsA) culture. B) environment.C) atmosphere. D) values.Answer: A12) Networking and telecommunications technologies, along with computer hardware, software, data management technology, and the people required to run and manage them, constitute an organization'sA) data management environment. B) networked environment.C) IT infrastructure. D) information system.Answer: C13) Maintaining the organization's financial records is a central purpose of which main business function?A) manufacturing and accounting B) finance and accountingC) sales and manufacturing D) finance and salesAnswer: B14) In a business hierarchy, the level that is responsible for monitoring the daily activities of the business isA) middle management. B) service workers.C) production management. D) operational management.Answer: D15) Which of the following are environmental actors that interact with an organization and its information systems?A) customers B) suppliersC) regulatory agencies D) all of the aboveAnswer: D16) A corporation that funds a political action committee, which in turn promotes and funds a political candidate who agrees with the values of that corporation, could be seen as investing in which main category of complementary assets?A) managerial B) governmentalC) social D) organizationalAnswer: C17) An example of an organizational complementary asset isA) using the appropriate business model.B) a collaborative work environment.C) laws and regulations.D) all of the above.Answer: A18) An example of a social complementary asset isA) technology and service firms in adjacent markets.B) training programs.C) distributed decision-making rights.D) all of the above.Answer: A19) Disciplines that contribute to the technical approach to information systems are:A) computer science, engineering, and networking.B) operations research, management science, and computer science.C) engineering, utilization management, and computer science.D) management science, computer science, and engineering.Answer: B20) Sociologists study information systems with an eye to understandingA) how systems affect individuals, groups, and organizations.B) how human decision makers perceive and use formal information.C) how new information systems change the control and cost structures within the firm.D) the production of digital goods.Answer: A21) Psychologists study information systems with an eye to understandingA) how systems affect individuals, groups, and organizations.B) how human decision makers perceive and use formal information.C) how new information systems change the control and cost structures within the firm.D) the production of digital goods.Answer: B22) Which of the following are key corporate assets?A) intellectual property, core competencies, and financial and human assetsB) production technologies and business processes for sales, marketing, and financeC) knowledge and the firm's tangible assets, such as goods or servicesD) time and knowledgeAnswer: A23) A firm that must invest in new information systems capabilities in order to comply with federal legislation can be said to be investing to achieve which business objective?A) customer intimacy B) operational excellenceC) survival D) improved reportingAnswer: C24) Which field of study focuses on both a behavioral and technical understanding of information systems?A) sociology B) operations researchC) economics D) management information systemsAnswer: D25) The three principle levels within a business organization hierarchy areA) senior management, operational management, and service workers.B) senior management, middle management, and operational management.C) senior management, operational management, and information systems.D) senior management, middle management, and service workers.Answer: B26 ) Which main business function is responsible for maintaining employee records?A) sales and marketing B) human resourcesC) finance and accounting D) manufacturing and productionAnswer: B27) The shared information technology resources for the organization are called its:A) MIS plan. B) operational networkC) IT infrastructure D) business infrastructureAnswer: C28) Promoting the organ ization’s products and services is a business function of:A) manufacturing and production B) finance and accountingC) human resources D) sales and marketingAnswer:D29) A broad-based understanding of information systems that includes behavioral knowledge about organizations and individuals using information systems as well as technical knowledge about computers is called:A) computer literacy B) technology literacy.C) management literacy D) information systems literacy.Answer: D30) Converting raw data into a more meaningful form is called:A) capturing B) processing.C) controlling D) feedback.Answer: B3 Fill in the Blanks1) A(n) ________ is one where nearly all significant business processes and relationships are managed through digital means.Answer: digital firm2) ________ refer to the set of logically related tasks and behaviors that organizations develop over time to produce specific business results and the unique manner in which these activities are organized.Answer: Business processes3) A ________ describes how a company produces, delivers and sells a product or service to create wealth.Answer: business model4) A(n) ________ is composed of interrelated components working together to collect, process, store, and disseminate information to support decision making, coordination, control, analysis, and visualization in an organization.Answer: information system5) ________ is data that has been shaped into a form that is meaningful to human beings.Answer: Information6) To fully understand information systems, you must understand the broader , management and technology dimensions of system.Answer: Feedback7) A(n) ________ refer to broader understanding of information systems, which encompasses an understanding of the management and organizational dimensions as well as the technical dimensions of systems.Answer: information systems literacy8) In a(n) ________ perspective, the performance of a system is optimized when both the technology and the organization mutually adjust to one another until a satisfactory fit is obtained.Answer: sociotechnical9) ________ makes long-range strategic decisions about the firm's products and services.Answer: Senior management10) ________ refer to those assets required to derive value from a primary investment. Answer: Complementary assets4 Essay Questions1) Why are information systems so essential for running and managing a business today?Answer: Information systems are the foundation for conducting business today. In many industries, survival and even existence without extensive use of IT is inconceivable, and IT plays a critical role in increasing productivity.Six reasons why information systems are so important for business today include:(1) Operational excellence(2) New products, services, and business models(3) Customer and supplier intimacy(4) Improved decision making(5) Competitive advantage(6) Survival2) What exactly is an information system?Answer: We can define information systems from both a technology and a business perspective.Technology perspective: An information system is a set of interrelated components that work together to collect, process, store, and disseminate information to support decision making, coordination, control, analysis, and visualization in an organization. Business Perspective: An information system represents an organizational and management solution based on information technology, to a challenge or problem posed by the environment.3) List and describe the organizational, management, and technology dimensions of information systems.Answer:•Organization: The organization dimension of information systems involves issues such as the organization’s hierarchy, functional specialties, business processes, culture, and political interest groups.•Management: The management dimension of information systems involves setting organizational strategies, allocating human and financial resources, creating new products and services and re-creating the organization if necessary.•Technology: The technology dimension consists of computer hardware, software, data management technology, and networking/telecommunications technology.4) Describe the sociotechnical perspective on information systems.Answer: A sociotechnical perspective combines the technical approach and behavior approach to achieve optimal organizational performance. Technology must be changed and designed to fit organizational and individual needs and not the other way around. Organizations and individuals much also change through training, learning, and allowing technology to operate and prosper.[文档可能无法思考全面,请浏览后下载,另外祝您生活愉快,工作顺利,万事如意!]。
Financial Accounting006
Date Jan. 2
GENERAL JOURNAL
Description
Page 34
Debit Credit
McGraw-Hill/Irwin
© 2004 The McGraw-Hill Companies
6-7
Credit Card Sales to Consumers
On January 2, a Timberland factory store’s credit card sales were $3,000. The credit card company charges a 3% service fee.
An exchange has taken place.
The earnings process is nearly complete.
McGraw-Hill/Irwin
Collection is probable.
© 2004 The McGraw-Hill Companies
6-3
Reporting Net Sales
Amount Is Due
Maximum Days in Credit Period
McGraw-Hill/Irwin
© 2004 The McGraw-Hill Companies
Companies record sales discounts, sales returns and allowances, and credit
card discounts separately to allow management to monitor these transactions.
When companies allow customers to purchase merchandise on an open
Financial Accounting Theory (7)
Copyright © 2015 Pearson Canada Inc.
7-8
7.4 Financial Instruments
• Definition
– A contract that creates a financial asset of one firm and a financial liability or equity instrument of another firm
• Recognition is sooner than under historical cost
• Increases in value recognized when realized under historical cost
Copyright © 2015 Pearson Canada Inc.
• After acquisition, most liabilities valued at amortized cost
Copyright © 2015 Pearson Canada Inc. 7 - 10
7.5.3 The Fair Value Option
• Under IFRS 9, firm may designate financial assets/liabilities at acquisition as valued at fair value to reduce a mismatch.
• Barth, Hodden, and Stubben (2008)
– IFRS 9 requires own credit risk gains/losses to be included in OCI
Copyright © 2015 Pearson Canada Inc.
会计学原理FinancialAccountingbyRobertLibby第八版第十一
会计学原理FinancialAccountingbyRobertLibby第八版第十一Chapter 11 - Reporting and Interpreting Owners’ EquityChapter 11Reporting and Interpreting Owners’ Equity__ TO __NS1. A corporation is a separate legal entity (authorized by law to operate as an individual).It is owned by a number of persons and/or entities whose ownership is evidenced by shares of capital stock. Its primary advantages are: (a) transferability of ownership, (b) limited liability to the owners, and (c) the ability to accumulate large amounts of resources. 2. The charter of a corporation is a legal document from the state that authorizes itscreation as a separate legal entity. The charter specifies the name of the entity, its purpose, and the kinds and number of shares of capital stock it can issue. 3. (a) Authorized capitalstock―the maximum number of shares of stock that can be sold and issued as specified in the charter of the corporation.(b) Issued capital stock―the total number of shares of capital stock that havebeen issued by the corporation at a particular date. (c) Outstanding capital stock―the number of shares currently owned by thestockholders.4. Common stock―the usual or normal stock of the corporation. It is the voting stockand generally ranks after the preferred stock for dividends and assets distributed upon dissolution. Often it is called the residual equity. Common stock may be either par value or no-par value.Preferred stock―when one or more additional classes of stock are issued, the additional classes are called preferred stock. Preferred stock has modifications that make it different fromcommon stock. Generally, preferred stock has both favorable and unfavorable features in comparison with common stock. Preferred stock usually is par value stock and usually specifies a dividend rate such as D6% preferred stock.‖Chapter 11 - Reporting and Interpreting Owners’ Equity5. Par value is a nominal per share amount established for the common stock and/orpreferred stock in the charter of the corporation, and is printed on the face of each stock certificate. The stock that is sold by a corporation to investors above par value is said to have sold at a premium, while stock that is sold below par is said to have sold at a discount. The laws of practically all states forbid the initial sale of stock by a corporation to investors below par value. No-par value stock does not have an amount per share specified in the charter. As a consequence, it may be issued at any price without involving a discount or a premium. It avoids giving the impression of a value that is not present. 6. The usual characteristics of preferred stock are: (1) dividend preferences, (2) conversion privileges, (3) asset preferences, and (4) nonvoting specifications. 7. The two basic sources of stockholders’ equity are:Contributed capital―the amount invested by stockholders by purchase from the corporation of shares of stock. It is comprised of two separate elements: (1) the par or stated amount derived from the sale of capital stock (common or preferred) and(2) the amount received in excess of par or stated value.Retained earnings―the accumulated amount of all ne t income since the organization of the corporation, less losses and less the accumulated amount of dividends paid by the corporation since organization.8. Stockholders’ equity is accounted for in terms of source. This means that severalaccounts are maintained for the various sources of stockholders’ equity, such as common stock, preferred stock, contributed capital in excess of par, and retained earnings. 9. Treasury stock is a corporation’s own capital stock that was sold (issued) andsubsequently reacquired by the corporation. Corporations frequently purchase shares of their own capital stock for sound business reasons, such as to obtain shares needed for employees’ bonus plans, to influence the market price of the stock, to increase earnings per share amounts, and to have shares on hand for use in the acquisition of other companies. Treasury stock, while held by the issuing corporation, confers no voting, dividend, or other stockholder rights. 10. Treasury stock is reported on the balance she et under stockholders’ equity as adeduction; that is, as contra stockholders’ equity. Any Dgain or loss‖ on treasury stock that has been sold is reported on the financial statements as an addition to contributed capital if a gain; if a loss, it is deducted from any previous contributed capital, or otherwise from retained earnings.Chapter 11 - Reporting and Interpreting Owners’ Equity11. The two basic requirements to support a cash dividend are: (1) cash on hand or theability to obtain cash sufficient to pay the dividend and (2) a sufficient balance in retained earnings, because the dividend represents a return of earnings to the stockholders. A cash dividend reduces both the assets of a corporation and stockholders’ equity by the amount o f the dividend. 12. Cumulative preferred stock has a dividend preference such that, should thedividends on the preferred stock for any year, or series of years, not be paid, dividends cannot be paid to the common stockholders until all such dividends in arrears are paid to the preferred stockholders. Noncumulative preferred stock does not have this preference; therefore, dividends not paid in past periods will never be paid to the preferred stockholders. 13. A stockdividend involves the issuance to the stockholders of a dividend in thecorporation’s own stock (rather than cash). A stock dividend is significantly different from a cash dividend in that the corporation does not disburse any assets, while in the case of a cash dividend, cash is decreased by the amount of the dividend.A cash dividend also reduces total stockholders’ equity by the amount of the dividend. In contrast, a stock dividend does not change total stockholders’ equity. 14. The primary purposes for issuing a stock dividend are: (1) to maintain dividendconsistency; that is, to pay dividends each year either in cash or in capital stock, and (2) to capitalize retained earnings; that is, a stock dividend requires a transfer from the Retained Earnings account to the permanent contributed capital accounts for the amount of the dividend. Although this transfer does not change stockholders’ equity in total, it does cause a shift from retained earnings to contributed capital. 15. When a dividend is declared and paid, the three important dates are:Declaration date―the date on which the board of directors votes the dividend. In the case of a cash dividend, a dividend liability comes into existence on this date and must be recordedas a debit to Retained Earnings and as a credit to Dividends Payable.Date of record―this date usually is about one month after the date of declaration. It is the date on which the corporation extracts from its stockholders’ records the list of individuals owning shares. The dividend is paid only to those names listed on the record date. No entry in the accounts is made on this date.Date of payment―the date on which the cash is disbursed to pay the dividend. It follows the date of record as specified in the dividend announcement. The entry to record the cash disbursement for the dividend is a debit to Dividends Payable and a credit to Cash.Chapter 11 - Reporting and Interpreting Owners’ Equity16. Retained earnings is the accumulated amount of all net income of the corporationless all losses and less the accumulated amount of all dividends declared to date. The primary components of retained earnings are: beginning balance, plus net income, less net losses, minus dividends declared, equals the ending balance.__ TO __E CHOICE1. c) 6. b)2. d) 7. c)3. b) 8. c)4. a) 9. d)5. c) 10. a)Chapter 11 - Reporting and Interpreting Owners’ EquityAuthors’ Recommended Solution Time(Time in minutes)students will need to complete the assignment. As with any open-ended project, it is possible for students to devote a large amount of time to these assignments. While students often benefit from the extra effort, we find that some become frustrated by the perceived difficulty of the task. You can reduce student frustration and anxiety by making your expectations clear. For example, when our goal is to sharpen research skills, we devote class time to discussing research strategies. When we want the students to focus on a real accounting issue, we offer suggestions about possible companies or industries.Chapter 11 - Reporting and Interpreting Owners’ EquityMINI- __ESM11C1.Stockholders may:a) Vote in the stockholders’ meeting (or by proxy) on major issues concerning management of the corporation. b) Participate proportionately with other stockholders in the distribution of the corporation’s profits. c) Share proportionately with other stockholders in the distribution of corporate assets upon liquidation.Being able to vote is the most important of the rights because this ensures that the owners have an input at the stockholders’ meeting and some control of the management of the corporation, thus enabling them to protect their rights as stockholders. M11C2.Unissued shares = 90,000 (268,000 C 178,000) M11C3.Cash (170,000 $21) (+A) ...........................................3,570,000Common Stock (170,000 $1) (+SE) ......................Capital in Excess of Par (+SE) .................................The journal entry would be different if the par value were $2: Cash (170,000 $21) (+A) ...........................................3,570,000Common Stock (170,000 $2) (+SE) ......................Capital in Excess of Par (+SE) .................................340,000 3,230,000170,000 3,400,000Chapter 11 - Reporting and Interpreting Owners’ EquityM11C4.Common stock is the basic voting stock issued by a corporation. It ranks after preferred stock for dividends and assets distributed upon liquidation of thecorporation. The dividend rate for common stock is determined by the board of directors, and is based on the company’s profitability. The dividend rate forpreferred stock is fixed by a contract. Common stock has more potential for growth than preferred stock if the company is profitable. On the other hand, the investor may lose more money with common stock than with preferred stock if the company is not profitable.Usually, It is advisable to invest in the common stock if you believe the company will be profitable. Common stock will receive a higher return on the $100,000 than preferred stock would.Chapter 11 - Reporting and Interpreting Owners’ EquityM11C7.April 15:Retained Earnings (-SE) .............................................. Dividends Payable (+L) ............................................June 14:Dividends Payable (-L) ................................................. Cash (-A) ..................................................................65,00065,00065,00065,000M11C10.Retained Earnings (-SE) .............................................. Common Stock (+SE) ..............................................800,000800,000Chapter 11 - Reporting and Interp reting Owners’ Equity__ESE11C1.Computation of End of Year Balance for Treasury Stock:Beginning balance Net increase307,532,841 383,407,665Ending balanceComputation of Shares Outstanding: E11C2.Req. 1 The number of authorized shares is specified in the corporate charter: 300,000. Req. 2 Issued shares are the sharessold to the public: 160,000 Req. 3Issued shares 160,000 Treasury stockIssued shares Treasury stock2,109,316,331 1,725,908,666Shares OutstandingOutstanding shares 135,000Chapter 11 - Reporting and Interpreting Owners’ EquityE11C3. Req. 1Stockholders’ EquityContributed capital: Preferred stock, authorized 4,000 shares, issued and outstanding, 3,000 shares ...................................................... $ 24,000 Common stock, authorized 103,000 shares,issued and outstanding, 20,000 shares .................................................... 200,000 Capital in excess of par, preferred .............................................................. 36,000 Capital in excess of stated value, no-par common ..................................... 120,000 Total contributed capital .......................................................................... 380,000 Retained earnings .......................................................................................... 60,000 Total Stockholders’ Equity .......................................................................Req. 2The answer would depend on the profitability of the company and the stability of its earnings. The preferred stock has a 9% dividend rate. If the company earns more than 9%, the additional earnings would accrue to the current stockholders. If the company earns less than 9%, it would pay a higher rate to the preferred stockholders. E11C4.Req. 1 ($30 x 90,000 shares) - $1,600,000 = $1,100,000 Req.2 $900,000 - $1,000,000 + $800,000 = $700,000 Req.3 90,000 shares C 80,000 shares = 10,000 shares Req.4 EPS = $1,000,000 80,000 = $12.50Chapter 11 - Reporting and Interpreting Owners’ EquityE11C5.Req. 1a. Cash (5,600 shares x $20) (+A) ............................................ 112,000 Common stock (5,600 shares x $10) (+SE) ...................... Capital in excess of par, common stock (+SE) .................. Sold common stock at a premium.b.Cash (1,000 shares x $25) (+A) ............................................ Common stock (1,000 shares x $10) (+SE) ...................... Capital in excess of par, common stock (+SE) .................. Sold common stockat a premium.25,00056,000 56,000 10,000 15,000Req. 2Stockholders’ EquityContributed capital: Common stock, par $10, authorized 11,500 shares, outstanding 6,600 shares .................................................................... $ 66,000 Contributed capital in excess of par ........................................................ 71,000 Total contributed capital .......................................................................... 137,000 Retained earnings ...................................................................................... 12,000 Stockholders’ equity ...................................................................................Chapter 11 - Report ing and Interpreting Owners’ EquityE11C6. Req. 1Req. 2(Note that this solution is based on the number of Class A common shares that areoutstanding. We elect not to include the Class B shares because they are owned by the Dillard family. Usually, students do not question this assumption but when they do, it permits usto discuss reasons for issuing different types of common stock. In this case, owners of Class B shares are permitted to elect two-thirds of the board of directors, effectively letting the founding family maintain control of a public company). Number of shares outstanding 2022年: 118,529,925 shares issued minus 73,099,319 Number of shares outstanding 2022年: 117,706,523 shares issued minus 61,740,439 Req. 3(In thousands) Retained earnings for 2022年: $3,107,344minusnet income for 2022年$463,909 plus dividends for 2022年$10,002 = $2,653,437 Req. 4(thousand). Req. 5Treasury stock transactions decreased stockholders’ equity by $490,786 (thousand) ($1,846,312 - $1,355,526). Req. 6 For 2022年, treasury stock cost per share: $1,846,312 (thousand) ÷ 73,099,319 shares =Chapter 11 - Reporting and Interpreting Owners’ EquityE11C7.Req. 1a. Cash (50,000 shares x $50) (+A) .......................................... 2,500,000 Common stock (50,000 shares x $2) (+SE) ...................... 100,000 Capital in excess of par, common stock (+SE) ..................2,400,000 Sold common stock at a premium. b.Treasury stock (2,000 shares x $52) (+XSE, -SE) ................ Cash (-A) ........................................................................... Bought treasury stock.104,000104,000Req. 2Stockholders’ EquityContributed capital: Common stock, par $2, authorized 80,000 shares, issued 50,000 shares .......................................................................... $ 100,000 Contributed capital in excess of par ........................................................ 2,400,000 Total contributed capital .......................................................................... 2,500,000 Treasury stock............................................................................................ (104,000 ) Stockholders’ equity ................................................................................... E11C8.Shareholders’ equity (deficit) in thousands:Common stock, par value $.01 per share; 100,000,000 shares authorized, 33,981,509 shares issued and outstanding at December 31, 2022年, 34,150,389 shares issued and outstandingat December 31, 2022年Additional paid-in capital Accumulated deficitTotal shareholders’ equity2022年2022年340 342 198,304 200,524 (118,282 ) (98,733 ) 80,362 102,133Chapter 11 - Reporting and Interpreting Owners’ EquityE11C9.Stockholders’ EquityContributed capital: Preferred stock, 8%, par $50, authorized 59,000 shares, issued and outstanding, 20,000 shares ............................................... $1,000,000 Common stock, par $10, authorized 98,000 shares, issued, 78,000 shares ......................................................................... 780,000 Capital in excess of par, preferred stock ................................................. 600,000 Capital in excess of par, common stock .................................................. 780,000 Treasury stock ..................................................................................... (80,000) Retained earnings* ......................................................................................... 160,000 Total stockholders’ equity........................................................................ *($210,000 C $50,000 = $160,000.) E11C10.a. Cash (20,000 shares x $20) (+A) .......................................... 400,000 Common stock, no-par (+SE) ............................................ .b. Cash (6,000 shares x $40) (+A) ............................................ 240,000 Common stock, no-par (+SE) ...........................................c.Cash (7,000 shares x $30) (+A) ............................................ 210,000 Preferred stock (7,000 shares x $10) (+SE) ...................... Capital in excess of par, preferred (+SE) ..........................400,000 240,000 70,000 140,000Req. 2Yes, it is ethical as long as there is a full disclosure of relevant information. In any arm’slength transaction, an informed buyer will pay the market value of the stock.Chapter 11 - Reporting and Interpreting Owners’ EquityE11C11. Req. 1Number of preferred shares issued: $100,000 Req. 2Number of preferred shares outstanding: 10,000 shares issued minus 500 shares held Req. 3Average sales price per share of preferred stock when issued: ($100,000 + $15,000) ÷ Req. 4Treasury stock transactions decreased stockholders’ equity by $8,000 (same as the decrease in corporate resources in 4 above). Req. 6Treasury stock cost per share: $9,500 ÷Req. 7Req. 8Issue price of common stock $600,000 ÷Chapter 11 - Reporting and Interpreting Owners’ EquityE11C12. Req. 1The number of shares that have been issuedis computed by dividing the common stock account ($4,008 million) by the par value of the shares ($1 per share) or approximately 4,008,000,000 shares. Req. 2Retained earnings end of 2022年 ............ $70,682,000,000 Net income for 2022年 ............................ 10,756,000,000 Dividends for 2022年 ............................... (5,811,600,000 ) Retained earnings end of 2022年 ............ $75,626,400,000The amount of retained earnings is an estimate because we do not know the exactnumber of shares outstanding (because we do not know the number of shares in treasury stock). This number is needed todetermine the amount of dividends paid during 2022年. We based the dividends on the estimate calculated in the previous requirement.E11C13.The treasury stock account is a contra equity account, meaning that it subtracts from the total stockholders’ equity. Cash also decreases on the balance sheet by the same amount.Req. 2Many companies repurchase common stock in order to develop an employee bonus plan that provides workers with shares of the company’s stock as part of their compensation. Because of SEC regulations concerning newly issued shares, companies find it cheaper to give their employees shares of stock that were purchased from stockholders than to issue new shares. In this case, the company mentions the goal of enhancing shareholders’ value. If the company main tains its current level of income, earnings per share will increase with fewer shares outstanding. Themanagement expects that the increase in EPS will be reflected in an increase in stock price. Req. 3Shares that are held in treasury stock do not participate individend payments. As a result, the purchase of treasury stock will reduce the amount of dividends that the company must pay in future years.Chapter 11 - Reporting and Interpreting Owners’ EquityE11C14. Req. 1Stockholders’ Eq uityContributed capital:Common stock, authorized 100,000 shares, issued 34,000 shares, ofwhich 2,000 shares are held as treasury stock .................................. Capital in excess of par ........................................................................ Total contributed capital .................................................................... Retained earnings ................................................................................... Total .................................................................................................. Less: Cost of treasury stock ................................................................. Total Stockholders’ Equity Req. 2The dividend yield ratio is 2.24% ([$16,000 32,000 shares] $22.29). While this yield seems small, it is a typical return on common stock. Investors receive a return from both dividends and stock price appreciation.Treasury stock does not receive dividends. As a result, dividends should be paid on 32,000 shares. E11C15.Req. 1a. Treasury stock (200 shares x $20) (+XSE, -SE) ................... Cash (-A) ........................................................................... Bought treasury stock.b.Cash (40 shares x $25) (+A) ................................................. Treasury stock(40 shares x $20) (-XSE, +SE) .................. Capital in excess of par (+SE) ........................................... Sold treasury stock.Capital in excess of par (-SE) ............................................... Treasury stock (30 shares x $20) (-XSE, +SE) ................ Sold treasury stock.4,0001,000450 1504,000800 200600$680,000 163,000 843,000 89,000 932,000 25,000 c. Cash (30 shares x $15) (+A) .................................................Req. 2It is not possible to make a Dprofit‖ or Dloss‖ on treasury stock transactions. Therefore, these transactions do not affect the income statement.Chapter 11 - Reporting and Interpreting Ow ners’ EquityE11C16.Req. 1 Feb. 1:Treasury stock, common (160 shares x $20) (+XSE, -SE) Cash (-A) ........................................................................July 15:Cash (80 shares x $21) (+A) ............................................. Treasury stock, common (-XSE, +SE) ........................... Capital in excess of par (+SE) .......................................Sept. 1:Cash (50 shares x $19) (+A) ............................................. Capital in excess of par (-SE) ............................................ Treasury stock, common (50 shares x $20) (-XSE, +SE) . Req. 2Dividends are not paid on treasury stock. Therefore, the amount of total cash dividends paid is reduced when treasury stock is purchased. Req. 3The sale of treasury stock for more or less than its original purchase price does not have an impact on net income. Thetransaction affects only balance sheet accounts. The cash received from the sale of treasury stock is a cash inflow which would affect the Statement of Cash Flows in the financing activities section.3,2001,680950 503,2001,600 80 1,000Chapter 11 - Reporting and Interpreting Owners’ EquityE11C17. Req. 1Case 1: When companies unexpectedly announce increases in dividends, stock prices typically increase. Depending on course objective, the instructor may want to discuss research in finance concerning dividend policy.Case 2: Stock price is based on expectations. If the increase in operatingperformance was not expected, the stock price should increase. It is not necessary to increase dividends to have a favorable stock price reaction.Case 3: Stock dividends do not provide any economic valuebut they may have a signal effect and are often associated with increases in cash dividends. As a result, stock dividends do not appear to directly cause an increase in stock price but are often associated with factors that do impact favorably on price.Req.2Stock prices react to underlying economic events and not changes in reporting methods, per se. Markets are relatively effective in recognizing the differencebetween profits generated by operations and profits generated by the use of liberal accounting policies.。
财务会计(英)答案
1-10Owners' equity is also called capital (for proprietorships and partnerships) and shareholders' equity or stockholders' equity (for corporations).
1-3Examples of decisions that are likely to be influenced by financial statements include choosing where to expand or reduce operations, lending money, investing ownership capital, and rewarding mangers.
1-17CPA is a Certified Public Accountant. One becomes a CPA by a combination of education, qualifying experience, and the passing of a two-day national examination.
1-16The board of directors is the link between stockholders and the actual managers. It is the board’s duty to ensure that managers act in the interests of shareholders.