
财务分析-英国布里斯托大学财务分析课程 精品
The Capital Market: Trading value
The Investors: The claimants on value
Debtholders
Cash from Secondary sale of debt Debtholders
Operating activities Investing activities Financing activities
• long-term perspective as opposed to short-term gain
Dot-com bubble: Dell illustration
• Late 1990’s: unlimited faith in prospect of new technology and internet firms; bubble burst in 2001
• For the y/e 2000 Dell had reported earnings of $1.7 billion on sales of $25.3 billion. The MV of Dell’s shares at the time was $146.4 billion – 3 * the MV of GMC and Ford Motor Company combined (P/E 8.5 / 5.0 respectively)
What are we doing?
Part of fundamental analysis: • Financial statement analysis and valuation of shares so as to give
well informed investment advice to an equity investor.
• Personal gains:
– If markets are not efficient, the proper analysis helps in identifying mispriced companies.
– 1980’s: market efficiency paradigm widely accepted → passive investment
• Financial analysis – Analysis of financial performance and financial position using ratio and cash flow analysis
Process of fundamental analysis
• Forecasting the future – Forecasting of payoffs through forecasts of balance sheet, income statement and cash flows
• Dell’s shares traded at a P/E of 87.9!
• Despite healthy trading and forecasted growth Dell’s stock appeared over-valued. – In 2000 the per share stock price fell from $58 in early 2000 to $29 in 2003. The price had only recovered to $40 in 2005.
– Evidence of market inefficiency → active investment and a renewed interest in fundamental analysis (Warren Buffet)
– Fundamental analysis:
• anchoring on reliable information (accounting) rather than rumours and speculations;
Understanding the Past
Business analysis Accounting analysis
Financial analysis Forecasting Valuation
Trading on the valuation
Process of fundamental analysis
- Ryanair case: good preparation for the coursework
- Exercises: For your own work
- Tutorials: good preparation for the exam
- Coursework
Nikola.Petrovic@ Thursday, 13-14.00 Friday, 11.30-12.30 1B14
Week 12
A Framework for Fundamental Analysis
Business Analysis
BusiThe firm: The value generator
Cash from loans
Interest and loan payments
– Surviving firms reported earnings turned out to be a better indicator of future performance
– Most of the intangible assets disappeared
– The much-criticised SoFP (B/S) also provided good forecasts.
• Similar to what sell-side equity within brokerage houses are doing (as opposed to buy-side analysts affiliated with institutional investors)
• Final product: equity research report
Cash from share issues
Dividends and cash from share repurchases
Shareholders
Cash from Secondary sale of shares Shareholders
Source: Penman, p. 8
What are we doing?
They are doing: • Fundamental analysis: contextual analysis of all publicly available
information in order to value the company.
• Technical analysis: spotting share price time-series patterns in order to predict movement of prices.
• Business analysis – Economic factors – Industry structure – Competitive strategy – Corporate strategy
• Accounting analysis – Evaluation of the extent to which a firm’s accounting captures the underlying business reality – Understanding accounting distortions
• Note of caution in regard of financial statement analysis:
– Financial statement analysis can be done for various purposes: credit analysis, competitive benchmarking, analysis of mergers and acquisitions, etc.
• Financial analysts are: – information intermediaries; they digest information and provide summary information to the public/less sophisticated investors. – especially important where capital markets are well developed.
Dot-com bubble: The role of financial statements
• The role of F/S is to “anchor the investor on the rising tide of speculation” with hard information – Earnings did matter! Losses reported by new economy firms during the bubble turned out to be a good predictor of failure
Dot-com bubble: What were the analysts doing?
• They were riding the wave: – involved in short-term speculation of the market mood rather than providing more sober picture to their clients based on fundamentals of the companies. – Analysis based on internet clicks that do not generate any income
财务分析概述培训brlp
⑷、社会公众股(A股):是社会公众以合法收入投入公司形成的 股份。
⑸、 B股:是外资股东持有的在国内二级市场发行的人民币特种股 票。
⑹、H股:是在香港联交所上市的内地企业股票。 ⑺、转配股:指企业在增资配股时,国有股股东或法人股股东放弃
职工持股数额较少,并且,一二级市场巨大的溢 价差额使得职工对公司治理的兴趣不大。
出于对公司治理失败可能影响自身职业安全的考 虑,他们可能对公司治理施加正向作用。
(4)、可流通社会公众股股东
一般而言,个人持股者是自然人,具有追 求利益最大化的动机,但由于公司的个人股东日 益零散化,监控的成本与效益不匹配的原因,大 多数个人股东或者采用搭便车的行为来减少自己 的治理成本,或者采取用脚投票的方式来制约公 司管理层,即依靠股票的流动性带来的收购接管 行为对公司高级管理人员起到监督作用。
财务分析概述
一、财务分析的作用 财务分析作为一门实践性的课程,具有
相当的实用性。对在校的学生而言,更是有 实际意义 1、找工作。怎样看懂一个公司的报表? 2、新行业的需要。如担保业
财务分析概述
二、学科特点 1、思维要发散。分析是观察和推理的演绎。 福尔摩斯是高手:
“这一位先生,具有医务工作者的风度,但却是一副军人气概。那么,显见他是 个军医。他刚从热带回来,因为他脸色黝黑,但是,从他手腕的皮肤黑白分明看 来,这并不是他原来的肤色。他面容憔悴,这就清楚地说明他是久病未愈而又历 尽了艰苦。他左臂受过伤,现在动作起来还有些僵硬不便。试问,一个英国的军 医在热带地方历尽艰苦,并且左臂负过伤,这能在什么地方呢?自然只有在阿富 汗。”
5、消费模式
6、教育水平,等
英国布里斯托大学财务分析课程
• Financial analysis – Analysis of financial performance and financial position using ratio and cash flow analysis
英国布里斯托大学财务分析课程
Process of fundamental analysis
• Business analysis – Economic factors – Industry structure – Competitive strategy – Corporate strategy
• Accounting analysis – Evaluation of the extent to which a firm’s accounting captures the underlying business reality – Understanding accounting distortions
They are doing: • Fundamental analysis: contextual analysis of all publicly available
information in order to value the company.
财务分析课程教学大纲

《财务分析》课程教学大纲课程代号:3206120总学时: 36学时(讲授/理论30 学时,上机/课外实践 6 学时)适用专业:财务管理专业先修课程:会计学基础、中级财务会计、财务管理、经济学、管理学一、本课程地位、性质和任务地位:本课程是财务管理专业学生专业选修课程。
性质:本课程综合性、操作性很强,具有一定的实用性。
主要介绍财务报告分析的基本理论、基本方法和基本技能,在对企业财务状况、经营成果、现金流量进行分析和评价的基础上,应用综合分析方法对企业进行综合分析。
任务:通过教学,使学生能够具备财务报告分析的基本能力。
要求学生了解会计的基本理论,掌握财务分析的基本原理和基本方法,能够运用所学知识,利用企业所提供的会计报表,对企业的财务状况、经营成果和现金流量进行分析和评价,并写出财务分析报告,从而为经济决策提供依据。
二、课程教学的基本要求通过教学,使学生了解财务报告分析的内容、程序和基本方法,了解四张主表的概念、性质、作用、结构,了解财务综合分析的方法,掌握四张主表的会计分析,掌握被粉饰报表的识别的基本方法,掌握财务能力分析、杜邦分析体系、财务分析报告的编写。
三、课程学时分配、教学要求及主要内容(一)课程学时分配一览表(二)课程教学要求及主要内容第一讲财务分析概述教学目的和要求:了解财务分析的产生与发展,财务分析的主体与目的,财务分析的信息资料基础,财务分析的程序与方法;理解财务分析的内涵,会计分析与财务分析的区别与联系,财务分析的体系与内容;掌握财务分析的方法。
教学重点和难点:1. 财务报告分析的产生与发展2. 财务分析的内涵3. 会计分析与财务分析4. 财务分析的体系与内容5. 财务分析的方法教学内容:一、财务分析的产生与发展1、财务分析的内涵2、财务分析的产生与发展3、我国财务分析的发展二、财务分析的主体与目的三、财务分析的体系与内容1、美国理论界关于财务分析体系的几种安排2、我国财务分析体系与内容构建四、财务分析的信息资料基础1、财务分析信息的种类2、财务分析信息的要求3、财务分析评价标准信息4、认识外部信息(政策与市场信息)的重要性5、财务报告的内涵与作用6、财务分析法规与政策依据五、财务分析的程序与方法1、财务分析的基本程序与步骤2、财务分析的基本方法比较分析法、比率分析法、趋势分析法(也称水平分析法)、因素分析法、图解分析法第二讲资产负债表分析教学目的和要求:了解资产负债表的概念、性质、作用、结构;理解资产负债表各项目的经济内涵,资产负债表分析的局限性;掌握资产负债表的水平分析法、垂直分析法。
英国名校布里斯托大学财务分析和证券估值课程6
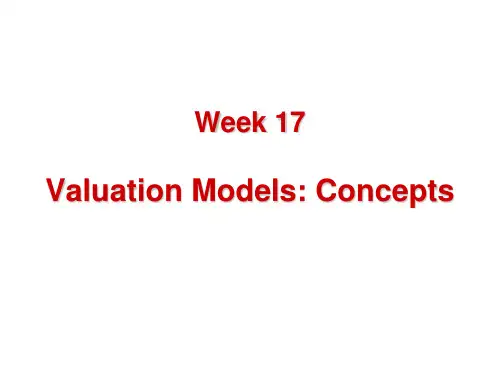
V0 B0
E
T
REt (1 r e )
t
t 1
2. If we assume that abnormal profits in terminal period can be earned only on existing projects at that time, and that any new projects will earn ROE =cost of equity, then:
Forecasting base models
• Direct – Cash-flow based: Dividend discount model (DDM) – Residual earnings model – Abnormal earnings growth model • Indirect – Cash-flow based: Discounted cash flow model (DCF) – Residual operating income model – Abnormal operating income growth model
财务分析综合概述bsmy
偿债能力的重要性
偿债能力是判断企业财务状况稳定与否的重要标志:
偿债能力强,对债务人(企业)而言,可以举债筹集资 金、扩大生产规模、增加投资力度、调整资本结构、获 取财务杠杆收益;对债权人而言,可以保证其债权本息 能够及时足额得以偿还。
偿债能力弱,会造成企业和债权人双方的财务危机,同 时使企业面临破产清算的风险。
到期债务本息偿付比率反映本期经营活动所产生的现 金净流量足以抵付本期到期债务本息的倍数,企业要 持续经营下去,该指标至少>1。
到期债务本息偿付比率是企业破产风险的财务预警指标。
2、长期偿债能力分析
长期偿债能力:企业偿还长期债务的能力,关系到企
业长期债权人和所有者的利益,应从企业短期偿债能 力、获利能力与资本结构三方面着手分析。
现金流量比率(Cash Flow Ratio)
企业的经营活动现金净流量与流动负债的比率。
现金流量比率
经营活动现金净流量 流动负债
现金流量比率反映本期经营活动所产生的现金净流量 足以抵付流动负债的倍数,0.4较为正常。
局限性:
经营活动现金流量是过去一个会计年度的经营结果; 流动负债是未来一个会计年度需要偿还的债务。 二者的会计期间不一致,该比率未考虑未来一个会计 年度影响经营活动现金流量变动的因素。
对企业财务风险的影响大
流动比率(Current Ratio)
企业的流动资产与流动负债的比率。
流动比率
流动资产 流动负债
流动比率越高,企业短期偿债能力越强。 流动比率过高,会影响企业的获利能力。 流动比率在2:1左右最为合适。
行业 零售业(应收账款少):流动比率<2,正常 特点 制造业(存货多):流动比率>2,正常
长期负债因为数额较大,其本金的偿还必须有一种积 累的过程。从长期来看,企业所有的盈利应最终反映
英国名校布里斯托大学财务分析和证券估值课程5

• Alternatively, in step 3 use: Share price calculated using direct method x number of shares
Cost of capital
Important ! • Circularity problem: current share price is used to calculate WACC for the purpose of the valuation of these same shares. If you use current/observed share price to calculate WACC, then direct and indirect valuation methods will give different share price estimates because of the inconsistency in which fair value of the firm is calculated. There isn’t much you can do about it.
Cost of capital
• The cost of capital for equity is really derived from the cost of capital for operations (not vice versa) Rearranging WACC formula, it can be obtained:
Cost of capital
• Operations have their own risk, referred to as operational risk calculated as weighted average cost of capital
英国名校布里斯托大学财务分析和证券估值课程5
Forecasting the future
Changes in macroeconomic factors
Forecasted economic variables
Business analysis
Industry operation and key industry statistics Industry structure (Porter’s 5 forces) Firm’s strategy (differentiation, cost leadership, focus) and synergy effects; SWOT
Week 16
Forecasting
Process of fundamental analysis
Business analysis
Understanding the Past
Accounting analysis
Financial analysis
Forecasting
Valuation
Trading on the valuation
Forecasted financial statements
Forecasted ratios
Forecasting horizon
Terminal period assumptions
Forecasting framework
Forecast sales Forecast margins Forecast depreciation rate Operating expenses Financial expense Forecast interest rate Forecast tax rate Tax expense Pro Forma Income Statement Pro Forma Cash Flow Statement Forecast distribution to equity holders Pro Forma SoFP Net financial obligations Net operating assets Forecast leverage Forecast turnover
财务分析(双语课)
财务分析(双语课)Financial Analysis (双语课)财务分析是指从财务角度对企业经营状况进行的分析,旨在揭示企业的财务状况、盈利能力、偿债能力、运营能力等方面的情况。
Financial analysis refers to the analysis of enterprise operating conditions from a financial perspective, aiming to reveal the company's financial status, profitability, debt repayment ability,and operational capabilities.财务分析的四大基本原则包括全面、系统性、定量化和相对性,通过对财务报表上的数据进行处理和分析,产生出一系列重要的财务比率和指标,这些指标可以帮助投资者、债权人、政府、分析师等各种利益相关者更好地理解企业的财务状况和运营状况,从而做出更加合理的决策。
The four basic principles of financial analysis include comprehensiveness, systematicity, quantification, and relativity.By processing and analyzing the data on financial statements, a series of important financial ratios and indicators are generated. These indicators can help investors, creditors, governments, analysts and other stakeholders to better understand the financial and operational conditions of enterprises, and make more reasonable decisions.财务分析的核心就是利用财务比率和指标,对企业的财务状况、盈利能力、偿债能力、运营能力等方面的情况进行分析,以此评估企业的投资价值和风险程度。
英国名校布里斯托大学财务分析和证券估值课程8
V N O A /N O A = 3
6.0
V N O A /N O A = 2 .5
Week 19
Relative Valuation
Valuation models classification
Valuation models
No forecasting
Forecasting
Real options
Asset-based
Relative Valuation
Cash Flow based
Application: Investment companies Natural resource companies (minerals, oil, timberland) Break-up (liquidation) value
Valuation multiples
Idea: How to compare the valuation of the companies? Share price is not a good summary itself, since it depends on number of shares issued – two otherwise identical companies can have different share price if they have different numbers of share issued Solution: scale share price by some accounting variable or some other industry-specific measure Price multiples commonly reported in the financial press, on-line, etc… The firms with higher multiples considered to be more valuable.
英国留学财务分析报告(3篇)
第1篇一、引言随着全球化的推进,越来越多的中国学生选择出国留学,英国作为世界教育强国之一,吸引了大量中国留学生。
然而,留学英国所需费用较高,对于家庭经济条件一般的学生来说,留学费用的规划和管理显得尤为重要。
本报告将对英国留学的财务状况进行分析,旨在帮助有意向留学英国的学生及其家庭做好财务准备。
二、英国留学费用构成1. 学费英国留学的学费是留学费用中的主要部分。
不同院校、不同专业、不同学位的学费存在较大差异。
以下是一些常见留学费用的参考:(1)本科:英国本科课程学费一般在每年1.5万至3万英镑之间,医学、工程等专业学费较高,可达4万至5万英镑。
(2)硕士:英国硕士课程学费一般在每年1.5万至3万英镑之间,商科、工程、医学等专业学费较高,可达4万至5万英镑。
2. 生活费英国留学的生活费包括住宿费、餐饮费、交通费、书籍费、医疗保险等。
以下是一些生活费用的参考:(1)住宿费:英国留学生住宿费用较高,不同类型住宿费用差异较大。
以下是一些参考:- 校园宿舍:每年约5000至9000英镑。
- 私人租房:每年约5000至1.5万英镑。
- 学生公寓:每年约4000至8000英镑。
(2)餐饮费:英国留学生每月餐饮费用约为200至400英镑。
(3)交通费:英国留学生每月交通费用约为100至200英镑。
(4)书籍费:英国留学生每年书籍费用约为200至500英镑。
(5)医疗保险:英国留学生每年医疗保险费用约为200至400英镑。
3. 其他费用(1)签证费用:英国留学生签证费用约为3000元人民币。
(2)机票费用:往返英国机票费用约为5000至10000元人民币。
(3)保险费用:英国留学生保险费用约为1000至2000元人民币。
三、英国留学财务规划1. 家庭收入分析在制定留学财务规划之前,家庭应先分析自身经济状况。
家庭收入包括父母工资、家庭其他收入等。
家庭收入应满足以下条件:(1)家庭收入足以支付留学期间的学费、生活费等费用。