
ACCAF5考试真题答案
AnswersFundamentals Level – Skills Module, Paper F5Performance Management December 2014 Answers Section A1 ADivision A: Profit = $14·4m x 30% = $4·32mImputed interest charge = $32·6m x 10% = $3·26mResidual income = $1·06mDivision B: Profit = 8·8m x 24% = $2·112mImputed interest charge = $22·2m x 10% = $2·22mResidual income = $(0·108)m2 3 4 5 DAll costs are included when using life cycle costing.AThis is the definition of a basic standard.BThe first statement is describing management control, not strategic planning.CNumber of units required to make target profit = fixed costs + target profit/contribution per unit of P1. Fixed costs = ($1·2 x 10,000) + ($1 x 12,500) – $2,500 = $22,000.Contribution per unit of P = $3·20 + $1·20 = $4·40.($22,000 + $60,000)/$4·40 = 18,636 units.6 AProduct A B C DSelling price per unitRaw material costDirect labour cost at $11 per hour Variable overhead cost Contribution per unit $160$24$66$24$214$56$88$18$100$22$33$24$140$40$22$18 $46 $52 $21 $60 ––––––––––––––––Direct labour hours per unit Contribution per labour hour Rank6$7·6728$6·5043$72$3013Normal monthly hours (total units x hours per unit) 1,800 1,000 720 800 If the strike goes ahead, only 2,160 labour hours will be available.Therefore make all of D, then 1,360 hours’ worth of A (2,160 – 800 hrs).7 8 B460 – 400 = 60 clients$40,000 – $36,880 = $3,120VC per unit = $3,120/60 = $52Therefore FC = $40,000 – (460 x $52) = $16,080BIncrease in variable costs from buying in (2,200 units x $40 ($140 – $100)) = $88,000 Less the specific fixed costs saved if A is shut down = ($10,000)Decrease in profit = $78,000Only the first statement is correct. Traditional absorption costing tends to over-allocate costs to high volume products, not under-allocate them.1011 BBy definition, a shadow price is the amount by which contribution will increase if an extra kg of material becomes available. 20 x $2·80 = $56.CNeither statement is correct. Responsibility is not assigned solely to senior managers as, for example, in a TQM environment quality is everybody’s responsibility. In addition, standard costing can be difficult to apply in dynamic situations.1213 AThe second statement is talking about flow cost accounting, not input/output analysis.DTarget 1 is a financial target and so assesses economy factors. Target 2 is measuring the rate of work handled by staff which is an efficiency measure. Target 3 is assessing output, so is a measure of effectiveness.1415 BIn comparison to participative budgeting, an advantage of non-participative budgeting is that it should be less time consuming, as less collaboration will be required in order to produce the budgets.CThe target costing process always begins with the target selling price being set. The required profit is then determined and deducted from the target selling price to estimate the target cost. The target cost is then compared to the estimated current cost and the cost gap is then calculated.1617 AThis is a description of an incremental budget.ANew profit figures before salary paid:Good manager: $180,000 x 1·3 = $234,000Average manager: $180,000 x 1·2 = $216,000Poor: $180,000 x 1·1 = $198,000EV of profits = (0·35 x $234,000) + (0·45 x $216,000) + (0·2 x $198,000) = $81,900 + $97,200 + $39,600 = $218,700 Deduct salary cost and EV with manager = $178,700Therefore do not employ manager as profits will fall by $1,300.18 BSet-up costs per production run = $140,000/28 = $5,000Cost per inspection = $80,000/8 = $10,000Other overhead costs per labour hour = $96,000/48,000 = $2 Overheads costs of product D:$Set-up costs (15 x $5,000) Inspection costs (3 x $10,000) Other overheads (40,000 x $2)75,000 30,000 80,000 ––––––––185,00020 This is an example of feedforward control as the manager is using a forecast to assist in making a future decision.AIf demand is inelastic or the product life cycle is short, a price skimming approach would be more appropriate.1 Chair Co(a) Learning curve formula = y = ax bCumulative average time per unit for 8 units: Y = 12 x 8–·415 = 5·0628948 hours.Therefore cumulative total time for 8 units = 40·503158 hours. Cumulative average time per unit for 7 units: Y = 12 x 7–·415 = 5·3513771 hours.Therefore cumulative total time for 7 units = 37·45964 hours.Therefore incremental time for 8th unit = 40·503158 hours – 37·45964 hours = 3·043518 hours. Total labour cost for 8th unit =3·043518 x $15 = $45·65277 Material and overheads cost per unit = $230 Therefore total cost per unit = $275·65277 Therefore price per unit = $413·47915 (b) (i)Actual learning rate Cumulative number ofseats produced 1 2 4 8Cumulative totalCumulative averagehours per unit 12·5 12·5 x r 12·5 x r 2 hours 12·5 ? ? 34·312·5 x r 3Using algebra: 34·3 = 8 x (12·5 x r 3)4·2875 = (12·5 x r 3) 0·343 = r 3 r = 0·70The learning effect was 70% as compared to the forecast rate of 75%, meaning that the labour force learnt more quicklythan anticipated. (ii) Adjusted priceThe adjusted price charged will be lower than the original price calculated in part (a). This is because the incremental cost of the 8th unit will be lower given the 70% learning rate, even though the first unit took 12·5 hours. We know this because we are told that the cumulative time for 8 units was actually 34·3 hours. This is lower than the estimated cumulative time in part (a) for 8 units of 40·503158 hours and therefore, logically, the actual incremental time for the 8th unit must be lower than the estimated 3·043518 hours calculated in part (a). Consequently, total cost will be lower and price will be lower, given that this is based on cost.2 Glam CoBottleneck activity(a) The bottleneck may have been worked out as follows:Total salon hours = 8 x 6 x 50 = 2,400 each year. The capacity for each senior stylist must be 2,400 hours, which equates to 2,400 cuts each year (2,400/1). Since there are three senior stylists, the total capacity is 7,200 hours or 7,200 cuts each year. Using this method, the capacity for each activity is as follows: Cut Treatment 16,000 4,800 Assistants Senior stylists Junior stylists48,000 7,200 9,6009,600The bottleneck activity is clearly the work performed by the senior stylists.The senior stylists’ time is called a bottleneck activity because it is the activity which prevents the salon’s throughpu t from being higher than it is. The total number of cuts o r treatments which can be completed by the salon’s senior stylists is less than the number which can be completed by other staff members, considering the number of each type of staff available and the time required by each type of staff for each client.(b) TPARCut $ Treatment$Selling price 60 110MaterialsThroughputThroughput per bottleneck hour Total salon costs per BN hour (w1) TPAR0·6059·4059·4042·561·48 (7·40+0·6)1026842·561·6Working 1: Total salon costs(3 x $40,000) + (2 x $28,000) + (2 x $12,000) + $106,400 = $306,400Therefore cost for each bottleneck hour = $306,400/7,200 = $42·56Note: Answers based on total salary costs were $80,000 were also equally acceptable since the wording of question was open to interpretation.3 Hi Life CoDirect materials: FabricWoodNote12$ 200 m2 at $17·50 per m220 m at $8·20 per m30 m at $8·50 per m3,5001642552Direct labour:SkilledSemi-skilledFactory overheads Administration overheads 50 hours at $24 per hour300 hours at $14 per hour20 hours at $15 per hour34561,2004,200300–––––––Total cost 9,619––––––1 2 Since the material is in regular use by HL Co, it is replacement cost which is the relevant cost for the contract.30 m will have to be ordered from the alternative supplier for immediate delivery but the remaining 20 m can be used from inventory and replaced by an order from the usual supplier at a cost of $8·20 per m.3 4 5 There is no cost for the first 150 hours of labour because there is spare capacity. The remaining 50 hours will be paid at time and a half, which is $16 x 1·5, i.e. $24 per hour.HL Co will choose to use the agency workers, who will cost $14 per hour, since this is cheaper than paying existing semi-skilled workers at $18 per hour ($12 x 1·5) to work overtime.None of the general factory costs are incremental, so they have all been excluded. However, the supervisor’s overtime pay is incremental, so has been included. The supervisor’s normal salary, on the other hand, h as been excluded because it is not incremental.6 These are general overheads and are not incremental, so no value should be included for them.4 Jamair(a) The four perspectivesFinancial perspective – this perspective is concerned with how a company looks to its shareholders. How can it create value for them? Kaplan and Norton identified three core financial themes which will drive the business strategy: revenue growth and mix, cost reduction and asset utilisation.Customer perspective – this co nsiders how the organisation appears to customers. The organisation should ask itself: ‘to achieve our vision, how should we appear to our customers?’ The customer perspective should identify the customer and market segments in which the business will compete. There is a strong link between the customer perspective and the revenue objectives in the financial perspective. If customer objectives are achieved, revenue objectives should be too.Internal perspective – this requires the organ isation to ask itself: ‘what must we excel at to achieve our financial and customer objectives?’ It must identify the internal business processes which are critical to the implementation of the organisation’s strategy. These will include the innovation process, the operations process and the post-sales process.Learning and growth perspective – this requires the organisation to ask itself whether it can continue to improve and create value. The organisation must continue to invest in its infrastructure – i.e. people, systems and organisational procedures – in order to improve the capabilities which will help the other three perspectives to be achieved.(b) Goals and measuresFinancial perspectiveGoal Performance measureTo use fewer planes to transport customers Lease costs of plane per customerExplanation – operating efficiency will be driven by getting more customers on fewer planes. This goal and measure cover the cost side of this.Goal Performance measureTo increase seat revenue per plane Revenue per available passenger mileExplanation – this covers the first part of achieving operating efficiency – by having fewer empty seats on planes.Customer perspectiveGoal Performance measureTo ensure that flights are on time ‘On time arrival’ ranking from the aviation authorityExplanation – Jamair is currently number 7 in the rankings. If it becomes known as a particularly reliable airline, customers are more likely to use it, which will ultimately increase revenue.Goal Performance measureTo reduce the number of flights cancelled The number of flights cancelledExplanation – again, if flights are seen to be cancelled frequently by Jamair, customers will not want to use it. It needs to be perceived as reliable by its customers.Internal perspectiveGoal Performance measureTo improve turnaround time on the ground ‘On the ground’ timeExplanation – less time spent on the ground means fewer planes are needed, which will reduce plane leasing costs. However, it is important not to compromise the quality of cleaning or make errors in refuelling as a consequence of reducing on the ground time.Goal Performance measureTo improve the cleanliness of Jamair’s planes The percentage of customers happy with the standard of the planes,as reported in the customer satisfaction surveys.Explanation –at present, only 85% of customers are happy with the standard of cleanliness on Jamair’s planes. This could be causing loss of revenue.Goal Performance measureTo develop the online booking system Percentage downtime.Explanation – since the company relies entirely on the booking system for customer booking of flights and check-in, it is critical that it can deal with the growing number of customers.Learning perspectiveGoal Performance measureTo reduce the employee absentee rate The number of days absent per employeeExplanation – it is critical to Jamair that its workforce is reliable as, at worse, absent staff lead to cancelled flights.Goal Performance measureNumber of days’ training per ground crew member To increase ground crew training on cleaning andrefuelling proceduresExplanation – if ground crew are better trained, they can reduce the number of minutes that the plane stays on the ground, which will result in fewer planes being required and therefore lower costs. Also, if their cleaning is better, customer satisfaction and retention will increase.Note: Only one goal and measure were required for each perspective. In order to gain full marks, answers had to be specific to Jamair as stated in the requirements.5 Safe Soap Co(a) Variance calculationsMix varianceTotal kg of materials per standard batch = 0·25 + 0·6 + 0·5 = 1·35 kgTherefore standard quantity to produce 136,000 batches = 136,000 x 1·35 kg = 183,600 kgActual total kg of materials used to produce 136,000 batches = 34,080 + 83,232 + 64,200 = 181,512 kgMaterial Actual quantityStandard mixkgs181,512 x 0·25/1·35 = 33,613·33181,512 x 0·6/1·35 = Actual quantityActual mixkgs34,08083,232Variance Standard costper kgVariancekgs(466·67)(2,560)$104$(4,666·70)(10,240)LyeCoconut oil Shea butter80,672181,512 x 0·5/1·35 = 67,226·67 64,200 3,026·67 3 9,080·01––––––––––––––––––––––––––181,512 181,512 (5,826·69)A––––––––––––––––––––––––––Yield varianceMaterial Standard quantityStandard mix Actual quantityStandard mixkgs33,613·3380,672Variance Standard costper kgVariancekgs386·67928$104$3,866·703,712Lye Coconut oil Shea butter 0·25 x 136,000 =0·6 x 136,000 =0·5 x 136,000 =34,00081,60068,000 67,226·67 773·33 3 2,319·99––––––––183,600––––––––––––––––––181,512 9,898·69F––––––––––––––––––––––––––(b) (i) A materials mix variance will occur when the actual mix of materials used in production is different from the standardmix. So, it is inputs which are being considered. Since the total mix variance is adverse for the Safe Soap Co, this means that the actual mix used in September and October was more expensive than the standard mix.A material yield variance arises because the output which was achieved is different from the output which would havebeen expected from the inputs. So, whereas the mix variance focuses on inputs, the yield variance focuses on outputs.In both September and October, the yield variance was favourable, meaning that the inputs produced a higher level of output than one would have expected.(ii) Whilst the mix and yield variances provide Safe Soap Co with a certain level of information, they do not necessarily explain any quality issues which arise because of the change in mix. The consequences of the change may well have an impact on sales volumes. In Safe Soap Co’s case, the sales volume variance is adverse, meaning that sales volumes have fallen in October. It is not known whether they also fell in September but it would be usual for the effects on sales of the change in mix to be slightly delayed, in this case by one month, given that it is only once the customers start receiving the slightly altered soap that they may start expressing their dissatisfaction with the product.There may also be other reasons for the adverse sales volume variance but given the customer complaints which have been received, the sales manager’s views should be taken on b oard.Fundamentals Level – Skills Module, Paper F5Performance Management December 2014 Marking Scheme Section A Marks2 marks per question 40––––––Section B1 (a) PriceCumulative average time per unit for 8 units Total time for 8 unitsCumulative average time per unit for 7 units Total time for 7 unitsIncremental time for 8th unitCost for 8th unitTotal cost1 0·5 1 0·5 0·5 0·5 0·5Price 0·5–––5–––(b) (i) Learning rateCalculating learning rate Saying whether better or worse 2·5 0·5 –––3 –––(ii) Effect on price 2–––Total marks 10––––––2 (a)(b) Calculation and justification of bottleneckExplanation of bottleneck31–––4–––TPARThroughput 1111 Throughput per bottleneck hourTotal salon costsCost per hourTPAR 2–––6–––Total marks 10––––––3 Fabric calculationFabric reasonWood calculation 0·5 0·5 1Wood reason 1Skilled labour calculation Skilled labour reason 1 1Semi-skilled labour calculationSemi-skilled labour reasonFactory overheads calculationFactory overheads reason Administration overheads reasonTotal relevant cost (lowest cost estimate) 0·5 1 0·5 1·5 1 0·5 –––Total marks 10––––––精品文档Marks4 (a)(b) PerspectivesExplanation for each perspective 1·5–––6–––Goals and measuresEach goal/measure/explanationPresentation and structure21–––9–––Total marks 15––––––5 (a)(b) Variance calculationsMix varianceQuantity variance44–––8–––(i) VariancesMarks per variance explained 2–––4–––(ii) DiscussionPer valid point 1–––3–––Total marks 15––––––。
ACCA资料 真题 f5_2014_jun_a

Fundamentals Level – Skills Module, Paper F5Performance Management June 2014 Answers 1(a)Full budgeted production cost per unit using absorption costingProduct X Y Z TotalBudgeted annual production (units)20,00016,00022,000Labour hours per unit2·532T otal labour hours50,00048,00044,000142,000Overhead absorption rate = $1,377,400/142,000 = $9·70 per hour.Product X Y Z$ per unit$ per unit$ per unitDirect materials252822Direct labour303624Overhead ($9·70 x 2·5/3/2)24·2529·1019·40––––––––––––––––––Full cost per unit79·2593·1065·40––––––––––––––––––(b)Full budgeted production cost per unit using activity based costingProduct X Y Z TotalBudgeted annual production (units)20,00016,00022,000Batch size500800400Number of batches (i.e. set ups)402055115Number of purchase orders per batch454Total number of orders160100220480Machine hours per unit1·51·251·4Total machine hours30,00020,00030,80080,800Cost driver rates:Cost per machine set up$280,000/115 = $2,434·78Cost per order$316,000/480 = $658·33Cost per machine hour($420,000 + $361,400)/80,800 = $9·67Allocation of overheads to each product:Product X Y Z Total$$$Machine set up costs97,39148,696133,913280,000Material ordering costs105,33365,833144,834316,000Machine running and facility costs290,100193,400297,836781,336*––––––––––––––––––––––––––––––––––T otal492,824307,929576,5831,377,336––––––––––––––––––––––––––––––––––Number of units produced20,00016,00022,000Overhead cost per unit$24·64$19·25$26·21Total cost per unit:$ per unit$ per unit$ per unitDirect materials252822Direct labour303624Overhead24·6419·2526·21––––––––––––––––––ABC cost per unit79·6483·2572·21––––––––––––––––––*A difference of $64 arises here as compared to the cost pool total of $781,400 because of rounding differences. This has been ignored.(c)When activity based costing is used, the cost for product X is very similar to that cost calculated using full absorption costing.This means that the price for product X is likely to remain unchanged because cost plus pricing is being used. Demand for product X is relatively elastic but since no change in price is expected, sales volumes are likely to remain the same if ABC is introduced.However, the cost for product Y is almost $10 per unit less using ABC. This means that the price of product Y will go down if cost plus pricing is used. Given that demand for product Y is also elastic, like demand for product X, a reduced selling price is likely to give rise to increased sales volumes.The cost of product Z is nearly $7 per unit more using ABC and the price of product Z will therefore go up if ABC is used.Given that demand for product Z is relatively inelastic, this means that sales volumes would be expected to be largely unchanged despite an increase in price.2(a)Optimum production planDefine the variablesLet x = number of units of Xeno to be produced.Let y = number of units of Yong to be produced.Let C = contribution.State the objective functionC = 30x+ 40yState the constraintsBuild time: 24x + 20y ≤1,800,000Program time: 16x + 14y ≤1,680,000T est time: 10x + 4y ≤720,000Non-negativity constraints:x, y ≥0Sales constraintsx ≤85,000y ≤66,000Draw the graphBuild time:If x = 0, y = 1,800,000/20 = 90,000If y = 0, x = 1,800,000/24 = 75,000Program time:If x = 0, y = 1,680,000/14 = 120,000If y = 0, x = 1,680,000/16 = 105,000Test time:If x = 0, y = 720,000/4 = 180,000If y = 0, x = 720,000/10 = 72,000Solve using the iso-contribution lineIf y = 40,000, C = 40,000 x $40 = $1,600,000If C = $1,600,000 and y = 0, x = $1,600,000/$30 = 53,333·333(a)Ratios(i)ROCE = operating profit/capital employed x 100%$’000ROCEW Co Design division6,000/23,54025·49%Gearbox division3,875/32,32011·99%C Co7,010/82,9758·45%(ii)Asset turnover = sales/capital employed x 100%$’000Asset turnoverW Co Design division14,300/23,5400·61Gearbox division25,535/32,3200·79C Co15,560/82,9750·19(iii)Operating profit margin = operating profit/sales x 100%$’000Operating profitW Co Design division6,000/14,30041·96%Gearbox division3,875/25,53515·18%C Co7,010/15,56045·05%Both companies and both divisions within W Co are clearly profitable. In terms of what the different ratios tell us, ROCE tells us the return which a company is making from its capital. The Design division of W Co is making the highest return at over 25%, more than twice that of the Gearbox division and nearly three times that of C Co. This is because the nature of a design business is such that profits are largely derived from the people making the designs rather than from the assets. Certain assets will obviously be necessary in order to produce the designs but it is the employees who are mostly responsible for generating profit.The Gearbox division and C Co’s ROCE are fairly similar compared to the Design division, although when comparing the two in isolation, the Gearbox division’s ROCE is actually over three percentage points higher than C Co’s (11·99% compared to 8·45%). This is because C Co has a substantially larger asset base than the Gearbox division.From the asset turnover ratio, it can be seen that the Gearbox division’s assets generate a very high proportion of sales per $ of assets (79%) compared to C Co (19%). This is partly because the Gearbox division buys its components in from C Co and therefore does not need to have the large asset base which C Co has in order to make the components. When the unit profitability of those sales is considered by looking at the operating profit margin, C Co’s unit profitability is much higher than the Gearbox division (45% operating profit margin as compared to 15%). The Design division, like the Gearbox division, is also using its assets well to generate sales (asset turnover of 61%) but then, like C Co, its unit profitability is high too (42% operating profit margin.) This is why, when the two ratios (operating profit margin and asset turnover) are combined to make ROCE, the Design division comes out top overall – because it has both high unit profitability and generates sales at a high level compared to its asset base.It should be noted that any comparisons between such different types of business are of limited use. It would be more useful to have prior year figures for comparison and/or industry averages for similar businesses. This would make performance review much more meaningful.(b)Transfer pricesFrom C Co’s perspectiveC Co transfers components to the Gearbox division at the same price as it sells components to the external market. However,if C Co were not making internal sales then, given that it already satisfies 60% of external demand, it would not be able to sell all of its current production to the external market. External sales are $8,010,000, therefore unsatisfied external demand is ([$8,010,000/0·6] –$8,010,000) = $5,340,000.From C Co’s perspective, of the current internal sales of $7,550,000, $5,340,000 could be sold externally if they were not sold to the Gearbox division. Therefore, in order for C Co not to be any worse off from selling internally, these sales should be made at the current price of $5,340,000, less any reduction in costs which C Co saves from not having to sell outside the group (perhaps lower administrative and distribution costs).As regards the remaining internal sales of $2,210,000 ($7,550,000 –$5,340,000), C Co effectively has spare capacity to meet these sales. Therefore, the minimum transfer price should be the marginal cost of producing these goods. Given that variable costs represent 40% of revenue, this means that the marginal cost for these sales is $884,000. This is therefore the minimum price which C Co should charge for these sales.In total, therefore, C Co will want to charge at least $6,224,000 for its sales to the Gearbox division.From the Gearbox division’s perspectiveThe Gearbox division will not want to pay more for the components than it could purchase them for externally. Given that it can purchase them all for 95% of the current price, this means a maximum purchase price of $7,172,500.OverallT aking into account all of the above, the transfer price for the sales should be somewhere between $6,224,000 and $7,172,500.4(a)Profit outcomesUnit contribution Sales price per unit$30$35Up to 100,000 units$18$23Above 100,000 units$19$24Sales price $30Sales Unit Total Fixed Advertising Profitvolume contribution contribution costs costs$$’000$’000$’000$’000 120,000192,280450900930110,000192,090450900740140,000192,6604509001,310Sales price $35Sales Unit Total Fixed Advertising Profitvolume contribution contribution costs costs$$’000$’000$’000$’000 108,000242,5924509701,172100,000232,30045097088094,000232,162450970742(b)Expected valuesSales price $30Sales Profit Probability EV ofvolume profit$’000$’000120,0009300·4372110,0007400·5370140,0001,3100·1131––––873––––Sales price $35Sales Profit Probability EV ofvolume profit$’000$’000108,0001,1720·3351·6100,0008800·326494,0007420·4296·8––––––912·4––––––If the criterion of expected value is used to make a decision as to which price to charge, then the price charged should be $35 per unit since the expected value of this option is the greatest.(c)Maximin decision ruleUnder this rule, the decision-maker selects the alternative which offers the most attractive worst outcome, i.e. the alternative which maximises the minimum profit. In the case of Gam Co, this would be the price of $35 as the lowest profit here is $742,000 as compared to a lowest profit of $740,000 at a price of $30.(d)Reasons for uncertainty arising in the budgeting processUncertainty arises largely because of changes in the external environment over which a company will sometimes have little control. Reasons include:–Customers may decide to buy more or less goods or services than originally forecast. For example, if a major customer goes into liquidation, this has a huge effect on a company and could also cause them to go into liquidation.–Competitors may strengthen or emerge and take some business away from a company. On the other hand, a competitor’s position may weaken leading to increased business for a particular company.–T echnological advances may take place which lead a company’s products or services to become out-dated and therefore less desirable.–The workforce may not perform as well as expected, perhaps because of time off due to illness or maybe simply because of lack of motivation.–Materials may increase in price because of global changes in commodity prices.–Inflation can cause the price of all inputs to increase or decrease.–If a company imports or exports goods or services, changes in exchange rates can cause prices to change.–Machines may fail to meet production schedules because of breakdown.–Social/political unrest could affect productivity, e.g. the workforce goes on strike.Note:This list is not exhaustive, nor would candidates be expected to make all the points raised in order to score full marks.5(a)Variances(i)The sales mix contribution varianceCalculated as (actual sales quantity – actual sales quantity in budgeted proportions) x standard contribution per unit.Standard contributions per valet:Full = $50 x 44·6% = $22·30 per valetMini = $30 x 55% = $16·50 per valetActual sales quantity in budgeted proportions (ASQBP):Full: 7,980 x (3,600/5,600) = 5,130Mini: 7,980 x (2,000/5,600) = 2,850Valet type AQAM AQBM Difference Standard Variancecontribution$$Full4,0005,130(1,130)22·3025,199AMini3,9802,8501,13016·5018,645F–––––––6,554A–––––––(ii)The sales quantity contribution varianceCalculated as (actual sales quantity in budgeted proportions – budgeted sales quantity) x standard contribution per unit.Valet type AQBM BQBM Difference Standard Variancecontribution$$Full5,1303,6001,53022·3034,119FMini2,8502,00085016·5014,025F–––––––48,144F–––––––(b)DescriptionThe sales mix contribution varianceThis variance measures the effect on profit of changing the mix of actual sales from the standard mix.The sales quantity contribution varianceThis variance measures the effect on profit of selling a different total quantity from the budgeted total quantity.(c)Sales performance of the businessThe sales performance of the business has been very good over the last year, as shown by the favourable sales quantity variance of $48,144. Overall, total sales revenue is 33% higher than budgeted (($319,400 –$240,000)/$240,000). This is because of a higher total number of valets being performed. When you look at where the difference in sales quantity actually is, you can see from the data provided in the question that it is the number of mini valets which is substantially higher. This number is 99% ((3,980 –2,000)/2,000) higher than budgeted, whereas the number of full valets is only 11% ((4,000 –3,600)/3,600) higher. Even 11% is still positive, however.The fact that the number of mini valets is so much higher combined with the fact that they generate a lower contribution per unit than the full valet led to an adverse sales mix variance of $6,554 in the year. This cannot be looked at in isolation as a sign of poor performance; it is simply reflective of the changes which have occurred in Strappia. We are told that disposable incomes in Strappia have decreased by 30% over the last year. This means that people have less money to spend on non-essential expenditure such as car valeting. Consequently, they are opting for the cheaper mini valet rather than the more expensive full valet. At the same time, we are also told that people are keeping their cars for an average of five years now as opposed to three years. This may be leading them to take more care of them and get them valeted regularly because they know that the car has to be kept for a longer period. Thus, the total quantity of valets is higher than budgeted, particularly the mini valets.Also, there is now one less competitor for Valet Co than there was a year ago, so Valet Co may have gained some of the old competitor’s business. T ogether, all of these factors would explain the higher number of total valets being performed and in particular, of the less expensive type of valet.Note:Other valid points will be given full credit.Fundamentals Level – Skills Module, Paper F5Performance Management June 2014 Marking SchemeMarks1(a)Full absorption costOverhead absorption rate1·5Cost for X incl labour and materials0·5Cost for Y incl labour and materials0·5Cost for Z incl labour and materials0·5–––3–––(b)Activity based costCorrect cost driver rates4·5Overhead unit cost for X1Overhead unit cost for Y1Overhead unit cost for Z1Adding labour and materials costs2T otal cost for X0·5T otal cost for Y0·5T otal cost for Z0·5–––11–––(c)DiscussionEffect on price3Effect on sales volume3–––6–––Total marks20––––––2(a)Optimum production planStating the objective function0·5Defining constraint for built time0·5Defining constraint for program time0·5Defining constraint for test time0·5Non-negativity constraints0·5Sales constraint x0·5Sales constraint y0·5Iso-contribution line worked out 1The graph:Labels 0·5Build time line0·5Program time line0·5T est time line0·5Demand for x line0·5Demand for y line0·5Iso-contribution line 0·5Feasible region identified and labelled/shaded 1Optimum point identified 1Equations solved at optimum point3T otal contribution0·5T otal profit0·5–––14–––(b)Slack valuesT est time calculation1·5Program time calculation1·5Defining and identifying slack resources1·5Discussing implication of slack resources1·5–––6–––Total marks20––––––Marks 3(a)RatiosCalculating ROCE1·5Calculating asset turnover1·5Calculating operating profit margin1·5Per valid comment1–––10–––(b)Transfer pricingEach valid comment/calculation 1 or 2–––10–––Total marks20––––––4(a)Profit outcomesUnit contribution up to 100,000 units1Unit contribution above 100,000 units1Each line of table for price of $30 (3 in total)1Each line of table for price of $35 (3 in total)1–––8–––(b)Expected valuesExpected value for $301Expected value for $351Recommendation1–––3–––(c)MaximinExplanation2Decision1–––3–––(d)UncertaintyEach point made1–––6–––Total marks20––––––5(a)CalculationsSales mix contribution variance4Sales quantity contribution variance4–––8–––(b)DescriptionOne mark per description2–––(c)Discussion on sales performanceCalculations –each one, max 20·5Maximum for each point made2–––10–––Total marks20––––––。
ACCA F5 2010年12月真题答案

Actual volume
750 650
Sales price Variance
$ 15,000 A
6,500 A ––––––– 21,500 A –––––––
Sales volume contribution variance = (actual sales volume – budgeted sales volume) x standard margin
Cost of sales Cost of sales has decreased by 19·2% in 2010. This must be considered in relation to the decrease in turnover as well. In 2009, cost of sales represented 72·3% of turnover and in 2010 this figure was 63·7%. This is quite a substantial decrease. The reasons for it can be ascertained by, firstly, looking at the freelance staff costs.
It can also be seen from the non-financial performance indicators that 20% of students in 2010 are students who have transferred over from alternative training providers. It is likely that they have transferred over because they have heard about the improved service that AT Co is providing. Hence, they are most likely the reason for the increased market share that AT Co has managed to secure in 2010.
ACCA 历年真题f5_2013_jun_q

Option 2 Expand the exercise studio. The capital cost of this would be $360,000.The expected effect on membership numbers for the next three years is as follows:
All contracts to customers of Squarize are for a minimum three-month period. The pay-tv box is sold to the customer at the beginning of the contract; however, the broadband and telephone equipment is only rented to them.
1. In the economy as a whole, discretionary spending had been severely hit by rising unemployment and inflation. In a bid to save cash, many pay-tv customers were cancelling their contracts after the minimum three-month period as they were then able to still keep the pay-tv box. The box comes with a number of free channels, which the customer can still continue to receive free of charge, even after the cancellation of their contract.
2015年6月ACCA考试F5mock答案

Section A1.relevant cost for materials:A:2000*12=24000(Purchase cost)B:2000*10=20000(replacement cost)C:1400*5+600*8=11800(scrap value+purchase cost)D:6000(opportunity cost2.D3.BTarget cost=18000*0.9=16200Attainable cost=16286Cost gap=864.D5.D ZBB is not suitable for manufacturing cost and can be applied to service costs6.A7.D8.D9.C each staff only works for40*(52-5)=1880hours10.B11.B12.D(120*3.5vs410)*4=40(F)13.A contribution/unit=30-(10+8+4+2)=6BEP(units)=64000/6=1066714.DEV with perfect information=15.C16.C17.ATime9th=total time for1-8units–total time for1-7units(using the learning effect formular directly)18.A Using average growth model F=O(1+g)^419.A20.AAns for Q19+20MIX VARIANCEProduct actual mix std mix variance(units)std rate variance($)PP129803284304A123648APP230402736304F72128F60206020QUANTITY VARIANCEProduct actual QTY Budgeted qty variance(units)std rate variance($)@std mix@std mixPP132843000284F123408FPP227362500236F71652FSECTION BQUESTION1(A)Machine hour required=4000*(6+4+8)=72000hoursMachine hour available=70000Machine hour in shortage=2000Therefore machine hour is the limiting factorCP1CP2CP3$$$Relevant cost of making407248Relevant cost of buying588068Cost saving/unit18820Machine hours/unit648Cost saving/machine hour32 2.5Ranking132Machine hours available700000CP1:4000*6=24000CP3:4000*8=32000CP2:3500*4=14000TOTAL:700000Therefore the company should buy another500units of CP2from external supplier.(B)Three other factors(reference point only.In final exams please write in sentences)●the loss of control over the whole production process●the quantity and the quality supplied by the external contractor●the price stability can be sustained or not.●Any other possible ways to increase the capacity of the production etc.QUESTION2(A)Payoff tables:size demand sales@20vc/unit goodwill depre net profitsmall 11013022008801201501050 11020022008801201501050medium 1701302600915.23101374.8 170200340013601203101610large 2401302600915.24201264.8 240200400014084202172(B)Maximax rule:Size demand profit Small1101301050 Medium1702001610 Large2402002172Therefore the company should buy large oneMaximin ruleSize demand profit Small1102001050 Medium1702001374.8 Large2402001264.8Therefore the company should buy medium Mini max-regretsummary(A)demand 130200size 11010501050 1701374.81610 2401264.82172regretdemand maxregret 130200size 110324.811221122 1700562562 2401100110Therefore the company should buy large oneQUESTION3(A)ABC VarianceExpenditure variance=1800*45vs84000=3000(A)Efficicency variance=(2100vs1800)*45=13500(F)Std cost driver rate=90000/2000=45/movement10500units of product should use(10500*2000)/10000=2100movements(b)Original std:0.5hr@$20/hrRevised std0.5hr*1.1@$20*0.95/hrActual std11000hrs@140800Labor rate variance-planning=18500*0.55*(20vs20*0.95)=10175F-operational=11000*0.95*20vs140800=68200FLabor efficiency var-planning=18500*(0.5vs0.55)*20=18500A-Operational=(18500*0.55vs11000)*20*0.95=15675AQUESTION4(refer to REFERENCE ANSWER FOR DEC/2011Q3) QUESTION5(a)cost pool cost driver cost($)number of driverscost driver rateproduction set-ups production runs105,000150700process testing#of tests300,0003,000100material handling cost #of materialmovements50,0001,00050ordering cost order numbers225,0002,000112.5(b)TOTAL production overheads for10,000units are:set-ups7000number of tests800number of material movements750number of order16875Total:25425Volume:10000Production overheads/unit 2.54General overheads:OAR=1.8mil/600000hrs=$3/hrTotal labor hours for10000units of products=10000/4=2500hoursGeneral o/h per unit=2500/10000*3=$0.75/unitTotal unit cost and selling price for productCost$/unitComponent cost 1.5Direct labor(15/60*8)2Production overheads 2.54General O/H0.75Total unit cost 6.79Mark-up(6.79*0.4) 2.72Selling price9.51。
历年6月ACCA考试F5真题答案

(c) Maximin and expected value decision rules The ‘maximin’ decision rule looks at the worst possible outcome at each supply level and then selects the highest one of these. It is used when the outcome cannot be assessed with any level of certainty. The decision maker therefore chooses the outcome which is guaranteed to minimise his losses. In the process, he loses out on the opportunity of making big profits. It is often seen as the pessimistic approach to decision-making (assuming that the worst outcome will occur) and is used by decision makers who are risk averse. It can be used for one-off or repeated decisions.The ‘expected value’ rule calculates the average return that will be made if a decision is repeated again and again. It does this by weighting each of the possible outcomes with their relative probability of occurring. It is the weighted arithmetic mean of the possible outcomes.Since the expected value shows the long run average outcome of a decision which is repeated time and time again, it is a useful decision rule for a risk neutral decision maker. This is because a risk neutral person neither seeks risk or avoids it; they are happy to accept an average outcome. The problem often is, however, that this rule is often used for decisions that only occur once. In this situation, the actual outcome is unlikely to be close to the long run average. For example, with Cement Co, the closest actual outcome to the expected value of $1,172,000 is the outcome of $1,085,000. This is not too far away from the expected value but many of the others are really different.。
2016年9月份ACCA考试科目F5真题练习及答案解析
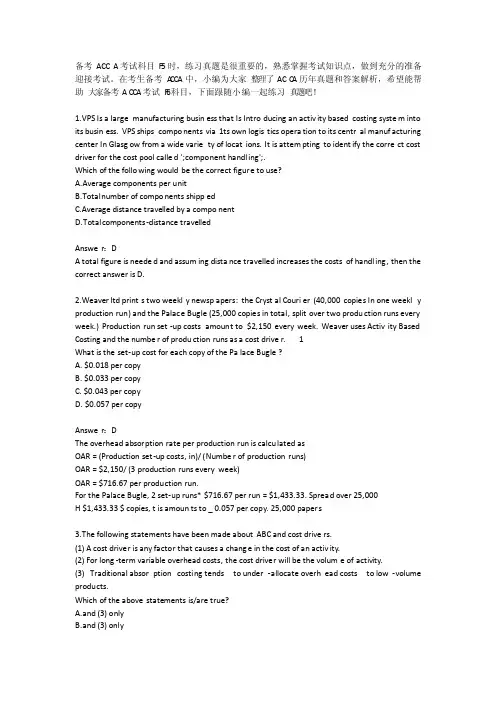
备考ACCA考试科目F5时,练习真题是很重要的,熟悉掌握考试知识点,做到充分的准备迎接考试。
在考生备考A CCA中,小编为大家整理了ACC A历年真题和答案解析,希望能帮助大家备考ACCA考试F6科目,下面跟随小编一起练习真题吧!1.VPS Is a largemanufa cturi ng busine ss that Is Introd ucing an activi ty basedcostin g system into its busine ss. VPS shipscompon entsvia 1ts own logist ics operat ion to its centra l manufa cturi ng center In Glasgo w from a wide variet y of locati ons. It is attemp tingto identi fy the correc t cost driver for the cost pool called ';compon ent handli ng';.Whichof the follow ing wouldbe the correc t figure to use?A.Averag e compon entsper unitB.Totalnumber of compon entsshippe dC.Averag e distan ce travel led by a compon entD.Totalcompon ents-distan ce travel ledAnswer:DA totalfigure is needed and assumi ng distan ce travel led increa ses the costsof handli ng, then the correc t answer is D.2.Weaver ltd prints two weekly newspa pers:the Crysta l Courie r (40,000 copies In one weekly produc tionrun) and the Palace Bugle(25,000 copies in total, splitover two produc tionruns everyweek.) Produc tionrun set-up costsamount to $2,150 everyweek. Weaver uses Activi ty BasedCostin g and the number of produc tionruns as a cost driver. 1What is the set-up cost for each copy of the Pa lace Bugle?A. $0.018 per copyB. $0.033 per copyC. $0.043 per copyD. $0.057 per copyAnswer:DThe overhe ad absorp tionrate per produc tionrun is calcul atedasOAR = (Produc tionset-up costs, in)/ (Number of produc tionruns)OAR = $2,150/ (3 produc tionruns everyweek)OAR = $716.67 per produc tionrun.For the Palace Bugle, 2 set-up runs* $716.67 per run = $1,433.33. Spread over 25,000H $1,433.33 $ copies, t is amount s to _ 0.057 per copy. 25,000 papers3.The follow ing statem entshave been made aboutABC and cost driver s.(1) A cost driver is any factor that causes a change in the cost of an activi ty.(2) For long-term variab le overhe ad costs, the cost driver will be the volume of activi ty.(3) Tradit ional absorp tioncostin g tendsto under-alloca te overhe ad coststo low-volume produc ts.Whichof the abovestatem entsis/are true?A.and (3) onlyB.and (3) onlyC.and (2) onlyD.(1), (2) and (3)Answer:DStatem ent (1) provid es a defini tionof a cost driver. Cost driver s for long-term variab le overhe ad costswill be the volume of a partic ularactivi ty to whichthe cost driver relate s, so Statem ent (2) is correc t. Statem ent (3) is also correc t. In tradit ional absorp tioncostin g, standa rd high -volume produc ts receiv e a higher amount of overhe ad coststhan with ABC. ABC allows for the unusua lly high costsof suppor t activi tiesfor low-volume produc ts (such as relati velyhigher set-up costs, orderproces singcostsand so on).结合老师的辅导和真题的练习,相信大家一定能取得优异的ACCA考试成绩。
2015年6月ACCA F5考试真题答案
A 38·80 104·64
9·28 144·00 ––––––––– 296·72 –––––––––
1,200 800
––––––––– 2,296·72 –––––––––
B 58·20 209·28 37·12 288·00 ––––––––– 592·60 –––––––––
2,640 1,620 ––––––––– 4,852·60 –––––––––
A 14,600 14,600 350,400 14,600
B 22,400 33,600 1,075,200 89,600
Total 37,000 48,200 1,425,600 104,200
Cost driver rates
Administrative costs – $1,870,160/48,200 = $38·80 per admin hour
Overhead allocation per procedure Procedure
Administrative costs Nursing costs Catering costs General facility costs
Add direct costs: Surgical Anaesthesia Total cost per procedure
Answers
Fundamentals Level – Skills Module, Paper F5 Performance Management
Section A
1C
Divisional profit before depreciation = $2·7m x 15% = $405,000 per annum. Less depreciation = $2·7m x 1/50 = $54,000 per annum. Divisional profit after depreciation = $351,000 Imputed interest = $2·7m x 7% = $189,000 Residual income = $162,000.
ACCA_F5_201212_Ans
高C A a c c a .g n .c nFundamentals Level – Skills Module, Paper F5Performance Management December 2012 Answers1Hair Co (a)Weighted average contribution to sales ratio (WA C/S ratio) = total contribution/total sales revenue. Per unit:C SD $$$Selling price 110160120Material 1(12)(28)(16)Material 2(8)(22)(26)Skilled labour (16)(34)(22)Unskilled labour (14)(20)(28)–––––––––Contribution 605628–––––––––Sales units20,00022,00026,000T otal sales revenue$2,200,000$3,520,000$3,120,000T otal contribution$1,200,000$1,232,000$728,000WA C/S ratio = $1,200,000 + $1,232,000 + $728,000/$2,200,000 + $3,520,000 + $3,120,000= $3,160,000/$8,840,000 = 35·75%(b)Break-even sales revenue = fixed costs/C/S ratio Therefore break-even sales revenue = $640,000/35·75% = $1,790,209·70.(c)PV chart Calculate the individual C/S ratio for each product then rank them according to the highest one first.Per unit:C SD $$$Contribution 605628Selling price 110160120C/S ratio 0·550·350·23Ranking 123ProductRevenueCumulative Revenue Profit Cumulative Profit (x axis co-ordinate)(y axis co-ordinate)$$$$(640,000)(640,000)Make C 2,200,0002,200,0001,200,000560,000Make S 3,520,0005,720,0001,232,0001,792,000Make D3,120,0008,840,000728,0002,520,000高顿财经A C C A a c c a .g a o d u n .c n(d)From the chart above it can be seen that, if the products are sold in order of the highest ranking first, break even will take place at a point just under $1,200,000 of sales revenue. The exact figure can be worked out by taking the fixed costs of $640,000 and dividing them by Product C’s C/S ratio of 0·55, i.e. the exact BEP is $1,163,636. This is substantially earlier than the break-even point which occurs if the products are all sold in a constant mix, which is $1,790,209, as calculated in (b) above.The reason for this is obviously because the more profitable product, C, contributes more per unit to fixed costs when being sold on its own, than when a mix of products C, S and D are sold. The weighted average C/S ratio of all three products is only 35·75%, compared to C’s C/S ratio of 55%. Obviously, then, break even will occur earlier if C is sold in priority.In reality, however, the mix of sales will vary throughout the year and Hair Co can neither assume that the products are sold in a constant mix, nor that the most profitable can be sold first.2Truffle Co (a)Basic variancesStandard cost of labour per hour = $6/0·5 = $12 per hour.Labour rate variance = (actual hours paid x actual rate) – (actual hours paid x std rate)Actual hours paid x std rate = $136,800/·95 = $144,000. Therefore rate variance = $144,000 –$136,800 = $7,200 FLabour efficiency variance =(actual production in std hours – actual hours worked) x std rate[(20,500 x 0·5) – 12,000] x $12 = $21,000 A.(b)Planning and operational variancesLabour rate planning variance(Revised rate –std rate) x actual hours paid = [$12 – ($12 x 0·95)] x 12,000 = $7,200 F .Labour rate operational varianceThere is no labour rate operational variance.(Revised rate – actual rate) x actual hours paid = $11·40 –$11·40 x 12,000 = 0Most p r ofitable fi r st Co n sta n t m ix2,0004,0006,0008,00010,000–1,000–50005001,0001,5002,0002,5003,000Sales revenue $’000P r o f i t $’000CSD高顿财经A C C A a c c a .g a o d u n .c nLabour efficiency planning variance(Standard hours for actual production –revised hours for actual production) x std rate [10,250 –(20,500 x 0·5 x 1·2)] x $12 = $24,600 A.Labour efficiency operational variance(Revised hours for actual production – actual hours for actual production) x std rate (12,300 – 12,000) x $12 = $3,600 F .(c)DiscussionWhen looking at the total variances alone, it looks like the production manager has been extremely poor at controlling his staff’s efficiency, since the labour efficiency variance is $21,000 adverse. It also looks, at a glance, like he has managed to secure labour at a lower rate.In order to assess the production manager’s performance fairly, however, only the operational variances should be taken into account. This is because planning variances reflect differences that arise because of factors that are outside the control of the production manager. The operational variance for the labour rate was $0, which means that the labour force were paid exactly what was agreed at the end of October: their reduced rate of $11·40 per hour. The manager clearly did not have to pay anyone for overtime, for example, which would have been expected to push this rate up. The rate reduction was secured by the company and was not within the control of the production manager, so he cannot take credit for the favourable rate planning variance of $7,200. The company is the source of this improvement.As regards labour efficiency, the planning and operational variances give us more information about the total efficiency variance of $21,000A. When this is broken down into its two parts, it becomes clear that the operational variance, for which the manager does have control, is actually $3,600 favourable. This is because, when the recipe is changed as it has been in November, the chocolates usually take 20% longer to make in the first month whilst the workers are getting used to handling the new ingredient mix. When this is taken into account, it can therefore be seen that workers took less than the 20% extra time that they were expected to take, hence the positive operational variance. The planning variance, on the other hand, is $24,600 adverse. This is because the standard labour time per batch was not updated in November to reflect the fact that it would take longer to produce the truffles. The manager cannot be held responsible for this.Overall, then, the manager has performed well, given the change in the recipe.3Web CoWeb Co has made three changes and introduced two incentives in an attempt to increase sales. Using the performance indicators given in the question, it is possible to assess whether these attempts have been successful.Total sales revenueThis has increased from $2·2 million to $2·75m, an increase of 25% (W1). This is a substantial increase, especially considering the fact that a $10 discount has been given to all customers spending $100 or more at any one time. However, because a number of changes and incentives have been introduced, it is not possible to assess how effective each of the individual changes/incentives has been in increasing sales revenue without considering the other performance indicators.Net profit margin (NPM)This has decreased from 25% to 16·7%. In $ terms this means that net profit was $550,000 in quarter 1 and $459,250 in quarter 2 (W2). If the 25% NPM had been maintained in quarter 2, the net profit would have been $687,500 for quarter 2. It is therefore $228,250 lower than it would have been. This is mainly because of the $200,000 paid out for advertising and the $20,000 paid to the consultant for the search engine work. The remaining $8,250 difference could be a result of the cost of the $10 discounts given to customers who spent more than $100, depending on how these are accounted for. Alternatively, it could be due to the costs of providing the Fast T rack service. More information would be required on how the discounts are accounted for (whether they are netted off sales revenue or instead included in cost of sales) and also on the cost of providing the Fast T rack service.Whilst it is not clear how long the advert is going to run for in the fashion magazine, $200,000 does seem to be a very large cost.This expense is largely responsible for the fall in NPM. This is discussed further under ‘number of visits to website’.Number of visits to websiteThese have increased dramatically from 101,589 to 141,714, an increase of 40,125 visits (39·5% W3). The reason for this is a combination of visitors coming through the fashion magazine’s website (28,201 visitors W5), with the remainder of the increase most probably being due to the search engine consultants’ work. Both of these changes can therefore be said to have been effective in improving the number of people who at least visit Web Co’s online store. However, given that the search engine consultant only charged a fee of $20,000 compared to the $200,000 paid for magazine advertising, in relative terms, the consultant’s work provided value for money. Web Co’s sales are not really high enough to withstand a hit of $200,000 against profit, hence the fall in NPM.Number of orders/customers spending more than $100The number of orders received from customers has increased from 40,636 to 49,600, an increase of 22% (W4). This shows that,whilst most of the 25% sales revenue increase is due to a higher number of orders, 3% of it is due to orders being of a higher purchase value. This is also reflected in the fact that the number of customers spending more than $100 per visit has increased高顿财经A C C A a c c a .g a o d u n .c nfrom 4,650 to 6,390, an increase of 1,740 orders. So, for example, If each of these 1,740 customers spent exactly $100 rather than the $50 they might normally spend, it would easily explain the 3% increase in sales that is not due to increased order numbers. It depends partly on how the sales discounts of $10 each are accounted for. As stated above, further information is required on these.An increase in the number of orders would also be expected, given that the number of visitors to the site has increased substantially.This leads on to the next point.Conversion rate – visitor to purchaserThe conversion rate of visitors to purchasers has gone down from 40% to 35%. This is not surprising, given the advertising on the fashion magazine’s website. Readers of the magazine may well have clicked on the link out of curiosity and may come back and purchase something at a later date. It may be useful to have a breakdown of the visitor to purchaser rate, showing one statistic for visitors who have come from the online magazine and one for those who have not. This would help clarify the position.Website availabilityRather than improving after the work completed by Web Co’s IT department, the website’s availability has stayed the same. This means that the IT department’s changes to the website have not corrected the problem. Lack of availability is not good for business,although its exact impact is difficult to ascertain. It may be that visitors have been part of the way through making a purchase only to find that the website then becomes unavailable. More information would need to be available about aborted purchases, for example, before any further conclusions could be drawn.Subscribers to online newsletterThese have increased by a massive 159%. It is not clear what impact this has had on the business as we do not know whether the level of repeat customers has increased. This information is needed. Surprisingly, it seems that there has not been an increased cost associated with providing Fast T rack delivery, as the whole fall in net profit has been accounted for, so one can only assume that Web Co managed to offer this service without incurring any additional cost itself.ConclusionWith the exception of the work carried out to make the system more available, all of the other measures seem to have increased sales or, in the case of Incentive 1, increased subscribers. More information is needed in relation to a couple of areas, as noted above. The business has therefore been responsive to changes made and incentives implemented but the cost of the advertising was so high that, overall, profits have declined substantially. This expenditure seems too high in relation to the corresponding increase in sales volumes.Workings1.Increase in sales revenue $2·75m –$2·2m/$2·2m = 25% increase.2. NPM: 25% x $2·2m = $550,000 profit in quarter 1. 16·7% x $2·75m = $459,250 profit in quarter 2.3.No. of visits to website: increase = 141,714 –101,589/101,589 = 39·5%.4.Increase in orders = 49,600 –40,636/40,636 = 22%.5.Customers accessing website through magazine line = 141,714 x 19·9% = 28,201.6.Increase in subscribers to newsletter = 11,900 –4,600/4,600 = 159%.4Designit (a)ExplanationThe rolling budget outlined for Designit would be a budget covering a 12-month period and would be updated monthly.However, instead of the 12-month period remaining static, it would always roll forward by one month. This means that, as soon as one month has elapsed, a budget is prepared for the corresponding month one year later. For example, Designit would begin by preparing a budget for the 12 months from 1 December 2012 to 30 November 2013, to correspond with its year end. Then, at the end of December 2012, a budget would be prepared for the month December 2013, so that the unexpired period covered by the budget is always 12 months.When the budget is initially prepared for the year ending 30 November 2013, the first month is prepared in detail, with much less detail being given to later months, where there is a greater uncertainty about the future. Then, when this first month has elapsed and the budget for the month of December 2013 is prepared, it is also necessary to revisit and revise the budget for January 2013, which will now be done in more detail.Note:This answer gives more level of detail than would be required to gain full marks.(b)ProblemsDesignit only has one part-qualified accountant. H e is already overworked and probably has neither the time nor the experience to prepare rolling budgets every month. One would only expect to see monthly rolling budgets of this nature in businesses which face rapid change. There is no evidence that this is the case for Designit. If it did decide to introduce rolling budgets, it would probably be sufficient if they were updated on a quarterly rather than a monthly basis. If this monthly rolling budget is going to be introduced, it is going to require a lot of input from many of the staff, meaning that they will have less time to dedicate to other things.The sales managers may react badly to the new budgeting and incentive system. They are used to having been set targets that are easily achievable. With the new system, they will have to work hard all year round. They are also likely to become frustrated with the fact that they do not know the target for the whole year in advance. Once they have hit their target for the高顿财经A C C A a c c a .g a o d u n .c nmonth, they may then also be tempted to hold back further work and let it run into the next month, so that they increase the chances of meeting next month’s target. This would not be good for the business.(c)Alternative incentive schemeThe issue with the current bonus scheme is that the reward system is stepped, rather than being a percentage of sales. The first $1·5 million fee income target is too easy to reach and the second $1·5 million target is too hard to reach. Therefore,managers are not motivated to earn additional fees once the initial $1·5 million target has been reached.A series of constantly rising bonus rates ranging over a narrower rate of sales could be used. For example, every $500,000of fee income could be rewarded with an additional bonus equivalent to 5% of salary. Alternatively, the bonus could be replaced by commission, giving the managers a reward as a percentage of the fee income rather than a percentage of salary.Currently, the company is paying out $30,000 in bonus to each of its managers each year. This is 2% of $1·5 million.Therefore, the bonus could be that each manager earns 2% commission on all sales.(d)Using spreadsheetsIf spreadsheets are used for budgeting, the part-qualified accountant could be rekeying large amounts of data taken from the company’s systems. It would be very easy for him to make a mistake when he is entering his data, especially without someone else to check his work.Similarly, if there is any error in any of the formulae, all the numbers in the budget will be wrong. Whilst this risk already exists because fixed budgets are being prepared on spreadsheets, the rolling budgets will be far more complex, which increases the risk of error in the design of the model or any of the formulae.A model can become easily corrupted simply by putting a number in the wrong cell. The accountant is unlikely to spot this due to his lack of experience and the time pressure on him.When spreadsheets are used, there is no audit trail that can be followed in order to check the numbers.5Wash Co (a)Transfer price using machine hoursT otal overhead costs = $877,620T otal machine hours = (3,200 x 2) + (5,450) x 1 = 11,850Overhead absorption rate = $877,620/11,850 = $74·06Overhead cost for S = 2 x $74·06 = $148·12 and for R = 1 x $74·06 = $74·06.Product SProduct R$$Materials cost11795Labour cost (at $12 per hour)69Overhead costs 148·1274·06––––––––––––T otal cost271·12178·0610% mark-up27·11 17·81 ––––––––––––T ransfer price using machine hours 298·23195·87––––––––––––(b)Transfer price using ABC Machine set up costs:driver = number of production runs.30 + 12 = 42.Therefore cost per set up = $306,435/42 = $7,296·07Machine maintenance costs:driver = machine hours: 11,850 (S= 6,400; R=5,450)$415,105/11,850 = $35·03Ordering costs:driver = number of purchase orders 82 + 64 = 146.Therefore cost per order = $11,680/146 = $80Delivery costs:driver = number of deliveries.64 + 80 = 144.Therefore cost per delivery = $144,400/144 = $1,002·78高顿财经A C C A a c c a .g a o d u n .c nAllocation of overheads to each product:Product SProduct RTotal $$$Machine set-up costs218,88287,553306,435Machine maintenance costs 224,192190,913415,106Ordering costs 6,5605,12011,680Delivery costs64,178 80,222144,400––––––––––––––––––––––––T otal overheads allocated 513,812363,808877,620––––––––––––––––––––––––Number of units produced 3,2005,4508,650$$Overhead cost per unit 160·5766·75T ransfer price per unit:Materials cost 11795Labour cost 69Overhead costs 160·5766·75––––––––––––––T otal cost283·57170·75Add 10% mark up28·3617·08––––––––––––––T ransfer price under ABC311·93187·83––––––––––––––(c)(i)ABC monthly profitUsing ABC transfer price from part (b):Assembly division Product S Product R Total Production and sales 3,2005,450$$10% mark up 28·3617·08––––––––––––––––––––Profit90,75293,086183,838––––––––––––––––––––––––––––Retail divisionProduct S Product R TotalProduction and sales 3,2005,450$$Selling price 320260Cost price (311·93)(187·83)–––––––––––––––––––––Profit per unit 8·0772·17–––––––––––––––––––––T otal profit25,824393,327419,151–––––––––––––––––––––––––––––(ii)Discussion From the various profit figures for the three bases of allocating overheads, various observations can be made.–There is obviously very little difference between the TOTAL profits of each division whichever method is used,except for differences arising from rounding. In each case, the total profit made by the assembly division is approximately $183,000 and $419,000 for the retail division. It is the reallocation of profits from R to S or S to R that is the important factor in this situation, given that the retail division wants to reduce prices but increase sales volumes for R.–As regards the assembly division, when labour hours are used to allocate overheads, there is a big difference between the profits that each of the two products makes. When machine hours or ABC are used, this difference becomes much smaller.–As regards the retail division, when labour hours are used, product S generates 76% of the profit. When this method of allocation is then changed so that either machine hours are used or ABC is used, the main share of the profit then moves to product R. In the case of ABC, the profit moves so much to R that S only generates a profit per unit of $8·07 for the retail division, which is very low for a selling price of $320.–From the assembly division manager’s point of view, any change that results in increased sales of either R or S to the retail division would be a good thing for the assembly division, given that both products are profitable. However,the assembly division’s manager would probably oppose the implementation of ABC to achieve this end result because firstly, it is complex and secondly, it is unnecessary here. The aim of this exercise is to set more accurate transfer prices for R and S, which should mean a reduction in R’s transfer price and an increase in S’s, according to the information given. This would then have the effect of enabling the retail division to lower its price for R and increase sales volumes. This goal is achieved simply by changing the basis of overhead absorption from labour hours to machine hours, without the need for activity based costing.高顿财经A C C A a c c a .g a o d u n .c n–The retail manager’s view is likely to be exactly the same. If the basis of absorption is changed so that a lower transfer price is charged, the retail division could potentially reduce their selling price for R, provided that the increased sales volumes more than make up for the reduced margin. There is no need to get into the complexities of ABC when the results it produces are not that different.高顿财经A C C A a c c a .g a o d u n .c nFundamentals Level – Skills Module, Paper F5Performance ManagementDecember 2012Marks1Hair Co (a)Weighted average C/S ratio Individual contributions 3T otal sales revenue 1T otal contribution 1Ratio1–––6–––(b)Break-even revenue 2–––(c)PV chartIndividual CS ratios 1·5Ranking1Workings for chart 2Chart:Labelling0·5Plotting each of six points 4–––9–––(d)DiscussionGeneral comments re assumptions of CVP (max. 2 marks)1Each valid point re BEP 1–––3–––Total20––––––2Truffle Co (a)Rate and efficiency variances Rate variance2Efficiency variance 2–––4–––(b)Planning and operational variances Labour rate planning variance 2Labour rate operational variance 2Labour efficiency planning variance 2Labour efficiency operational variance 2–––8–––(c)DiscussionOnly operational variances controllable 1No labour rate operating variance1Planning variance down to company, not manager 2Labour efficiency total variance looks bad2Manager has performed well as regards efficiency 2Standard for labour time was to blame 2Conclusion 2–––Maximum marks 8–––Total20––––––高顿财经A C C A a c c a .g a o d u n .c nMarks3Web CoCalculations 4Missing info3Discussion and further analysis (2–3 marks per point)18Conclusion 2–––Total20––––––4Designit (a)ExplanationUpdated after one month elapsed 1Always 12 months 1Example given1First month in detail 1Later month less detail1Need to revisit earlier months 1–––Maximum4–––(b)Problems More time1Lack of experience 1T oo regular2Managers’ resistance 2Work harder1Holding back work 2–––Maximum 6–––(c)Simpler incentive scheme Current target too easy 1Second target too hard1Other valid point re current scheme 1New scheme outlined 3–––6–––(d)Using spreadsheets Errors entering data1Rolling budgets more complex 1Formulae may be wrong 1Corruption of model 1No audit trail 1–––Maximum 4–––Total20––––––高顿财经A C C A a c c a .g a o d u n .c nMarks5Wash Co (a)T ransfer price using machine hours Calculating OAR 1New TP for S 1New TP for R1–––3–––(b)T ransfer price using ABC Identify cost drivers 1Cost driver rates2T otal overheads allocated 2Overhead cost per unit 1T otal cost per unit 1T ransfer price per unit1–––8–––(c)ABC profit and discussion (i)Profit calculation 3–––(ii)Each valid comment 2–––Maximum marks 6–––Total20––––––21高顿财经A C C A a c c a .g a o d u n .c n。
ACCA F5考试真题答案
AnswersFundamentals Level – Skills Module, Paper F5 Performance ManagementSection A 1ADivision A: Profit = $14·4m x 30% = $4·32m Imputed interest charge = $32·6m x 10% = $3·26m Residual income = $1·06m Division B: Profit = 8·8m x 24% = $2·112m Imputed interest charge = $22·2m x 10% = $2·22m Residual income = $(0·108)m 2345DAll costs are included when using life cycle costing. AThis is the definition of a basic standard. BThe first statement is describing management control, not strategic planning. CNumber of units required to make target profit = fixed costs + target profit/contribution per unit of P1. Fixed costs = ($1·2 x 10,000) + ($1 x 12,500) – $2,500 = $22,000. Contribution per unit of P = $3·20 + $1·20 = $4·40. ($22,000 + $60,000)/$4·40 = 18,636 units. 6AProductA BC D Selling price per unit Raw material costDirect labour cost at $11 per hour Variable overhead cost Contribution per unit$160 $24 $66 $24 $214 $56 $88 $18 $100 $22 $33 $24 $140 $40 $22 $18 $46 $52 $21 $60 –––––––– –––– –––– Direct labour hours per unit Contribution per labour hour Rank 6 $7·67 2 8 $6·504 3 $7 2 $30 1 3 Normal monthly hours (total units x hours per unit) 1,8001,000720800If the strike goes ahead, only 2,160 labour hours will be available.Therefore make all of D, then 1,360 hours’ worth of A (2,160 – 800 hrs). 78B460 – 400 = 60 clients$40,000 – $36,880 = $3,120 VC per unit = $3,120/60 = $52Therefore FC = $40,000 – (460 x $52) = $16,080 BIncrease in variable costs from buying in (2,200 units x $40 ($140 – $100)) = $88,000 Less the specific fixed costs saved if A is shut down = ($10,000) Decrease in profit = $78,000Only the first statement is correct. Traditional absorption costing tends to over-allocate costs to high volume productsunder-allocate them. 10 11BBy definition, a shadow price is the amount by which contribution will increase if an extra kg of material becomes available. 20 x $2·80 = $56. CNeither statement is correct. Responsibility is not assigned solely to senior managers as, for example, in a TQM environment quality is everybody’s responsibility. In addition, standard costing can be difficult to apply in dynamic situations. 12 13AThe second statement is talking about flow cost accounting, not input/output analysis. DTarget 1 is a financial target and so assesses economy factors. Target 2 is measuring the rate of work handled by staff which is efficiency measure. Target 3 is assessing output, so is a measure of effectiveness. 14 15BIn comparison to participative budgeting, an advantage of non-participative budgeting is that it should be less time consuming, as less collaboration will be required in order to produce the budgets. CThe target costing process always begins with the target selling price being set. The required profit is then determined and deducted from the target selling price to estimate the target cost. The target cost is then compared to the estimated current cost and the co gap is then calculated. 16 17AThis is a description of an incremental budget. ANew profit figures before salary paid: Good manager: $180,000 x 1·3 = $234,000 Average manager: $180,000 x 1·2 = $216,000 Poor: $180,000 x 1·1 = $198,000EV of profits = (0·35 x $234,000) + (0·45 x $216,000) + (0·2 x $198,000) = $81,900 + $97,200 + $39,600 = $218,7Deduct salary cost and EV with manager = $178,700Therefore do not employ manager as profits will fall by $1,300. 18 BSet-up costs per production run = $140,000/28 = $5,000 Cost per inspection = $80,000/8 = $10,000Other overhead costs per labour hour = $96,000/48,000 = $2 Overheads costs of product D: $ Set-up costs (15 x $5,000) Inspection costs (3 x $10,000) Other overheads (40,000 x $2)75,000 30,000 80,00020 This is an example of feedforward control as the manager is using a forecast to assist in making a future decision.AIf demand is inelastic or the product life cycle is short, a price skimming approach would be more appropriate.1 Chair Co(a)Learning curve formula = y = ax b Cumulative average time per unit for 8 units: Y = 12 x 8–·415 = 5·0628948 hours.Therefore cumulative total time for 8 units = 40·503158 hours. Cumulative average time per unit for 7 units: Y = 12 x 7–·415 = 5·3513771 hours.Therefore cumulative total time for 7 units = 37·45964 hours.Therefore incremental time for 8th unit = 40·503158 hours – 37·45964 hours = 3·043518 hours. Total labour cost for 8th unit =3·043518 x $15 = $45·65277 Material and overheads cost per unit = $230 Therefore total cost per unit = $275·65277 Therefore price per unit = $413·47915 (b) (i) Actual learning rateCumulative number ofseats produced 1 2 4 8Cumulative totalCumulative averagehours per unit 12·5 12·5 x r 12·5 x r 2 hours 12·5 ? ? 34·312·5 x r 3Using algebra: 34·3 = 8 x (12·5 x r 3)4·2875 = (12·5 x r 3) 0·343 = r 3 r = 0·70The learning effect was 70% as compared to the forecast rate of 75%, meaning that the labour force learnt more quicklythan anticipated. (ii) Adjusted priceThe adjusted price charged will be lower than the original price calculated in part (a). This is because the incrementa cost of the 8th unit will be lower given the 70% learning rate, even though the first unit took 12·5 hours. We know this because we are told that the cumulative time for 8 units was actually 34·3 hours. This is lower than the estima cumulative time in part (a) for 8 units of 40·503158 hours and therefore, logically, the actual incremental time for the 8th unit must be lower than the estimated 3·043518 hours calculated in part (a). Consequently, total cost will be lower and price will be lower, given that this is based on cost.2Glam CoBottleneck activity (a)The bottleneck may have been worked out as follows:Total salon hours = 8 x 6 x 50 = 2,400 each year. The capacity for each senior stylist must be 2,400 hours, which equate to 2,400 cuts each year (2,400/1). Since there are three senior stylists, the total capacity is 7,200 hours or 7,200 cuts e year. Using this method, the capacity for each activity is as follows: Cut Treatment 16,000 4,800 Assistants Senior stylists Junior stylists48,000 7,200 9,6009,600The bottleneck activity is clearly the work performed by the senior stylists.The senior stylists’ time is called a bottleneck activity because it is the activity which prevents the salon’s throughpu t fro being higher than it is. The total number of cuts or treatments which can be completed by the salon’s senior stylists is than the number which can be completed by other staff members, considering the number of each type of staff available and the time required by each type of staff for each client.(b) TPARCut$Treatment$ Selling price 60 110Materials Throughput Throughput per bottleneck hour Total salon costs per BN hour (w1) TPAR 0·60 59·40 59·40 42·56 1·48 (7·40+0·6) 102 68 42·56 1·6Working 1: Total salon costs(3 x $40,000) + (2 x $28,000) + (2 x $12,000) + $106,400 = $306,400 Therefore cost for each bottleneck hour = $306,400/7,200 = $42·56Note: Answers based on total salary costs were $80,000 were also equally acceptable since the wording of question was open to interpretation.3Hi Life Co Direct materials: Fabric WoodNote 1 2 $ 200 m 2 at $17·50 per m 2 20 m at $8·20 per m 30 m at $8·50 per m 3,500 164 255 2 Direct labour: SkilledSemi-skilledFactory overheadsAdministration overheads 50 hours at $24 per hour 300 hours at $14 per hour 20 hours at $15 per hour3 4 5 61,200 4,200 300 ––––––– Total cost 9,619 ––––––1 2 Since the material is in regular use by HL Co, it is replacement cost which is the relevant cost for the contract.30 m will have to be ordered from the alternative supplier for immediate delivery but the remaining 20 m can be used from inventory and replaced by an order from the usual supplier at a cost of $8·20 per m.3 4 5There is no cost for the first 150 hours of labour because there is spare capacity. The remaining 50 hours will be paid at tim and a half, which is $16 x 1·5, i.e. $24 per hour.HL Co will choose to use the agency workers, who will cost $14 per hour, since this is cheaper than paying existingsemi-skilled workers at $18 per hour ($12 x 1·5) to work overtime.None of the general factory costs are incremental, so they have all been excluded. However, the supervisor’s overtime pay is incremental, so has been included. The supervisor’s normal salary, on the other hand, has been excluded because it is no incremental.6 These are general overheads and are not incremental, so no value should be included for them.4Jamair(a) The four perspectivesFinancial perspective – this perspective is concerned with how a company looks to its shareholders. How can it create valuefor them? Kaplan and Norton identified three core financial themes which will drive the business strategy: revenue growth and mix, cost reduction and asset utilisation.Customer perspective – this considers how the organisation appears to customers. The organisation should ask itself: achieve our vision, how should we appear to our customers?’ The customer perspective should identify the customer a market segments in which the business will compete. There is a strong link between the customer perspective and revenue objectives in the financial perspective. If customer objectives are achieved, revenue objectives should be too.Internal perspective – this requires the organisation to ask itself: ‘what must we excel at to achieve our financial and customer objectives?’ It must identify the internal business processes which are critical to the implementation of the organisation strategy. These will include the innovation process, the operations process and the post-sales process.Learning and growth perspective – this requires the organisation to ask itself whether it can continue to improve and create value. The organisation must continue to invest in its infrastructure – i.e. people, systems and organisational procedures – in order to improve the capabilities which will help the other three perspectives to be achieved.(b) Goals and measuresFinancial perspectiveGoal Performance measureTo use fewer planes to transport customers Lease costs of plane per customerExplanation – operating efficiency will be driven by getting more customers on fewer planes. This goal and measure cover the cost side of this.Goal Performance measureTo increase seat revenue per plane Revenue per available passenger mileExplanation – this covers the first part of achieving operating efficiency – by having fewer empty seats on planes.Customer perspectiveGoal Performance measureTo ensure that flights are on time ‘On time arrival’ ranking from the aviation authorityExplanation – Jamair is currently number 7 in the rankings. If it becomes known as a particularly reliable airline, customers are more likely to use it, which will ultimately increase revenue.Goal Performance measureTo reduce the number of flights cancelled The number of flights cancelledExplanation – again, if flights are seen to be cancelled frequently by Jamair, customers will not want to use it. It needs to b perceived as reliable by its customers.Internal perspectiveGoal Performance measureTo improve turnaround time on the ground ‘On the ground’ timeExplanation – less time spent on the ground means fewer planes are needed, which will reduce plane leasing costs. However, it is important not to compromise the quality of cleaning or make errors in refuelling as a consequence of reducing on ground time.Goal Performance measureTo improve the cleanliness of Jamair’s planes The percentage of customers happy with the standard of the planes,as reported in the customer satisfaction surveys.Explanation –at present, only 85% of customers are happy with the standard of cleanliness on Jamair’s planes. This could be causing loss of revenue.Goal Performance measureTo develop the online booking system Percentage downtime.Explanation – since the company relies entirely on the booking system for customer booking of flights and check-in, critical that it can deal with the growing number of customers.Learning perspectiveGoal Performance measureTo reduce the employee absentee rate The number of days absent per employeeExplanation – it is critical to Jamair that its workforce is reliable as, at worse, absent staff lead to cancelled flights.Goal Performance measureTo increase ground crew training on cleaning andNumber of days’ training per ground crew member refuelling proceduresExplanation – if ground crew are better trained, they can reduce the number of minutes that the plane stays on the groun which will result in fewer planes being required and therefore lower costs. Also, if their cleaning is better, customer satisfaction and retention will increase.Note: Only one goal and measure were required for each perspective. In order to gain full marks, answers had to be specific to Jamair as stated in the requirements.5 Safe Soap Co(a) Variance calculationsMix varianceTotal kg of materials per standard batch = 0·25 + 0·6 + 0·5 = 1·35 kgTherefore standard quantity to produce 136,000 batches = 136,000 x 1·35 kg = 183,600 kgActual total kg of materials used to produce 136,000 batches = 34,080 + 83,232 + 64,200 = 181,512 kgMaterial Actual quantityStandard mixkgs181,512 x 0·25/1·35 = 33,613·33181,512 x 0·6/1·35 = Actual quantityActual mixkgs34,08083,232Variance Standard costper kgVariancekgs(466·67)(2,560)$104$(4,666·70)(10,240)Lye Coconut oil Shea butter80,672181,512 x 0·5/1·35 = 67,226·67 64,200 3,026·67 3 9,080·01––––––––––––––––––––––––––181,512 181,512 (5,826·69)A––––––––––––––––––––––––––Yield varianceMaterial Standard quantityStandard mix Actual quantityStandard mixkgs33,613·3380,672Variance Standard costper kgVariancekgs386·67928$104$3,866·703,712Lye Coconut oil Shea butter 0·25 x 136,000 =0·6 x 136,000 =0·5 x 136,000 =34,00081,60068,000 67,226·67 773·33 3 2,319·99––––––––183,600––––––––––––––––––181,512 9,898·69F––––––––––––––––––––––––––(b) (i) A materials mix variance will occur when the actual mix of materials used in production is different from the standardmix. So, it is inputs which are being considered. Since the total mix variance is adverse for the Safe Soap Co, this mea that the actual mix used in September and October was more expensive than the standard mix.A material yield variance arises because the output which was achieved is different from the output which would havebeen expected from the inputs. So, whereas the mix variance focuses on inputs, the yield variance focuses on outputs.In both September and October, the yield variance was favourable, meaning that the inputs produced a higher level of output than one would have expected.(ii) Whilst the mix and yield variances provide Safe Soap Co with a certain level of information, they do not necess explain any quality issues which arise because of the change in mix. The consequences of the change may well have an impact on sales volumes. In Safe Soap Co’s case, the sales volume variance is adverse, meaning that sales volumes have fallen in October. It is not known whether they also fell in September but it would be usual for the effects on sal of the change in mix to be slightly delayed, in this case by one month, given that it is only once the customers receiving the slightly altered soap that they may start expressing their dissatisfaction with the product.There may also be other reasons for the adverse sales volume variance but given the customer complaints which have be en received, the sales manager’s views should be taken on board.Fundamentals Level – Skills Module, Paper F5 Performance ManagementDecember 2014 Marking SchemeSection AMarks 2 marks per question 40 ––– –––Section B 1(a) PriceCumulative average time per unit for 8 units Total time for 8 unitsCumulative average time per unit for 7 units Total time for 7 unitsIncremental time for 8th unit Cost for 8th unit Total cost 1 0·5 1 0·5 0·5 0·5 0·5 Price0·5 ––– 5 ––– (b) (i) Learning rateCalculating learning rateSaying whether better or worse2·5 0·5 ––– 3 ––– (ii) Effect on price2 ––– Total marks10 ––– ––– 2(a) (b)Calculation and justification of bottleneckExplanation of bottleneck 3 1 ––– 4 ––– TPARThroughput1 1 1 1 Throughput per bottleneck hour Total salon costs Cost per hour TPAR2 ––– 6 ––– Total marks10 ––– ––– 3Fabric calculation Fabric reason Wood calculation 0·5 0·5 1 Wood reason1 Skilled labour calculation Skilled labour reason1 1 Semi-skilled labour calculation Semi-skilled labour reason Factory overheads calculation Factory overheads reasonAdministration overheads reasonTotal relevant cost (lowest cost estimate) 0·5 1 0·5 1·5 1 0·5 ––– Total marks10 ––– –––Marks 4 (a)(b)PerspectivesExplanation for each perspective 1·5–––6–––Goals and measuresEach goal/measure/explanationPresentation and structure21–––9–––Total marks 15––––––5 (a)(b)Variance calculationsMix varianceQuantity variance44–––8–––(i) VariancesMarks per variance explained 2–––4–––(ii) DiscussionPer valid point 1–––3–––Total marks 15––––––。
2015年12月ACCA考试F5业绩管理真题SB部分_真题(含答案与解析)-交互
2015年12月ACCA考试F5业绩管理真题(SectionB部分)(总分60, 做题时间195分钟)Section BThe Chemical Free Clean Co (C Co) provides a range ofenvironmentally-friendly cleaning services to business customers, often providing a specific service to meet a client's needs. Its customers range from large offices and factories to specialist care wards at hospitals, where specialist cleaning equipment must be used and regulations adhered to. C Co offers both regular cleaning contracts and contracts for one-off jobs. For example, its latest client was a chain of restaurants which employed them to provide an extensive clean of all their business premises after an outbreak of food poisoning.The cleaning market is **petitive, although there are only a small number of companies providing a chemical free service. C Co has always used cost-plus pricing to determine the prices which it charges to its customers but recently, the cost of the cleaning products C Co uses has increased. This has meant that C Co has had to increase its prices, resulting in the loss of several regular customers to competing service providers.The finance director at C Co has heard about target costing and is considering whether it could be useful at C Co.Required:SSS_TEXT_QUSTI(a) Briefly describe the main steps involved in deriving a target cost.该题您未回答:х该问题分值: 3答案:Target costing stepsDeriving a target costStep 1: A product or service is developed which is perceived to be needed by customers and therefore will attract adequate sales volumes.Step 2: A target price is then set based on the customers' perceived value of the product. This will therefore be a market based price. Step 3: The required target operating profit per unit is then calculated. This may be based on either return on sales or return oninvestment.Step 4: The target cost is derived by subtracting the target profit from the target price.Step 5: If there is a cost gap, attempts will be made to close the gap. Techniques such as value engineering may be performed, which looks at every aspect of the value chain business functions with an objective of reducing costs while satisfying customer needs.Step 6: Negotiation with customers may take place before deciding whether to go ahead with the project.SSS_TEXT_QUSTI(b) Explain any difficulties which may be encountered and any benefits which may arise when implementing target costing at C Co.该题您未回答:х该问题分值: 7答案:Application at C CoDifficulties in implementation– C Co is a **pany and in **panies, it is often more difficult to find a precise definition for some of the services. In order for target costing to be useful, it is necessary to define the service being provided. C Co actually provides a range of services toclients including specialist care wards at hospitals. This meansthat the definition of the services being provided will vary. Different target costs will need to be derived for the different services provided.– C Co has two types of clients: regular clients and one-off clients. Since the service for regular clients is being repeated, it should be relatively easy to set a target cost for these jobs. However, for the one-off jobs, there may not be **parative data available and therefore setting the target cost will be difficult. – Similarly, some of the work available is very specialist. For example, cleaning restaurants and kitchens after an outbreak of food poisoning will require specialist techniques and adherence to a set of regulations with which C Co may not be familiar. It may be difficult to establish the market price for a service like this, thus making it difficult to derive a target cost.Benefits to C Co– Target costing is useful in competitive markets where a companyis not dominant in the market and therefore has to accept a marketprice for their products. C Co is operating in a competitive market and whilst the service offered by C Co is more specialist, it is clear from the recent drop in sales that price increases do lead to loss of customers. C Co cannot therefore ignore the market price for cleaning services and simply pass on cost increases as it has done. Target costing would therefore help C Co to focus on the marketprice of similar services provided by competitors, where this information is available.– If after calculating a target cost C Co finds that a cost gap exists, it will then be forced to examine its internal processes and costs more closely. It should establish why the prices of the products it uses have increased in the first place. If it cannot achieve any reduction in these prices, it should consider whether it can source cheaper non-chemical products from alternative suppliers. So, target costing will benefit C Co by helping it to focus on cost reduction and consequently customer retention.Note: More points could be made and would earn marks.Bus Co is a large bus operator, operating long-distance bus services across the country. There are two other national operators in the country. Bus Co's mission is to ‘be the market leader in long-distance transport providing a greener, cleaner service for passengers nationwide’. Last month, an independent survey of 40,000 passengers was carried out, the results of which are shown in the table below:Table: Bus passenger satisfaction % by national operator* denotes that the percentage has not yet been calculated.The ‘overall satisfaction’ percentages, which have not yet been inserted into the table, are calculated using a weighted average which reflects the importance customers place on each of the other three criteria above. The weightings used are as follows:The managing director (MD) of Bus Co has said: ‘Independent research has shown that our customers are the most satisfied of any national bus operator. We are now leading the way on what matters most to customers –value for money and punctuality.’Required:SSS_TEXT_QUSTI(a) Calculate the ‘overall satisfaction’ percentage for each operator.该题您未回答:х该问题分值: 2答案:CalculationsBus: (0·4 × 0·67) + (0·32 × 0·8) + (0·28 × 0·82) = 75·36%. Prime: (0·4 × 0·58) + (0·32 × 0·76) + (0·28 × 0·83) = 70·76%.Express: (0·4 × 0·67) + (0·32 × 0·76) + (0·28 × 0·89) = 76·04%.SSS_TEXT_QUSTI(b) Taking into account all the data in the table and your calculations from part (a), discuss whether the managing director's statement is true.该题您未回答:х该问题分值: 4答案:Accuracy of statementThe MD's statement says that Bus Co's customers are the mostsatisfied of any national bus operator. However, this is not quite the case since, when the ‘overall satisfaction’ levels are calculated, Express's level is 76·04% compared to Bus Co's 75·36%. So, the first part of the MD's statement is untrue.The MD then goes on to say that Bus Co is leading the way on what matters most to customers – value for money and punctuality. Given the weightings attached to these two criteria, it appears true to say that these are the factors which matter most to customers. Similarly, it is true to say that Bus Co is leading as regards punctuality, being 4 percentage points ahead of Prime and Express on this criterion. However, given that Express also has the same level of satisfaction as regards offering value for money, Bus Co is only leading ahead of Prime on this criterion, not ahead of Express. Therefore, whilst it can say that it is the leader on punctuality, it can only say that it is the joint leader on value for money.SSS_TEXT_QUSTI(c)When measuring performance using a ‘value for money’ approach, the criteria of economy, efficiency and effectiveness can be used. Required:Briefly define ‘efficiency’ and ‘effectiveness’ and suggest one performance measure for EACH, which would help Bus Co assess the efficiency and effectiveness of the service it provides.该题您未回答:х该问题分值: 4答案:VFM‘Efficiency’ focuses on the relationship between inputs and outputs, considering whether the maximum output is being achieved for the resources used.Performance measure:Occupancy rate of buses.Utilisation rate for buses.(utilisation rate = hours on theroad/total hours available)Utilisation rate for drivers.(Many others could be given too but only one was asked for.)‘Effectiveness’ focuses on the relationship between anorganisation's objectives and outputs, considering whether the objectives are being met.Possible performance measures:Percentage of customers satisfied with cleanliness of buses. Percentage of carbon emissions relative to target set.(Many others could be given too but only one was asked for.)The Organic Bread Company (OBC) makes a range of breads for sale direct to the public. The production process begins with workers weighing out ingredients on electronic scales and then placing themin a machine for mixing. A worker then manually removes the mix from the machine and shapes it into loaves by hand, after which the bread is then placed into the oven for baking.All baked loaves are then inspected by OBC's quality inspector before they are packaged up and made ready for sale. Any loaves which fail the inspection are donated to a local food bank.The standard cost card for OBC's ‘Mixed Bloomer’, one of its most popular loaves, is as follows:Budgeted production of Mixed Bloomers was 1,000 units for the quarter, although actual production was only 950 units. The total actual quantities used and their actual costs were:Required:SSS_TEXT_QUSTI(a) Calculate the total material mix variance and the total material yield variance for OBC for the last quarter.该题您未回答:х该问题分值: 7答案:Variance calculationsMix variancePer question, total g of materials per standard batch = 610 g. Therefore standard quantity to produce 950 units = 950 × 610 g = 579·5 kgPer question, actual total kg of materials used to produce 950 units = 570·5 kgAlternative yield calculation570·5 kg should yield (÷ 0·61 kg) = 935·25 loaves570·5 kg did yield = 950 loavesDifference = 14·75 FValued a t standard material cost = 14·75F × $1·34 = $19·77FSSS_TEXT_QUSTI(b) Using the information in the question, suggest THREE possible reasons why an ADVERSE MATERIAL YIELD variance could arise at OBC.该题您未回答:х该问题分值: 3答案:Material yield varianceThree reasons why an adverse material yield variance may arise:– The mix may not be **pletely out of the machine, leaving some mix behind.– Since the loaves are made by hand, they may be made slightly too large, meaning that fewer loaves can be baked.– Errors or changes in the mix may cause some loaves to be sub-standard and therefore rejected by the quality inspector.– The loaves might be baked at the wrong temperature and therefore be rejected by the quality inspector.Note: Many more reasons could be given.Cardio Co manufactures three types of fitness equipment: treadmills (T), cross trainers (C) and rowing machines (R). The budgeted sales prices and volumes for the next year are as follows:The standard cost card for each product is shown below.Labour costs are 60% fixed and 40% variable. General fixed overheads excluding any fixed labour costs are expected to be $55,000 for the next year.Required:SSS_TEXT_QUSTI(a) Calculate the weighted average contribution to sales ratio for Cardio Co.该题您未回答:х该问题分值: 4答案:Weighted average C/S ratioWeighted average contribution to sales ratio (WA C/S ratio) = total contribution/total sales revenue.WA C/S ratio = ($408,240 + $433,600 + $330,220)/($672,000 + $720,000 + $532,000)= $1,172,060/$1,924,000 = 60·92%.SSS_TEXT_QUSTI(b) Calculate the margin of safety in $ revenue for Cardio Co.该题您未回答:х该问题分值: 3答案:Margin of safetyMargin of safety = budgeted sales – breakeven salesBudgeted sales revenue = $1,924,000Fixed labour costs = {(420 × $220) + (400 × $240) + (380 × $190)} × 0·6 = $156,360k.Therefore total fixed costs = $156,360 + $55,000 = $211,360. Breakeven sales revenue = fixed costs/weighted average C/S ratio= $211,360/60·92% = $346,947Therefore margin of safety = $1,924,000 – $346,947 = $1,577,053.SSS_TEXT_QUSTI(c) Using the graph paper provided and assuming that the products are sold in a CONSTANT MIX, draw a multi-product breakeven chart for Cardio Co. Label fully both axes, any lines drawn on the graph and the breakeven point.该题您未回答:х该问题分值: 6答案:Multi-product breakeven chartWorkingsTotal revenue = $1,924,000.Total variable costs = $1,924,000 – $1,172,060 = $751,940. Therefore total costs = $211,360 + $751,940 = $963,300.SSS_TEXT_QUSTI(d) Explain what would happen to the breakeven point if the products were sold in order of the most profitable products first.Note: You are NOT required to demonstrate this on the graph drawn in part (c).该题您未回答:х该问题分值: 2答案:BEP if products sold in order of profitabilityIf the more profitable products are sold first, this means that**pany will cover its fixed costs more quickly. Consequently, the breakeven point will be reached earlier, i.e. fewer sales will need to be made in order to break even. So, the breakeven point will be lower.Cardale Industrial Metal Co (CIM Co) is a large supplier ofindustrial metals. **pany is split into two divisions: Division F and Division N. Each division operates separately as an investment centre, with each one having full control over its non-current assets. In addition, both divisions are responsible for their own current assets, controlling their own levels of inventory and cash and having full responsibility for the credit terms granted to customers and the collection of receivables balances. Similarly, each division has full responsibility for its current liabilities and deals directly with its own suppliers.Each divisional manager is paid a salary of $120,000 per annum plus an annual performance-related bonus, based on the return on investment (ROI) achieved by their division for the year. Each divisional manager is expected to achieve a minimum ROI for their division of 10% per annum. If a manager only meets the 10% target, they are not awarded a bonus. However, for each whole percentage point above 10% which the division achieves for the year, a bonus equivalent to 2% of annual salary is paid, subject to a maximum bonus equivalent to 30% of annual salary.The following figures relate to the year ended 31 August 2015:/During the year ending 31 August 2015, Division N invested $6·8m in new equipment including a technologically advanced cutting machine, which is expected to increase productivity by 8% per annum. Division F has made no investment during the year, although **puter system is badly in need of updating. Division F's manager has said that he hasalready had to delay payments to suppliers (i.e. accounts payables) because of limited cash and **puter system ‘will just have to wait’, although the cash balance at Division F is still better than that of Division N.Required:SSS_TEXT_QUSTI(a) For each division, for the year ended 31 August 2015, calculate the appropriate closing return on investment (ROI) on which the payment of management bonuses will be based. Briefly justify the figures used in your calculations.Note: There are 3 marks available for calculations and 2 marks available for discussion.该题您未回答:х该问题分值: 5答案:Division FControllable profit = $2,645k.Total assets less trade payables = $9,760k + $2,480k – $2,960k = $9,280k.ROI = 28·5%.Division NControllable profit = $1,970k.Total assets less trade payables = $14,980k + $3,260k – $1,400k = $16,840k.ROI = 11·7%.In both calculations controllable profit has been used to reflect profit, rather than net profit. This is because the managers do not have any control over the Head Office costs and responsibility accounting deems that managers should only be held responsible for costs which they control. The same principle is being applied in the choice of assets figures being used. The current assets and current liabilities figures have been taken into account in the calculation because of the fact that the managers have full control over both of these.SSS_TEXT_QUSTI(b) Based on your calculations in part (a), calculate each manager's bonus for the year ended 31 August 2015.该题您未回答:х该问题分值: 3答案:BonusBonus to be paid for each percentage point = $120,000 × 2% = $2,400. Maximum bonus = $120,000 × 0·3 = $36,000.Division F:ROI = 28·5% = 18 whole percentage points above minimum ROI of 10%.18 × $2,400 = $43,200.Therefore manager will be paid the maximum bonus of $36,000.Division N: ROI = 11·7% = 1 whole percentage point above minimum. Therefore bonus = $2,400.SSS_TEXT_QUSTI(c) Discuss whether ROI is providing a fair basis for calculating the managers' bonuses and the problems arising from its use at CIM Co for the year ended 31 August 2015.该题您未回答:х该问题分值: 7答案:Discussion– The manager of Division N will be paid a far smaller bonus than the manager of Division F. This is because of the large asset base on which the ROI figure has been calculated. Total assets ofDivision N are almost double the total assets of Division F. This is largely attributable to the fact that Division N invested $6·8m in new equipment during the year. If this investment had not been made, net assets would have been only $10·04m and the ROI for Division N would have been 19·62%. This would have led to the payment of a $21,600 bonus (9 × $2,400) rather than the $2,400 bonus. Consequently, Division N's manager is being penalised for making decisions which are in the best interests of his division. It is very surprising that he did decide to invest, given that he knewthat he would receive a lower bonus as a result. He has actedtotally in the best interests of **pany. Division F's manager, onthe other hand, has benefitted from the fact that he has made no investment even though it is badly needed. This is an example ofsub-optimal decision making.– Division F's trade payables figure is much higher than DivisionN's. This also plays a part in reducing the net assets figure on which the ROI has been based. Division F's trade payables are over double those of Division N. In part, one would expect this because sales are over 50% higher (no purchases figure is given). However,it is clear that it is also because of low cash levels at Division F. The fact that the manager of Division F is then being rewardedfor this, even though relationships with suppliers may be adversely affected, is again an example of sub-optimal decision making.– If the co ntrollable profit margin is calculated, it is 18·24%for Division F and 22·64% for Division N. Therefore, if capital employed is ignored, it can be seen that Division N is performing better. ROI is simply making the division's performance look worse because of its investment in assets. Division N's manager is likely to feel extremely demotivated by **paratively small bonus and, in the future, he may choose to postpone investment in order to increase his bonus. Managers not investing in new equipment and technology will mean that **pany will not keep up with industry changes and affect its overall **petitiveness.– To summarise, the use of ROI is leading to sub-optimal decision making and a lack of goal congruence, as what is good for the managers is not good for **pany and vice versa. Luckily, the manager at Division N still appears to be acting for the benefit of **pany but the other manager is not. The fact that one manager is receiving a much bigger bonus than the other is totally unfair here and may lead to conflict in the long run. This is not good for **pany, particularly if **es a time when the divisions need to work together.1。