
债券市场分析与策略第7版答案参考版
精选文档,供参考! CHAPTER 2 PRICING OF BONDS
CHAPTER SUMMARY This chapter will focus on the time value of money and how to calculate the price of a bond. When pricing a bond it is necessary to estimate the expected cash flows and determine the appropriate yield at which to discount the expected cash flows. Among other aspects of a bond, we will look at the reasons why the price of a bond changes
REVIEW OF TIME VALUE OF MONEY Money has time value because of the opportunity to invest it at some interest rate. Future Value The future value of any sum of money invested today is: Pn = P0(1+r)n where n = number of periods, Pn = future value n periods from now (in dollars), P0 = original principal (in dollars), r = interest rate per period (in decimal form), and the expression (1+r)n represents the future value of $1 invested today for n periods at a compounding rate of r.
When interest is paid more than one time per year, both the interest rate and the number of periods used to compute the future value must be adjusted as follows:
r = annual interest rate / number of times interest paid per year, and n = number of times interest paid per year times number of years.
The higher future value when interest is paid semiannually, as opposed to annually, reflects the greater opportunity for reinvesting the interest paid.
Future Value of an Ordinary Annuity When the same amount of money is invested periodically, it is referred to as an annuity. When the first investment occurs one period from now, it is referred to as an ordinary annuity.
The equation for the future value of an ordinary annuity is:
Pn =11nr A r where A is the amount of the annuity (in dollars). 精选文档,供参考!
Example of Future Value of an Ordinary Annuity Using Annual Interest: If A = $2,000,000, r = 0.08, and n = 15, then Pn = 11nr A r P15 = 08.01 17217.3 000,000,2$ = $2,000,000[27.152125] = $54,304.250.
Because 15($2,000,000) = $30,000,000 of this future value represents the total dollar amount of annual interest payments made by the issuer and invested by the portfolio manager, the balance of $54,304,250 – $30,000,000 = $24,304,250 is the interest earned by reinvesting these annual interest payments.
Example of Future Value of an Ordinary Annuity Using Semiannual Interest: Consider the same example, but now we assume semiannual interest payments. If A = $2,000,000 / 2 = $1,000,000, r = 0.08 / 2 = 0.04, n = 2(15) = 30, then
Pn = 11nr A r P30 = 04.01 )04. (1 000,000,1$ 30 = 04.01 2434.3 000,000,1$= $1,000,000[56.085] = $56,085,000. The opportunity for more frequent reinvestment of interest payments received makes the interest earned of $26,085,000 from reinvesting the interest payments greater than the $24,304,250 interest earned when interest is paid only one time per year.
Present Value The present value is the future value process in reverse. We have:
11nPVr
.
For a given future value at a specified time in the future, the higher the interest rate (or discount rate), the lower the present value. For a given interest rate (discount rate), the further into the future that the future value will be received, then the lower its present value.
Present Value of a Series of Future Values To determine the present value of a series of future values, the present value of each future value must first be computed. Then these present values are added together to obtain the present value of the entire series of future values. 精选文档,供参考!
Present Value of an Ordinary Annuity When the same dollar amount of money is received each period or paid each year, the series is referred to as an annuity. When the first payment is received one period from now, the annuity is called an ordinary annuity. When the first payment is immediate, the annuity is called an annuity due.
The present value of an ordinary annuity is:
111n rPV = A r
where A is the amount of the annuity (in dollars). The term in brackets is the present value of an ordinary annuity of $1 for n periods. Example of Present Value of an Ordinary Annuity Using Annual Interest:
If A = $100, r = 0.09, and n = 8, then: 111n rPV = A r = 811 1.09$100 0.09 = 11 1.99256$100 0.09
= 10.501867 $100 0.09 = $100[5.534811] = $553.48.
Present Value When Payments Occur More Than Once Per Year If the future value to be received occurs more than once per year, then the present value formula is modified so that (i) the annual interest rate is divided by the frequency per year, and (ii) the number of periods when the future value will be received is adjusted by multiplying the number of years by the frequency per year.
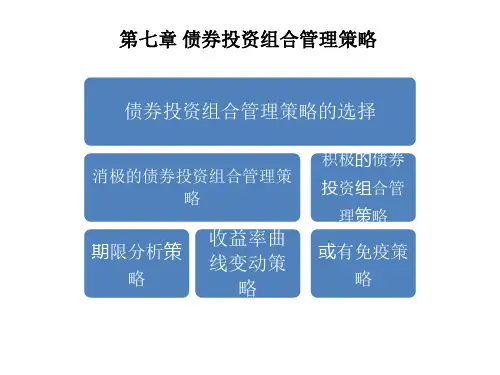
第七章 债券投资组合管理策略
债的影响方向相反、数额相等,两者互相抵消,就能
消除净资产面临的利率风险。
利率变化对资产和负债产生的影响可以用下式表示:
%ΔA=-DURA×(Δi)/(1+i)
%ΔD=-DURD×(Δi)/(1+i)
式中:%ΔA——(At-At+1)/At,资产市场价值变化的百分率;
降低。尽管利率上升,但零息债券的再投资收入却
不会增加,因此无法抵消价值降低的损失,无法保证
资产组合(零息债券)能产生足够的现金流偿还剩余
债务。显然,在目标期免疫策略中,第三个条件是自
动满足的。
3.净资产免疫策略
在免疫策略中还有一种特殊的免疫策略——净
资产免疫策略。净资产免疫策略的基本思想是:利
率变化对资产和负债的市场价值都会产生影响,对
一个无效的市场上,债券的价格或多或少遗漏了某
些影响债券价格的信息。
必须指出,在实践中,采取积极策略的债券投资
组合管理者并没有超过采取消极策略的投资者而
获得超额收益率。对发达国家(如美国)的债券市场
的实证研究表明,积极策略并没能明显地战胜市场 。
二、互换策略
(一)互换策略的定义
大体而言,债券互换策略就是指将预期收益率
市场价值变化量相当于总资产的百分比。
%ΔNW≈-DURgap×Δi/(1+i)
(7.3)
式中:%ΔNW——净资产市场价值的变化占总资产的
比重(以百分数表示)。
4.免疫策略的局限性
上述免疫策略在实际应用中也存在一些局限
性,认识到这些局限性对于成功的债券组合管理是
十分必要的。
第一,免疫策略是以久期为基础的,而久期只
高鸿业微观第七版第7章习题参考答案
第 1 页 共 13 页
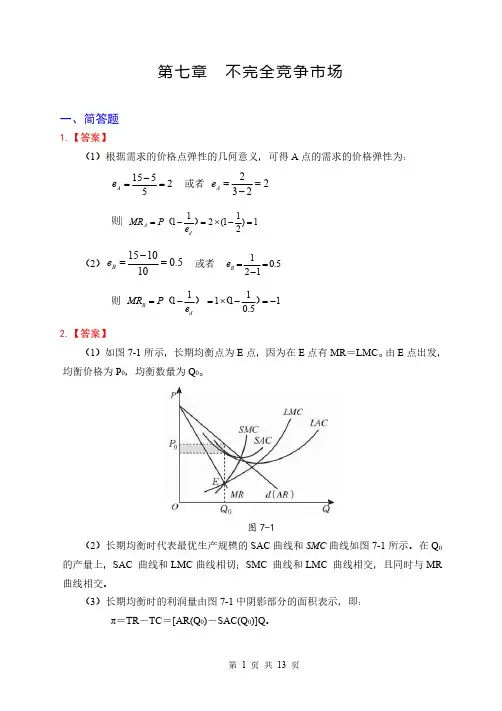
3.【答案】 由于垄断厂商所面临的需求曲线向右下方倾斜,导致了垄断厂商所面临的需求曲线
的位置高于边际收益 MR 曲线的位置,即 总有 P > MR。所以,在垄断厂商实现 MR = MC 利润最大化均衡时,必有 P > MC。
7.【答案】
(1)由长期总成本函数 LTC=0.001Q3-0.51Q2+200Q,可得:
LAC=0.001Q2-0.51Q+200。
垄断竞争厂商长期均衡时,利润为零,此时,D 与 LAC 相交,即有:AR=P=LAC,
代入相关参数可得:238-0.5Q=0.001Q2-0.51Q+200
解得 Q1=-190(舍去),Q2=200。
第 2 页 共 13 页
所以,当该垄断厂商实现利润最大化时,其产量 Q=2.5,价格 P=7,收益 TR =17.5,利润 л=4.25 (2)由已知条件可得 MR=8-0.8Q,令 MR=8-0.8Q=0,解得 Q=10
且 dTR 0.8 0 dQ
所以,当 Q=10 时,TR 值达最大值。 以 Q=10 代入反需求函数 P=8-0.4Q,得:P=8-0.4×10=4 则有:TR=PQ=4×10=40 л =TR-TC=PQ-TC
在经济学分析中,通常把厂商均衡时 P 与 MC 之间的大小比较作为衡量市场经 济效率的一个标准。在完全竞争市场条件下,厂商所面临的需求曲线与边际收益 MR 曲 线重合,即有 P=MR,所以,在完全竞争厂商实现 MR=MC 利润最大化均衡时,必 有 P=MC。在完全竞争厂商均衡的 P = MC 条件下,厂商销售产品的价格刚好等于生 产的边际成本,并实现了全部的消费者剩余和生产者剩余。而在垄断厂商均衡的 P > MC 条件下,厂商销售产品的价格大于等于生产的边际成本,且减少了消费者剩余和生 产者剩余,形成了社会福利的“无谓损失”。
战略管理试卷(7)参考答案
战略管理试卷(7)参考答案一、是非判断题(正确选A,错误选B。
每题1分,共10分)1.作为一种模式,战略将企业的主要目的、政策与活动按照一定的顺序结合成一个紧密的整体。
()答案:B答案分析:模式改为计划。
2.进入威胁的大小主要取决于进入壁垒高低,以及现有企业的反应程度。
( ) 答案:A3.企业的竞争优势是相对于竞争对手而言的一种绝对优势。
答案:B答案分析:竞争优势具有明显的相对性,任何企业的竞争优势都是相对于行业或竞争对手而言的,使竞争优势表现出非常强的动态性。
4.采取榨取性战略的目的是取得公司整体业绩的明显提高。
答案:错答案分析:采取发展性战略的目的是取得公司整体业绩的明显提高。
5.企业远景的内容包括企业的方向和实现企业方向的方式。
答案:B答案分析:企业远景的内容不仅包括企业的方向和实现企业方向的方式,还包括企业能够获得成功的原因。
6.新兴产业的企业最适合于开展专业化战略。
( )答案:A7.同一企业的战略业务单位之间不存在明显的替代可能,所以也就很难有相互的关系。
答案:B答案分析:同一企业的战略业务单位之间存在一定的相互关系。
一般来说,业务单位之间的关系不外乎有性关系、无形关系和竞争性关系。
8.市场开发战略是由新市场领域和现有产品领域结合而成的一种企业成长战略。
()答案:A9.战略集团是指在企业中同样的战略领域、遵循着相同或类似战略的公司群体。
()答案:B答案分析:战略集团企业的战略并不一定相似。
10.价值链分析的重点在于经营资源分析。
()答案:B答案分析:价值链分析的重点在于价值活动的分析二、单项选择题(每题1.5分,共30分)1.采用()的主要目的是使企业在退出某项业务之前,尽可能多地获得该项业务所能创造的收益,尽可能多地收回业务利润,尽可能少地影响企业其他业务的正常进行。
A、榨取性战略B、撤退性战略C、清算性战略D、选择性战略答案:A答案分析:这是榨取性战略的本质内涵。
2.如果企业处于SWOT矩阵的第SO象限,那么宜采取的战略是( )。
高鸿业第七版参考答案

万美元= 30 万美元,两个阶段共增值 40 万美元。
(3) 在生产活动中,所获工资共计
7.5 +5=12.5( 万美元 )
在生产活动中,所获利润共计
(10 - 7.5) +(30 -5) =27.5( 万美元 )
用收入法计得的 GDP为
12.5 +27.5 =40( 万美元 )
可见,用最终产品法、增值法和收入法计得的 GDP是相同的。
计算 GDP时,应把这 5 美元和 3 美元一起加到 92 美元中作为收入计入 GDP。
6. 假设某国某年发生了以下活动: (a) 一银矿公司支付 7.5 万美元工资给矿工开采了 50 千克银卖给一银器制造商, 售价 10 万美元; (b) 银器制造
商支付 5 万美元工资给工人加工一批项链卖给消费者,售价 40 万美元。
身上取得的收入来加以支付的,因而习惯上被看作是转移支付。
4.为什么政府给公务员发工资要计入 GDP,而给灾区或困难人群发的救济金不计入 GDP?
解答:政府给公务员发工资要计入 GDP是因为公务员提供了为社会工作的服务, 政府给他们的工资就是购买他们的服务,因此属于政府购买,而政府给灾区或困难
欢迎共阅
人群发的救济金不计入 GDP,并不是因为灾区或困难人群提供了服务,创造了收入, 相反,是因为他们发生了经济困难,丧失了生活来源才给予其救济的,因此这部分
救济金属于政府转移支付。政府转移支付只是简单地通过税收 ( 包括社会保险税 ) 把 收入从一个人或一个组织手中转移到另一个人或另一个组织手中,并没有相应的货
物或劳务的交换发生。所以政府转移支付和政府购买虽都属政府支出,但前者不计 入 GDP而后者计入 GDP。
5. 为什么企业向政府缴纳的间接税 ( 如营业税 ) 也计入 GDP?
完整版投资学第7版TestBank答案08
完整版投资学第7版TestBank答案08Chapter 8 Index ModelsMultiple Choice Questions1. As diversification increases, the total variance of a portfolio approaches____________.A) 0B) 1C) the variance of the market portfolioD) infinityE) none of the aboveAnswer: C Difficulty: EasyRationale: As more and more securities are added to the portfolio, unsystematic risk decreases and most of the remaining risk is systematic, as measured by the variance of the market portfolio.2. The index model was first suggested by ____________.A) GrahamB) MarkowitzC) MillerD) SharpeE) none of the aboveAnswer: D Difficulty: EasyRationale: William Sharpe, building on the work of Harry Markowitz, developed theindex model.3. A single-index model uses __________ as a proxy for the systematic risk factor.A) a market index, such as the S&P 500B) the current account deficitC) the growth rate in GNPD) the unemployment rateE) none of the aboveAnswer: A Difficulty: EasyRationale: The single-index model uses a market index, such as the S&P 500, as a proxyfor the market, and thus for systematic risk.163Chapter 8 Index Models4. The Security Risk Evaluation book published by Merrill Lynch relies on the__________ most recent monthly observations to calculate regression parameters.A) 12B) 36C) 60D) 120E) none of the aboveAnswer: C Difficulty: EasyRationale: Most published betas and other regression parameters, including those published by Merrill Lynch, are based on five years of monthly return data.5. The Security Risk Evaluation book published by Merrill Lynch uses the__________ asa proxy for the market portfolio.A) Dow Jones Industrial AverageB) Dow Jones Transportation AverageC) S&P 500 IndexD) Wilshire 5000E) none of the aboveAnswer: C Difficulty: EasyRationale: The Merrill Lynch data (and much of the other published data sets) are basedon the S&P 500 index as a market proxy.6. According to the index model, covariances among security pairs areA) due to the influence of a single common factor represented by the market index returnB) extremely difficult to calculateC) related to industry-specific eventsD) usually positiveE) A and DAnswer: E Difficulty: EasyRationale: Most securities move together most of the time, and move with a market index, or market proxy.164Chapter 8 Index Models7. The intercept calculated by Merrill Lynch in the regression equations is equal toA) αin the CAPM(1 + β) α+ rB) fC) α+ r (1 -β) fD) 1 -αE) none of the aboveAnswer: C Difficulty: ModerateRationale: The intercept that Merrill Lynch calls alpha is really, using the parameters ofthe CAPM, an estimate of a + rf (1 - b). The apparent justification for this procedure isthat, on a monthly basis, rf(1 - b) is small and is apt to beswamped by the volatility of actual stock returns.8. Analysts may use regression analysis to estimate the index model for a stock. Whendoing so, the slope of the regression line is an estimate of ______________.of the asset A) the αthe βof the asset B)C) the σof the assetD) the of the asset δnone of the above E)Answer: B Difficulty: ModerateRationale: The slope of the regression line, b, measures the volatility of the stock versusthe volatility of the market.9. In a factor model, the return on a stock in a particular period will be related to_________.A) firm-specific eventsB) macroeconomic eventsC) the error termboth A and B D)E) neither A nor BAnswer: D Difficulty: ModerateRationale: The return on a stock is related to both firm-specific and macroeconomic events.165Chapter 8 Index Models10. Rosenberg and Guy found that __________ helped to predict a firm's beta.A) the firm's financial characteristicsB) the firm's industry groupC) firm sizeD) both A and BE) A, B and C all helped to predict betas.Answer: E Difficulty: ModerateRationale: Rosenberg and Guy found that after controlling for the firm's financial characteristics, the firm's industry group was a significant predictor of the firm's beta.11. If the index model is valid, _________ would be helpful in determining the covariancebetween assets K and L.A) βkB) βLC) σMD) all of the aboveE) none of the aboveAnswer: D Difficulty: ModerateRationale: If the index model is valid A, B, and C are determinants of the covariancebetween K and L.12. Rosenberg and Guy found that ___________ helped to predict firms' betas.A) debt/asset ratiosB) market capitalizationC) variance of earningsD) all of the aboveE) none of the aboveAnswer: D Difficulty: ModerateRationale: Rosenberg and Guy found that A, B, and C were determinants of firms' betas.166Chapter 8 Index Models13. If a firm's beta was calculated as 0.6 in a regression equation, Merrill Lynch would statethe adjusted beta at a numberA) less than 0.6 but greater than zero.B) between 0.6 and 1.0.C) between 1.0 and 1.6.D) greater than 1.6.E) zero or less.Answer: B Difficulty: ModerateRationale: Betas, on average, equal one; thus, betas over time regress toward the mean,or 1. Therefore, if historic betas are less than 1, adjusted betas are between 1 and the calculated beta.14. The beta of Exxon stock has been estimated as 1.2 by Merrill Lynch using regressionanalysis on a sample of historical returns. The Merrill Lynch adjusted beta of Exxon stock would be ___________.A) 1.20B) 1.32C) 1.13D) 1.0E) none of the aboveAnswer: C Difficulty: ModerateRationale: Adjusted beta = 2/3 sample beta + 1/3(1); = 2/3(1.2) + 1/3 = 1.13.15. Assume that stock market returns do not resemble a single-index structure. An investment fund analyzes 100 stocks in order to construct a mean-variance efficient portfolio constrained by 100 investments. They will need to calculate _____________expected returns and ___________ variances of returns.A) 100, 100B) 100, 4950C) 4950, 100D) 4950, 4950E) none of the aboveAnswer: A Difficulty: ModerateRationale: The expected returns of each of the 100 securities must be calculated.Inaddition, the 100 variances around these returns must be calculated.167Chapter 8 Index Models16. Assume that stock market returns do not resemble a single-index structure. An investment fund analyzes 100 stocks in order to construct a mean-variance efficient portfolio constrained by 100 investments. They will need to calculate ____________covariances.A) 45B) 100C) 4,950D) 10,000E) none of the aboveAnswer: C Difficulty: ModerateRationale: (n2 - n)/2 = (10,000 - 100)/2 = 4,950 covariances must be calculated. 17. Assume that stock market returns do follow a single-index structure. An investmentfund analyzes 200 stocks in order to construct a mean-variance efficient portfolio constrained by 200 investments. They will need to calculate ________ estimates of expected returns and ________ estimates of sensitivity coefficients to the macroeconomic factor.A) 200; 19,900B) 200; 200C) 19,900; 200D) 19,900; 19.900E) none of the aboveAnswer: B Difficulty: ModerateRationale: For a single-index model, n(200), expected returns and n(200) sensitivity coefficients to the macroeconomic factor must be estimated.18. Assume that stock market returns do follow a single-index structure. An investmentfund analyzes 500 stocks in order to construct a mean-variance efficient portfolio constrained by 500 investments. They will need to calculate ________ estimates of firm-specific variances and ________ estimates for the variance of the macroeconomic factor.A) 500; 1B) 500; 500C) 124,750; 1D) 124,750; 500E) 250,000; 500Answer: A Difficulty: ModerateRationale: For the single-index model, n(500) estimates of firm-specific variances mustbe calculated and 1 estimate for the variance of the common macroeconomic factor. 168Chapter 8 Index Models19. Consider the single-index model. The alpha of a stock is 0%. The return on the marketindex is 16%. The risk-free rate of return is 5%. The stock earns a return that exceedsthe risk-free rate by 11% and there are no firm-specific events affecting the stock performance. The βof the stock is _______.A) 0.67B) 0.75C) 1.0D) 1.33E) 1.50Answer: C Difficulty: ModerateRationale: 11% = 0% + b(11%); b = 1.0.20. Suppose you held a well-diversified portfolio with a very large number of securities,and that the single index model holds. If the óof your portfolio was 0.20 and ówas M0.16, the βof the p ortfolio would be approximately ________.A) 0.64B) 0.80C) 1.25D) 1.56E) none of the aboveAnswer: C Difficulty: Difficult 22222 = 1.56; b = 1.25. m = b Rationale: s; (0.2)p / s/(0.16)21. Suppose the following equation best describes the evolution of βover time: β= 0.25 + 0.75βt-1t If a stock had a βof 0.6 last year, you would forecast the βto be _______ in the comingyear.A) 0.45B) 0.60。
投资学第7章习题及答案

课后习题1.简述债券的定义及种类。
2.影响债券定价的因素有哪些?这些因素如何影响债券价值的?3.简述债券定价原理。
4.简述常见的债券收益率。
5.什么是债券的时间价值?6.假定A公司发行了两种具有相同息票率和到期日的债券,一种是可赎回的,而另一种是不可赎回的,哪一种售价更高?7.有一30年期、息票率为8%的债券,计算其在市场半年利率为3%时的价格。
比较利率下降所造成的资本利得和当利率上升到5%时的资本损失。
8.两种10年期债券的到期收益率目前均为7%,各自的赎回价格皆为1100美元。
其中之一的息票率为6%,另一种为8%。
为简单起见,假定在债券的预期支付现值超过赎回价格时立即赎回。
如果市场利率突然降至6%,每种债券的资本利得分别是多少?第七章本章习题答案1. 债券(bond)是以借贷协议形式发行的证券。
借者为获取一定量的现金而向贷者发行(如出售)债券,债券是借者的“借据”。
这张借据使发行者有法律责任,需在指定日期向债券持有人支付特定款额。
典型的息票债券使发行者有义务在债券有效期内向持有人每半年付息一次,这叫做息票支付,因为在计算机发明之前,大多数债券带有息票,投资者将其剪下并寄给发行者索求利息。
债券到期时,发行者再付清面值(par value, face value)。
债券的息票率(coupon rate)决定了所需支付的利息:每年的支付按息票率乘以债券面值计算。
息票率、到期日和面值是债券契约(bond indenture)的各个组成部分,债券契约是债券发行者与持有者之间的合约。
政府债券的发行主体是政府。
政府债券是政府主体为筹措财政资金,以政府信用为基础向社会发行,承诺到期还本付息的一种债券凭证。
政府债券又分为中央政府债券和地方政府债券。
中央政府债券又称为国债。
公司债券,是公司按照法定程序发行,约定在一定期限内还本付息的债权债务凭证。
公司债券代表着发债的公司和投资者之间的一种债权债务关系。
债券持有人是公司的债权人, 不是所有者,无权参与或干涉公司经营管理,但债券持有人有权按期收回本息。
证劵投资试题库(附参考答案)
证劵投资试题库(附参考答案)一、单选题(共52题,每题1分,共52分)1.下列关于债券的特征说法正确的是( )。
A、债务人必须按期向债权人支付利息和偿还本金B、永续债的存在说明偿还性不是债券的一般特性C、债券的收益随发行者经营收益的变动而变动D、具有高度流动性的债券反而不安全正确答案:A答案解析:考查债券的特征。
债券的特征有:偿还性、流动性、安全性、收益性。
偿还性是指债券有规定的偿还期限,债务人必须按期向债权人支付利息和偿还本金。
永续债券只是债券中极少的部分,不能因此否定债券具有偿还性的一般特征。
债券的安全性是指债券持有人的收益相对稳定,不随发行者经营收益的变动而变动,并可按期收回本金。
一般来说,具有高度流动性的债券同时也是较安全的,因为它不仅可以迅速地转换为货币,而且可以按一个较稳定的价格转换。
2.在下列机构中,不符合中国证监会关于首次公开发行股票询价对象规定条件的是()。
A、信托投资公司B、证券公司C、商业银行D、财务公司正确答案:C3.沪深300指数( )调整一次。
A、1周B、1个月C、6个月D、12个月正确答案:C答案解析:沪深300每半年调整一次。
4.投资基金是指通过向投资者募集资金,形成独立基金财产,由专业投资机构进行基金投资和管理,由( )进行资产托管,由( )共享投资收益、共享投资风险的一种集合投资方式。
A、基金托管人基金投资人B、基金投资人基金管理人C、基金托管人基金管理人D、基金管理人基金投资人正确答案:A答案解析:考查投资基金的概念。
5.一般来说,具有高度流动性的债券同时也是较安全的,因为它不仅可以迅速地转换为货币,还可以按一个较稳定的价格转换。
关于债券不能收回投资的风险的说法有误的是( )。
A、债务人不履行债务导致债券不能收回投资B、市场利率水平影响债券的转让价格C、不同的债务人不履行债务的风险程度是不一样的D、政府债券不履行债务的风险较高正确答案:D答案解析:考查债券的安全性。
《债券市场:分析与策略(第九版)》名词解释索引----考试必备!!!
名词面数承诺收益率47字母承销标准192 alt-A贷款194初始贷款额与抵押品价值之比201 CD等价收益率122初始发行时的高收益债券138 CPR209传统赎回条款和再融资条款136 LIBOR曲线111次级贷款194 MBS205次级抵押贷款支持证券205 MMD尺度167次级留置权193 wi市场120次级债券类别148 A次级债务131按市价调整头寸10次主权政府债券175案件受托人132存续期利率上限195 B D保兑信用证161大型发行机构168保障性186贷款抵押债券147备用信用证161贷款额与抵押品价值之比192本国债券市场174贷款重估198本金4贷款组合补充文件209本金保值票据144担保费208本金剥离国债124担保品管理人148本金价值4担保信托债券131贬值177担保债券184变现再融资219单交易商系统140波动性风险10单一价格拍卖120剥息124单一类别抵押贷款支持证券206不可撤销的信用额度161单月提前偿付率210不可赎回136当期贷款额与抵押品价值之比201不可再融资136当期国债120布雷迪债券185当前可赎回债券136部分偿付199导管企业192部分提前清偿199到期价值4 C到期期限3参考利率195到期日1产业部门131到期收益率37常规抵押贷款199到期收益率预期解释108常规价格136道义责任债券159偿债基金159等值应税收益率91偿债基金条款137抵押贷款191偿债基金要求137抵押贷款发放人192偿债准备基金159抵押债券131抵押转手证券206浮动利率债券27地方性发行机构168浮动利率债券163递延利息债券138负凸性222递延赎回权136覆盖率测试148递延息票结构138G第二留置权193杠杆贷款146第一留置权193杠杆收购153盯市10高级135定期拍卖法183高级次级债务132定期债券135高级担保债务131陡峭收益率曲线105高级无担保债务131斗牛士债券174高级银行贷款146短端久期80高级债券类别148短期债券3高收益债券135对投资组合久期的贡献度67高质量债券135多交易商系统140个性化抵押贷款支持证券205堕落天使138更新和重置基金159 F公共部门借款要求186发行前交易市场120公司175发行人1公司债券2发行说明书补充文件209公用事业部门130反向浮动利率债券5购买力风险9反向浮动利率债券163股票挂钩票据143反向收益率曲线105固定本金证券118非分期偿还债券5固定利率抵押贷款195非合规常规贷款200挂钩债券183非竞争性投标119关键利率久期81非欧元区市场区175滚动发行144非套现再融资194滚动发行风险144非投资级144国际债券市场174非投资级债券135国际组织175非政府机构抵押贷款支持证券205国家机构175分批还本债券135国家认可统计评级机构133分期偿付证券42国家债券市场174分期偿还债券5国库券118分期还款195国内信贷比率186分期还款时间表196国债2风险的风险10H服务费192还款额与收入之比192浮动利率债券4合规常规贷款200合规贷款200交叉匹配系统140合规限额199交易日123合同相对人关系146交易商间经纪人120荷兰式拍卖法183交易商间系统140宏观经济基本面186交易商募集的商业票据145后端比率194结构化债券162互换利率111结构性票据142互换利率收益率曲线111结算日123互换曲线111借款人1回售收益率42金额久期66回售条款6金额凸性值71汇率177金融部门131汇率风险9金融机构175汇率风险177仅付利息产品198混合可调整利率抵押贷款195经营和维持基金159货币风险9净价30货币风险177竞争性投标120货币挂钩票据144久期向量81货币认购权证180久期中性68货币市场等价收益率122局部预期理论108 J巨额贷款199基本价格169巨额潘德布雷夫185基本余额186具有货币选择权的债券180基础利率88绝对利率变动51基础设施债务175绝对收益率变动51基点的价值59绝对优先权规则132基准利差88K基准利率88可变利率通知债券163即期利率95可对冲利率105即期利率曲线95可交换债券6季节性效应219可调整利率抵押贷款195加权平均存续期5可选A级贷款194加权平均贷款期限207可选择偿还债券163加权平均贷款账龄207可延长的调息结构139加权平均票面利率207可转换债券6加权平均期限207客户对交易商系统140加权平均剩余期限207L加速偿债基金条款138垃圾债券135价格波动性59离岸金融中心176简单年利率36离岸债券市场174离岸中心176欧洲中期票据181理论即期曲线95P利差久期66拍卖系统140利率风险7潘德布雷夫债券市场184利率久期81票面利率195利率期限结构93平均存续期5利率期限结构95平均存续期221利率上限27平坦的收益率曲线106利率下限27普通年金14利率与期限再融资194普通年金18利率再融资219普通收益率曲线105利率止跌债券180Q利息的利息7期初年金18利息的利息45期间利率上限195联邦住房管理局提前偿付经验209期限3零息债券4期限结构的流动性理论108零息债券22期限利差93留置权状况193期限偏好理论106流动性风险9期限再融资219流动性理论106气球型期限137伦勃朗债券174前端比率194伦敦银行同业拆借利率4清偿能力186 M清算132美国受托人计划132权益组别148美元价格债券169全价30美元区175全球债券181猛犬债券174R面积覆盖率测试148燃尽效应220面值4认购倍数120面值收益率曲线95认购权证180名义利率4SN商业不动产抵押贷款支持证券2内部收益率34升值177内部债券市场174实际久期77年金14实际天数计算惯例123年金18实物付息债券138 O市场分割理论106欧洲美元债券178市场风险7欧洲区175市场间利差89欧洲债券市场174市场内利差89市政票据163提前还款风险202市政债券2提前赎回赔偿条款137事件风险153提前赎回溢价137适销性风险9提前再融资市政债券162收益率88条件提前偿付率209收益率比率89调息公式4收益率变动百分比52贴现17收益率利差88贴现率17收益率曲线93贴现值17收益率曲线重构久期80停止收益率120收益率相对变动52通货膨胀保值国债118首次按面值赎回收益率40通货膨胀风险9首次赎回日136通货膨胀挂钩债券5首次赎回收益率40通货膨胀调整本金119受让人146头条风险153赎回价格40投资级144赎回价格136投资级贷款146赎回价值4投资级债券135赎回时间表40投资期分析51赎回时间表136投资期收益率51赎回收益率40凸性56赎回条款5凸性偏差110双货币债券180凸性值71双重担保158托管至期满债券162水龙头式拍卖法183W税后收益率91外部债务比率186税收风险166外国债券市场174私人抵押贷款保险商199完全分期还款贷款195速度209完全预期理论106缩期风险222违约风险8锁定期198违约损失率150 T维修准备基金159套现再融资194无限税收一般责任债券158特别拍卖法183武士债券174提前偿付S曲线220X提前偿付额42息票4提前偿付风险222息票剥离国债124提前偿付速度209息票利率4提前还款惩罚抵押贷款200息票利率或息票利率递减债券180提前还款额199现金流瀑布148现金流收益率42有偏预期理论106现金流收益率209有限税收一般责任债券158现金流收益率220与通货膨胀指数挂钩的证券118现值16预期理论106相对收益率利差89远期利率104项目融资176Z新发国债95再融资136新发国债120再融资136信用分析133再融资比率219信用风险8再融资风险186信用挂钩票据143再融资收益率40信用降级9再投资风险7信用降级风险9再投资风险46信用利差8再投资期149信用利差风险8再投资收益45信用评级8暂具占有权的债务人132信用评级转换表152脏价30信用评级转换矩阵152债券等价收益率122信用升级9债券等值收益率38信用债券131债券等值收益率220信用证协议161债券重构125循环信用额度161债务人1 Y债务认购权证180烟草税债券162长端久期80延期风险222长期国债118延期付息债券5长期债券3衍生抵押贷款支持证券产品206长期债券135扬基债券174折价24扬基债券177正式声明168一般赎回价格136正凸性76一般责任债券158正向倾斜收益率曲线105一级票据146证券化192已发国债120证券化204溢价24政府贷款198银行贴现额基础121政府机构抵押贷款支持证券205盈余基金159政府机构债券2应计利息30政治分析187永久性(无期限)债券180直接付款信用证161优级贷款194直接募集票据145优级债券135指数利率195中级债券135转让方法146中期国债118转手息票利率207中期票据141资产支持证券市场2中期债券3资金的总成本141中期债券135子弹式贷款146中上级债券135子弹债券137重组132子市场89逐步升息债券138总收益率47主权债券175组别181住房抵押贷款支持证券2组合前缀206住房抵押贷款支持证券204组合系数207住房周转率218最差收益率42注册的证券本金和利息的分离过程124最低价拍卖法183专项收益债券162最高收益率120。
投资学第7版testbank答案16
投资学第7版testbank答案16Multiple Choice Questions1. The duration of a bond is a function of the bond'sA) coupon rate.B) yield to maturity.C) time to maturity.D) all of the above.E) none of the above.Answer: D Difficulty: EasyRationale: Duration is calculated by discounting the bond's cash flows at the bond's yield to maturity and, except for zero-coupon bonds, is always less than time to maturity.2. Ceteris paribus, the duration of a bond is positively correlated with thebond'sA) time to maturity.B) coupon rate.C) yield to maturity.D) all of the above.E) none of the above.Answer: A Difficulty: ModerateRationale: Duration is negatively correlated with coupon rate and yield to maturity.3. Holding other factors constant, the interest-rate risk of a coupon bondis higher when the bond's:A) term-to-maturity is lower.B) coupon rate is higher.C) yield to maturity is lower.D) current yield is higher.E) none of the above.Answer: C Difficulty: ModerateRationale: The longer the maturity, the greater the interest-rate risk. The lower the coupon rate, the greater the interest-rate risk. The lower the yield to maturity, the greater the interest-rate risk. These concepts are reflected in the duration rules; duration is a measure of bond price sensitivity to interest rate changes (interest-rate risk).4. The "modified duration" used by practitioners is equal to the MacaulaydurationA) times the change in interest rate.B) times (one plus the bond's yield to maturity).C) divided by (one minus the bond's yield to maturity).D) divided by (one plus the bond's yield to maturity).E) none of the above.Answer: D Difficulty: ModerateRationale: D* = D/(1 + y)5. Given the time to maturity, the duration of a zero-coupon bond is higherwhen the discount rate isA) higher.B) lower.C) equal to the risk free rate.D) The bond's duration is independent of the discount rate.E) none of the above.Answer: D Difficulty: ModerateRationale: The duration of a zero-coupon bond is equal to the maturity of the bond.6. The interest-rate risk of a bond isA) the risk related to the possibility of bankruptcy of the bond's issuer.B) the risk that arises from the uncertainty of the bond's return causedby changes in interest rates.C) the unsystematic risk caused by factors unique in the bond.D) A and B above.E) A, B, and C above.Answer: B Difficulty: ModerateRationale: Changing interest rates change the bond's return, both in terms of the price of the bond and the reinvestment of coupon payments.7. Which of the following two bonds is more price sensitive to changes ininterest rates1) A par value bond, X, with a 5-year-to-maturity and a 10% coupon rate.2) A zero-coupon bond, Y, with a 5-year-to-maturity and a 10%yield-to-maturity.A) Bond X because of the higher yield to maturity.B) Bond X because of the longer time to maturity.C) Bond Y because of the longer duration.D) Both have the same sensitivity because both have the same yield tomaturity.E) None of the aboveAnswer: C Difficulty: ModerateRationale: Duration is the best measure of bond pricesensitivity; the longer the duration the higher the price sensitivity.8. Holding other factors constant, which one of the following bonds has thesmallest price volatilityA) 5-year, 0% coupon bondB) 5-year, 12% coupon bondC) 5 year, 14% coupon bondD) 5-year, 10% coupon bondE) Cannot tell from the information given.Answer: C Difficulty: ModerateRationale: Duration (and thus price volatility) is lower when the coupon rates are higher.9. Which of the following is not trueA) Holding other things constant, the duration of a bond increases withtime to maturity.B) Given time to maturity, the duration of a zero-coupon decreases withyield to maturity.C) Given time to maturity and yield to maturity, the duration of a bondis higher when the coupon rate is lower.D) Duration is a better measure of price sensitivity to interest ratechanges than is time to maturity.E) All of the above.Answer: B Difficulty: ModerateRationale: The duration of a zero-coupon bond is equal to time to maturity, and is independent of yield to maturity.10. The duration of a 5-year zero-coupon bond isA) smaller than 5.B) larger than 5.C) equal to 5.D) equal to that of a 5-year 10% coupon bond.E) none of the above.Answer: C Difficulty: EasyRationale: Duration of a zero-coupon bond equals the bond's maturity.11. The basic purpose of immunization is toA) eliminate default risk.B) produce a zero net interest-rate risk.C) offset price and reinvestment risk.D) A and B.E) B and C.Answer: E Difficulty: ModerateRationale: When a portfolio is immunized, price risk and reinvestment risk exactly offset each other resulting in zero net interest-rate risk.12. The duration of a par value bond with a coupon rate of 8% and a remainingtime to maturity of 5 years isA) 5 years.B) years.C) years.D) years.E) none of the above.Answer: D Difficulty: Moderate Rationale:Calculations are shown below.Yr.CF PV of CF@08%Weight * Yr. 1$80$80/ = $ * 1 =2$80$80/2 = $ * 2 =3$80$80/3 = $ * 3 =4$80$80/4 = $ * 4 =5$1,080$1,080/5 = $ * 5 = Sum$ yrs. (duration)13. The duration of a perpetuity with a yield of 8% isA) years.B) years.C) years.D) cannot be determined.E) none of the above.Answer: A Difficulty: EasyRationale: D = = years.14. A seven-year par value bond has a coupon rate of 9% anda modified durationofA) 7 years.B) years.C) years.D) years.E) none of the above.Answer: C Difficulty: DifficultRationale:Calculations are shown below.Yr.CF PV of CF@9%Weight * Yr.1$90$ X 1 =2$90$ X 2 =3$90$ X 3 =4$90$ X 4 =5$90$ X 5 =6$90$ X 6 =7$1,090$ X 7 =Sum$ years (duration)modified duration = years/ = years.15. Par value bond XYZ has a modified duration of 6. Which one of the followingstatements regarding the bond is trueA) If the market yield increases by 1% the bond's price will decrease by$60.B) If the market yield increases by 1% the bond's price will increase by$50.C) If the market yield increases by 1% the bond's price will decrease by$50.D) If the market yield increases by 1% the bond's price will increase by$60.E) None of the above.Answer: A Difficulty: ModerateRationale: = -D*-$60 = -6 X $1,00016. Which of the following bonds has the longest durationA) An 8-year maturity, 0% coupon bond.B) An 8-year maturity, 5% coupon bond.C) A 10-year maturity, 5% coupon bond.D) A 10-year maturity, 0% coupon bond.E) Cannot tell from the information given.Answer: D Difficulty: ModerateRationale: The longer the maturity and the lower the coupon, the greater the duration17. Which one of the following par value 12% coupon bondsexperiences a pricechange of $23 when the market yield changes by 50 basis pointsA) The bond with a duration of 6 years.B) The bond with a duration of 5 years.C) The bond with a duration of years.D) The bond with a duration of years.E) None of the above.Answer: D Difficulty: DifficultRationale: DP/P = -D X [D(1+y) / (1+y)]; = -D X [.005 / ]; D = .18. Which one of the following statements is true concerning the duration ofa perpetuityA) The duration of 15% yield perpetuity that pays $100 annually is longerthan that of a 15% yield perpetuity that pays $200 annually.B) The duration of a 15% yield perpetuity that pays $100 annually isshorter than that of a 15% yield perpetuity that pays $200 annually.C) The duration of a 15% yield perpetuity that pays $100 annually is equalto that of 15% yield perpetuity that pays $200 annually.D) the duration of a perpetuity cannot be calculated.E) None of the above.Answer: C Difficulty: EasyRationale: Duration of a perpetuity = (1 + y)/y; thus, the duration of a perpetuity is determined by the yield and is independent of the cash flow.19. The two components of interest-rate risk areA) price risk and default risk.B) reinvestment risk and systematic risk.C) call risk and price risk.D) price risk and reinvestment risk.E) none of the above.Answer: D Difficulty: EasyRationale: Default, systematic, and call risks are not part of interest-rate risk. Only price and reinvestment risks are part ofinterest-rate risk.20. The duration of a coupon bondA) does not change after the bond is issued.B) can accurately predict the price change of the bond for any interestrate change.C) will decrease as the yield to maturity decreases.D) all of the above are true.E) none of the above is true.Answer: E Difficulty: EasyRationale: Duration changes as interest rates and time to maturity change, can only predict price changes accurately for small interest rate changes, and increases as the yield to maturity decreases.21. Indexing of bond portfolios is difficult becauseA) the number of bonds included in the major indexes is so large that itwould be difficult to purchase them in the proper proportions.B) many bonds are thinly traded so it is difficult to purchase them ata fair market price.C) the composition of bond indexes is constantly changing.D) all of the above are true.E) both A and B are true.Answer: D Difficulty: ModerateRationale: All of the above are true statements about bond indexes.22. You have an obligation to pay $1,488 in four years and 2 months. In whichbond would you invest your $1,000 to accumulate this amount, with relative certainty, even if the yield on the bond declines to % immediately after you purchase the bondA) a 6-year; 10% coupon par value bondB) a 5-year; 10% coupon par value bondC) a 5-year; zero-coupon bondD) a 4-year; 10% coupon par value bondE) none of the aboveAnswer: B Difficulty: DifficultRationale: When duration = horizon date, one is immunized, or protected, against one interest rate change. The zero has D = 5. Since the other bonds have the same coupon and yield, solve for the closest value of T that gives D = years. = )/.10 - [ + T(.] / = ; .68 T - .68 + .68 = ; .68 T = ; T = ; T [ln ] = ln ; T = years, so choose the 5-year 10% coupon bond.23. Duration measuresA) weighted average time until a bond's half-life.B) weighted average time until cash flow payment.C) the time required to recoup one's investment, assuming the bond waspurchased for $1,000.D) A and C.E) B and C.Answer: E Difficulty: ModerateRationale: B and C are true, as one receives coupon payments throughout the life of the bond (for coupon bonds); thus, duration is less than time to maturity (except for zeros).24. DurationA) assesses the time element of bonds in terms of both coupon and termto maturity.B) allows structuring a portfolio to avoid interest-rate risk.C) is a direct comparison between bond issues with different levels ofrisk.D) A and B.E) A and C.Answer: D Difficulty: ModerateRationale: Duration is a weighted average of when the cash flows of a bond are received; thus both coupon and time to maturity are considered. If the duration of the portfolio equals the investor's horizon date, the investor is protected against interest rate changes.25. Identify the bond that has the longest duration (no calculationsnecessary).A) 20-year maturity with an 8% coupon.B) 20-year maturity with a 12% coupon.C) 15-year maturity with a 0% coupon.D) 10-year maturity with a 15% coupon.E) 12-year maturity with a 12% coupon.Answer: C Difficulty: ModerateRationale: The lower the coupon, the longer the duration. The zero-coupon bond is the ultimate low coupon bond, and thus would have the longest duration.26. When interest rates decline, the duration of a 10-year bond selling ata premiumA) increases.B) decreases.C) remains the same.D) increases at first, then declines.E) decreases at first, then increases.Answer: A Difficulty: ModerateRationale: The relationship between interest rates and duration is an inverse one.27. An 8%, 30-year corporate bond was recently being priced to yield 10%. TheMacaulay duration for the bond is years. Given this information, the bond's modified duration would be________.A)B)C)D)E) none of the aboveAnswer: C Difficulty: EasyRationale: D* = D/(1 + y); D* = =28. An 8%, 15-year bond has a yield to maturity of 10% and duration of years.If the market yield changes by 25 basis points, how much change will there be in the bond's priceA) %B) %C) %D) %E) none of the aboveAnswer: A Difficulty: ModerateRationale: ΔP/P = X / = %29. One way that banks can reduce the duration of their asset portfolios isthrough the use ofA) fixed rate mortgages.B) adjustable rate mortgages.C) certificates of deposit.D) short-term borrowing.E) none of the above.Answer: B Difficulty: EasyRationale: One of the gap management strategies practiced by banks is the issuance of adjustable rate mortgages, which reduce the interest rate sensitivity of their asset portfolios.30. The duration of a bond normally increases with an increase in。
平狄克微观经济学(第7版)习题详解(第13章博弈论和竞争策略)
平狄克《微观经济学》(第7版)第13章博弈论和竞争策略课后复习题详解跨考网独家整理最全经济学考研真题,经济学考研课后习题解析资料库,您可以在这里查阅历年经济学考研真题,经济学考研课后习题,经济学考研参考书等内容,更有跨考考研历年辅导的经济学学哥学姐的经济学考研经验,从前辈中获得的经验对初学者来说是宝贵的财富,这或许能帮你少走弯路,躲开一些陷阱。
以下内容为跨考网独家整理,如您还需更多考研资料,可选择经济学一对一在线咨询进行咨询。
1.合作博弈和非合作博弈之间的区别是什么?各给出一个例子。
答:(1)合作博弈与非合作博弈的区别①博弈按照参与人之间能否达成协议分为合作博弈与非合作博弈。
能达成协议的称为合作博弈,合作博弈强调团队理性;不能达成协议的称为非合作博弈,非合作博弈更注重个人理性。
②合作博弈和非合作博弈之间的主要差别是一份有约束力的合同,即在合作博弈中,参与人可以谈定能使他们设计共同策略的有约束力的合同,但在非合作博弈中是不可能的。
(2)合作博弈的一个例子是关于一个行业中的两个厂商谈判一项开发一种新技术的联合投资(假设其中任何一个厂商都没有能独自成功的足够知识)。
如果两个厂商能够签订一份分配联合投资利润的有约束力的合同,则使双方都获益的合作的结果就是可能的。
非合作博弈的一个例子就是两竞争的厂商相互考虑到对方的可能的行为,并独立确定价格或广告策略以夺取市场份额的情况。
2.什么是占优策略?为什么一个占优策略均衡是稳定的?答:占优策略指不管其对手采取什么策略,该竞争者采取的策略都是最优策略。
占优策略均衡是指博弈方都采用占优策略所达到的均衡。
占优策略均衡是一种纳什均衡。
纳什均衡指每一个竞争者都确信,在给定竞争对手策略决定的情况下,他选择了最好的策略。
占优策略均衡稳定的原因是参与者在均衡时都没有激励去改变各自的策略。
3.解释纳什均衡的含义。
它与占优策略均衡有何不同?答:(1)纳什均衡的含义纳什均衡指这样一种策略集,在这一策略集中,每一个博弈者都确信,在给定竞争对手策略决定的情况下,他选择了最好的策略。