
北美精算师(SOA)考试MFE 2012年4月课程大纲
Models for Financial Economics—April 2012The Models for Financial Economics is called Exam MFE by the SOA and Exam 3F by the CAS. This three-hour exam consist of 30 multiple-choice questions. Also, a normal distribution calculator will be available during the test by clicking a link on the item screen. Details are available on the Prometric Web Site. The examination is jointly sponsored and administered by the SOA, CAS, and the Canadian Institute of Actuaries (CIA). The examination is also jointly sponsored by the American Academy of Actuaries (AAA) and the Conference of Consulting Actuaries (CCA).The purpose of the syllabus is to develop the candidate’s knowledge of the theoretical basis of certain actuarial models and the application of those models to insurance and other financial risks. A thorough knowledge of calculus, probability, interest theory and the earlier chapters of the McDonald textbook (which are in the syllabus of Exam FM/2) is assumed. Formulas are provided for the density and distribution functions for the standard normal and lognormal random variables. For paper and pencil examinations, tables of the standard normal distribution function are provided. Since the tables will be provided to the candidate at the examination, candidates will not be allowed to bring copies of the tables into the examination room. For CBT candidates, a normal distribution calculator is provided. See the link below for more information.Note: It is anticipated that candidates will have done the relevant exercises in the textbooks. Check the Updates section of the web site for any changes to the exam or syllabus.The ranges of weights shown are intended to apply to the large majority of exams administered. On occasion, the weights of topics on an individual exam may fall outside the published range. Candidates should also recognize that some questions may cover multiple learning outcomes.Each multiple-choice problem includes five answer choices identified by the letters A, B, C, D, and E, only one of which is correct. Candidates must indicate responses to each question on the computer.As part of the computer-based testing process, a few pilot questions will be randomly placed in the exam (paper and pencil and computer-based forms). These pilot questions are included to judge their effectiveness for future exams, but they will NOT be used in the scoring of this exam. All other questions will be considered in the scoring. All unanswered questions are scored incorrect. Therefore, candidates should answer every question on the exam. There is no set requirement for the distribution of correct answers for theSOA/CAS/CIA multiple-choice preliminary examinations. It is possible that a particular answer choice could appear many times on an examination or not at all. Candidates are advised to answer each question to the best of their ability, independently from how they have answered other questions on the examination.Since the CBT exam will be offered over a period of a few days, each candidate will receive a test form composed of questions selected from a pool of questions. Statistical scaling methods are used to ensure within reasonable and practical limits that, during the same testing period of a few days, all forms of the test are comparable in content and passingcriteria. The methodology that has been adopted is used by many credentialing programs that give multiple forms of an exam.LEARNING OUTCOMES – MODELS FOR FINANCIAL ECONOMICSA. Interest rate models (10-15%)1. Evaluate features of the Vasicek and Cox-Ingersoll-Ross bond price models.2. Explain why the time-zero yield curve in the Vasicek and Cox-Ingersoll-Ross bondprice models cannot be exogenously prescribed.3. Construct a Black-Derman-Toy binomial model matching a given time-zero yieldcurve and a set of volatilities.B. Rational valuation of derivative securities (65-75%)1. Use put-call parity to determine the relationship between prices of European put andcall options and to identify arbitrage opportunities.2. Calculate the value of European and American options using the binomial model.3. Calculate the value of European options using the Black-Scholes option-pricingmodel.4.Identify the situations where the values of European and American options are thesame.5. Interpret the option Greeks.6.Explain the cash flow characteristics of the following exotic options: Asian, barrier,compound, gap, and exchange.7.Explain the properties of a lognormal distribution and explain the Black-Scholesformula as an expected value for a lognormal distribution.8.Explain what it means to say that stock prices follow a diffusion process.9. Apply Itô’s lemma in the one-dimensional case.C. Simulation (10-15%)1. Simulate lognormal stock prices.2. Use variance reduction techniques to accelerate convergence.D. Risk management techniques (5-10%)1. Explain and demonstrate how to control risk using the method of delta-hedging. Note: Concepts, principles and techniques needed for Exam MFE/3F are covered in thereference listed below. Candidates and professional educators may use otherreferences, but candidates should be very familiar with the notation and terminology used in the listed references.Texts – Models for Financial Economics*Derivatives Markets (Second Edition), 2006, by McDonald, R.L.,Chapter 9,Chapter 10, (excluding “Options on Commodities” on page 334),Chapter 11, Sections 11.1 – 11.4, Appendices 11.A and 11.B,Chapter 12, Sections 12.1–12.5, Appendix 12.A,Chapter 13, including Appendix 13.B,Chapter 14,Chapter 18,Chapter 19, Sections 19.1–19.5Chapter 20, Sections 20.1–20.6 (up to but excluding “Multivariate Itô’s Lemma”on pages 665-666) and 20.7 (up to but excluding “Valuing a Claim on S a Q b onpages 670-672 and excluding “Finding the lease rate” on top one-half of page669),Chapter 21, Sections 21.1 – 21.2 (excluding “What If the Underlying Asset Is Not an Investment Asset” on pages 688-690) and 21.3 ( excluding “The BackwardEquation” on pages 691-692, and excluding the paragraph on page 692 thatbegins “If a probability…” and through the end of the section),Chapter 22, Section 22.1 (but with only those definitions in Tables 22.1 and 22.2 that are relevant to Section 22.1),Chapter 23, Sections 23.1 – 23.2 (pp.744 thru the middle of p.746 only),Chapter 24, Sections 24.1–24.5 (up to but excluding “Forward rate agreements”on pages 806-808),Appendix B.1, Appendix C and including relevant Errata (see below).Unless otherwise stated chapter appendices are not included in the required readings from this text.*Any textbook errata are included below.Other Resources – Models for Financial Economicsfor paper/pencilExam MFE/Exam 3F Formulas and TablesFormulas and Tables for CBT:• A normal distribution calculator will be available during the test by clicking buttons on the item screen.•Formula documentSome Remarks on Derivatives MarketsDerivatives Markets, Errata 2006 Second Edition, by R. McDonald,/faculty/mcdonald/htm/typos2e.htmlAll released exam papers, since 2000 can be found here.Exam MFE/3F Sample Questions and Solutions (1-76)。
北美精算学会SOA考试制度简介

北美精算学会SOA考试制度简介北美精算学会(Society of Actuaries)是一个专注于精算学和保险领域的国际性组织,在全球范围内均有影响力。
作为北美地区最主要的精算学会,SOA关注精算领域的发展并且提供相应的培训和认证考试。
SOA的认证考试是所有精算师都必须通过的一组考试,用于确保他们在精算学领域具有足够的知识和技能以胜任相关工作。
在2023年起,SOA的考试制度将更加严格和深入。
下面介绍SOA 认证考试的相关内容、难度以及它对精算师职业发展的重要性。
1.考试制度SOA的认证考试至今仍被视为精算师们必须通过的考试之一。
当今SOA的认证考试分为基础知识考试(Fundamental exams)和专业知识考试(Professional exams)两类。
基础知识考试由两部分组成:SOA Exam P(Probability Model)和SOA Exam FM(Financial Mathematics)。
专业知识考试则分为许多不同领域,包括生命精算、健康精算、产险精算以及企业风险管理等。
在2023年起,SOA的认证考试将分为基础、中级和高级三个阶段考试,以帮助考生更好地理解精算学的核心知识并逐步积累相关技能。
SOA基础阶段考试包括Exam P、FM、IFM(Investment and Financial Markets)、LTAM(Long Term Actuarial Mathematics)、STAM(Short-Term Actuarial Mathematics),考生对以上四个考试都需通过。
中级和高级阶段考试则分别针对基础知识和专业技能进行深入掌握和应用的学习和考核。
通过SOA的认证考试可以获得SOA认证并且获得了了全球性的认可,可以证明考生在精算学领域拥有足够的知识和技能。
2.考试难度SOA的考试难度非常大,在所有考试中综合排名位居全球前列。
SOA认证考试广泛应用数学、概率、统计学、经济学等多个领域的知识,要求考生必须具备较强的数学和逻辑推理能力。
2012准精算师考试大纲

中国精算师资格考试准精算师部分A1数学考试时间:3小时考试形式:选择题考试要求:本科目是关于风险管理和精算中随机数学的基础课程。
通过本科目的学习,考生应该掌握基本的概率统计知识,具备一定的数据分析能力,初步了解各种随机过程的性质。
考生应掌握概率论、统计模型和应用随机过程的基本概念和主要内容。
考试内容:A、概率论(分数比例约为35%)1. 概率的计算、条件概率、全概公式和贝叶斯公式 (第一章)2. 联合分布律、边缘分布函数及边缘概率密度的计算 (第二章)3. 随机变量的数字特征 (§3.1、§3.2、§3.4)4. 条件期望和条件方差 (§3.3)5. 大数定律及其应用 (第四章)B、数理统计(分数比例约为25%)1. 统计量及其分布 (第五章)2. 参数估计 (第六章)3. 假设检验 (第七章)4. 方差分析 (§8.1)C、应用统计(分数比例约为10%)1. 一维线性回归分析 (§8.2)2. 时间序列分析(平稳时间序列及ARIMA模型) (第九章)D、随机过程(分数比例约为20%)1. 随机过程一般定义和基本数字特征 (第十章)2. 几个常用过程的定义和性质(泊松过程、更新过程、马氏过程、鞅过程和布朗运动) (第十一章)E、随机微积分(分数比例约为10%)1. 关于布朗运动的积分 (§11.5、第十二章)2. 伊藤公式 (§12.2)考试指定教材:中国精算师资格考试用书:《数学》肖宇谷主编,李勇权主审,中国财政经济出版社2010版,所有章节。
A2 金融数学考试时间:3小时考试形式: 选择题考试要求:本科目要求考生具有较好的数学知识背景。
通过学习本科目, 考生应该熟练掌握利息理论、利率期限结构与随机利率模型、金融衍生工具定价理论、投资组合理论的主要内容,在了解基本概念、基本理论的基础上,掌握上述几部分内容涉及的方法和技巧。
北美精算师大纲精品文档20页

基本教育阶段(6门课程):课程1:精算科学的数学基础说明:这门课程的目的是为了培养关于一些基础数学工具的知识,形成从数量角度评估风险的能力,特别是应用这些工具来解决精算科学中的问题。
并且假设学员在学习这门课程之前已经熟练掌握了微积分、概率论的有关内容及风险管理的基本知识。
主要内容及概念:微积分、概率论、风险管理(包括损失频率、损失金额、自留额、免赔额、共同保险和风险保费)课程2:利息理论、经济学和金融学说明:这门课程包括利息理论,中级微观经济学和宏观经济学,金融学基础。
在学习这门课程之前要求具有微积分和概率论的基础知识。
主要内容及概念:利息理论,微观经济学,宏观经济学,金融学基础课程3:随机事件的精算模型说明:通过这门课程的学习,培养学员关于随机事件的精算模型的基础知识及这些模型在保险和金融风险中的应用。
在学习这门课程之前要求熟练掌握微积分、概率论和数理统计的相关内容。
建议学员在通过课程1和课程2后学习这门课程。
主要内容及概念:保险和其它金融随机事件,生存模型,人口数据分析,定量分析随机事件的金融影响课程4:精算建模方法说明:该课程初步介绍了建立模型的基础知识和用于建模的重要的精算和统计方法。
在学习这门课程之前要求熟练掌握微积分、线性代数、概率论和数理统计的相关内容。
主要内容及概念:模型-模型的定义-为何及如何使用模型-模型的利弊-确定性的和随机性的模型-模型选择-输入和输出分析-敏感性检验-研究结果的检验和反馈方法-回归分析-预测-风险理论-信度理论课程5-精算原理应用说明:这门课程提供了产品设计,风险分类,定价/费率拟定/建立保险基金,营销,分配,管理和估价的学习。
覆盖的范围包括金融保障计划,职工福利计划,事故抚恤计划,政府社会保险和养老计划及一些新兴的应用领域如产品责任,担保的评估,环境的维护成本和制造业的应用。
该课程的学习材料综合了各种计划和覆盖范围以展示精算原理在各研究领域中应用的一致性和差异性。
北美精算学会-SOA-考试制度第2页-精算师考试.doc
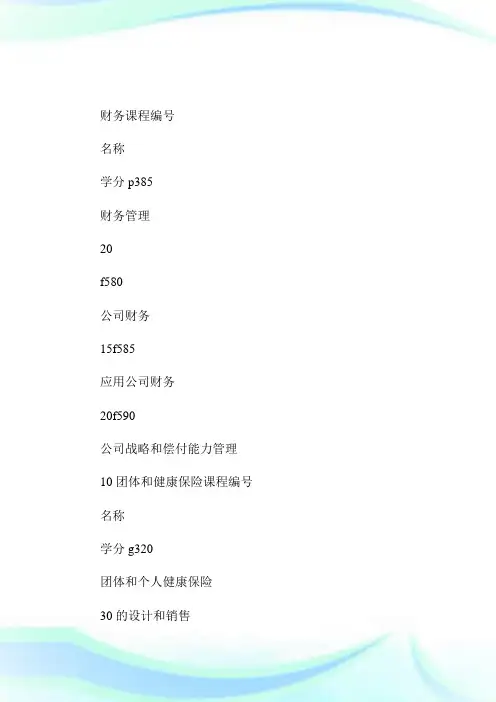
财务课程编号名称学分p385财务管理20f580公司财务15f585应用公司财务20f590公司战略和偿付能力管理10团体和健康保险课程编号名称学分g320团体和个人健康保险30的设计和销售g421团体和个人健康保险25的财务管理和法规g422团体和个人健康保险25的定价g522高级品种10g523非养老年金的退休后10和就业前的福利g525灵活的福利计划10g528健康保险专题15个人人寿和年金保险课程编号名称学分l340个人人寿和年金保险30的精算实务调查l343 人寿保险法和税收15n41高级设计和定价25n43估价和财务报告专题25l540个人人寿和年金保险10的营销l545丧失工作能力收入15l550再保险专题15养老金课程编号名称学分p360养老金估价原理15p362退休计划设计15p363养老金筹资工具15p365养老金计划的法律规定25p461养老金估价原理ii和20养老金计划会计标准p560 国际养老金问题20p564作为专家证人的10p567退休收入保障25投资课程编号名称学分v480衍生证券:理论和应用20v485高级资产组合管理15v595资产和负伤管理应用20要取得fsa资格必须通过以上一个方向的所有课程考试,以及再选择以上方向的其他课程,使学分达到150分,即学分总计要达到450分。
此外,当fsa要素的课程考试全部通过后,考生还要参加最后一门课程一一正认可课程(fac),其内容主要是职业道德和案例,时间为二天半,一般只要自始自终参加,在结束后的晚宴上会获得fsa证书。
到1996年,北美精算学会共有会员16,558名,其中美国11,961名,加拿大3,161名,其他国家1,436名,(除了fsa、asa外,还包括少量的财产和意外险和美国养老金)20,592人,其中美国15,695人,加拿大3,355人,其他国家1,542人。
北美精算学会的考点分布在全世界28个国家和地区,考试每年在春季(五月)和秋季(十一月)举行两次,全世界每年有数干人参加asa一万多门次课程的考试,其中asa的平均通过率为40%。
SOA精算考试课程及大纲

SOA精算考试课程及大纲-高级教育阶段高级教育阶段(2门课程):课程1 精算模型应用说明:该课程向学员介绍了建立精算模型实际考虑的因素。
要求学员具备基础课程的知识。
课程的一部分内容对所有的学员都是相同的。
要强调的是学员要重视与其从事的领域相关的技术和问题,这些内容因学员从事的领域而异。
模型可用于精算科学的许多方面,如定价/费率拟定,保险利益设计,资产/负债/资本管理,资产和负债估价,动态偿付能力检验。
不论模型用于哪一方面,其步骤是相同的。
该课程将概述这些步骤。
完成课程的学习后,学员将学会建模的过程并且用来解决一些问题。
主要内容和概念:模型设计或选择,数据输入分析,数据输出分析,结果的比较、检验和反馈。
课程2(a) 高级精算实务-金融说明:该课程研究金融中的高级内容。
学员在完成课程的学习后可加深在一些领域如:金融机构的资本管理,公司财务,金融风险管理(工具和技术),征税原理,期权定价理论和应用,发展金融战略等的知识和技能。
该课程帮助学员培养在保险公司、储蓄和信用机构、银行等金融机构从事金融和财税工作所应具备的技能。
课程的一些研究领域如期权和套利定价理论和应用,金融原理,资本结构和投资组合管理要求有严格的数学基础,目的是让学员能将这些原理应用于广阔的经济环境。
综合了数学、金融和经济知识及前面课程的技能将使学员在金融机构的管理起到不可代替的作用。
课程2(b) 高级精算实务-团体人寿险;个人和团体健康险说明:该课程对精算原理在团体人寿险和以个人及团体险形式提供下列保障:残疾收入,牙科支出,医疗和长期护理费用的险种中的应用进行深入的探讨。
该课程内容将包括提供这些保障的系统:保险公司,兰十字/兰盾组织,公众健康组织,会员优先服从组织,健康维护组织及Physician 医院组织。
课程2(c) 高级精算实务-健康管理计实务说明:该课程能为精算原理在医疗及牙科服务领域中的费用提供深入而有效的方法。
该课程内容包括以下健康管理组织机构:健康维护组织,Preferred Provider Organizations(PPOs),牙齿健康维护组织,Physician医院组织及医疗风险合同。
北美精算师介绍课程的介绍精算师考试.doc

ASA的课程课程1:精算科学的数学基础(MathematicalfoundationsofActuarialScience)这门课程的目的是为了培养关于一些基础数学工具的知识,形成从数量角度评估风险的能力,特别是应用这些工具来解决精算科学中的问题。
主要内容及概念:微积分、概率论、风险管理(包括损失频率、损失金额、自留额、免赔额、共同保险和风险保费)。
课程2:利息理论,经济与金融(InterestTheory,EconomicsandFinance)这门课程包括利息理论,中级微观经济学和宏观经济学,金融学基础。
课程3:关于风险的精算模型(ActuaricalModels)通过这门课程的学习,培养学员关于随机事件的精算模型的基础知识及这些模型在保险和金融风险中的应用。
主要内容包括:保险和其它金融随机事件,生存模型,人口数据分析,定量分析随机事件的金融影响。
课程4:精算建模方法(ActuarialModeling)该课程初步介绍了建立模型的基础知识和用于建模的重要的精算和统计方法。
主要内容包括:为何及如何选择和使用模型,回归分析,风险理论和信用理论。
课程5:基本精算原理的应用(ApplicationofBasicActuarialPrinciples)这门课程提供了产品设计,风险分类,定价/费率拟定/建立保险基金,营销,分配,管理和估价的学习。
覆盖的范围包括金融保障计划,职工福利计划,事故抚恤计划,政府社会保险和养老计划及一些新兴的应用领域如产品责任,担保的评估,环境的维护成本和制造业的应用。
课程6:金融与投资(FinanceandInvestments)该课程是用于投资和资产负债管理领域的精算原理的拓展。
学员在完成该课程的学习后,将会对资本市场、投资工具、衍生证券及应用、投资组合管理和资产-负债管理有深入的了解。
主要内容及概念:资本市场和基本投资原理,投资工具,衍生证券,投资组合管理的原理,资产负债管理。
北美精算考试简介
016*.高级非寿险精算实务
017*.团体保险 018*.意外伤害和健康保险 019*.投资学 020*.养老金计划
A S A R U C
Actuarial Student Association at RUC
1.精算数学基础 概率论 P 2.金融数学 FM 3.精算模型 MLC/MFE 4.精算建模方法 C 5.VEE 统计,经济,财务 6.FAP 实务 7.CERA(ERM,FSA module) 高级精算实务—金融经济理论 DP.高级精算实务—团体人寿险;个人和团体健康险设计定价 DP.高级精算实务—个险,年金设计定价(北美,加拿大) Advanced Portfolio Management CSP养老金计划美国,加拿大 CSP个人和团体健康险设计定价美国加拿大 Decision Making and Communication (DMAC) Module Fellowship Admissions Course (FAC)
折扣申请
考试时间(P:2、3、7、9、11月;FM-C:5、11月)
各科目的准备时间
评分方式 (10分制)
计算器
BA-35、BA II Plus、TI-30X、TI-30Xa、TI-30XIIS、TI-30XIIB
中国人民大学学生精算协会
2.金融数学 FM 3.精算模型 MLC/MFE
4.精算建模方法 C 5.VEE 统计,经济,财务 6.FAP 实务 7.CERA(ERM,FSA module) 高级精算实务—金融经济理论 DP.高级精算实务—团体人寿险; 个人和团体健康险设计定价 DP.高级精算实务—个险,年金设 计定价(北美,加拿大) Advanced Portfolio Management CSP养老金计划美国,加拿大
北美精算师大纲
基本教育阶段(6门课程):课程1:精算科学的数学基础说明:这门课程的目的是为了培养关于一些基础数学工具的知识,形成从数量角度评估风险的能力,特别是应用这些工具来解决精算科学中的问题。
并且假设学员在学习这门课程之前已经熟练掌握了微积分、概率论的有关内容及风险管理的基本知识。
主要内容及概念:微积分、概率论、风险管理(包括损失频率、损失金额、自留额、免赔额、共同保险和风险保费)课程2:利息理论、经济学和金融学说明:这门课程包括利息理论,中级微观经济学和宏观经济学,金融学基础。
在学习这门课程之前要求具有微积分和概率论的基础知识。
主要内容及概念:利息理论,微观经济学,宏观经济学,金融学基础课程3:随机事件的精算模型说明:通过这门课程的学习,培养学员关于随机事件的精算模型的基础知识及这些模型在保险和金融风险中的应用。
在学习这门课程之前要求熟练掌握微积分、概率论和数理统计的相关内容。
建议学员在通过课程1和课程2后学习这门课程。
主要内容及概念:保险和其它金融随机事件,生存模型,人口数据分析,定量分析随机事件的金融影响课程4:精算建模方法说明:该课程初步介绍了建立模型的基础知识和用于建模的重要的精算和统计方法。
在学习这门课程之前要求熟练掌握微积分、线性代数、概率论和数理统计的相关内容。
主要内容及概念:模型-模型的定义-为何及如何使用模型-模型的利弊-确定性的和随机性的模型-模型选择-输入和输出分析-敏感性检验-研究结果的检验和反馈方法-回归分析-预测-风险理论-信度理论课程5-精算原理应用说明:这门课程提供了产品设计,风险分类,定价/费率拟定/建立保险基金,营销,分配,管理和估价的学习。
覆盖的范围包括金融保障计划,职工福利计划,事故抚恤计划,政府社会保险和养老计划及一些新兴的应用领域如产品责任,担保的评估,环境的维护成本和制造业的应用。
该课程的学习材料综合了各种计划和覆盖范围以展示精算原理在各研究领域中应用的一致性和差异性。
北美精算师考试大纲 2012-May-exam-p
Probability ExamThe Probability Exam is called Exam P by the SOA and Exam 1 by the CAS. This three-hour exam consists of 30 multiple-choice questions. The examination is jointly sponsored and administered by the SOA, CAS, and the Canadian Institute of Actuaries (CIA). The examination is also jointly sponsored by the American Academy of Actuaries (AAA) and the Conference of Consulting Actuaries (CCA).The Probability Exam is administered as a computer-based test. For additional details, Please refer to Exam Rules.The purpose of the syllabus for this examination is to develop knowledge of the fundamental probability tools for quantitatively assessing risk. The application of these tools to problems encountered in actuarial science is emphasized. A thorough command of the supporting calculus is assumed. Additionally, a very basic knowledge of insurance and risk management is assumed.A table of values for the normal distribution is available below for candidates to download and will be included with the examination. Since the table will be included with the examination, candidates will not be allowed to bring copies of the table into the examination room.Check the Updates section on this exam’s home page for any changes to the exam or syllabus.The ranges of weights shown are intended to apply to the large majority of exams administered. On occasion, the weights of topics on an individual exam may fall outside the published range. Candidates should also recognize that some questions may cover multiple learning outcomes.Each multiple-choice problem includes five answer choices identified by the letters A, B, C, D, and E, only one of which is correct. Candidates must indicate responses to each question on the computer.As part of the computer-based testing process, a few pilot questions will be randomly placed in the exam (paper and pencil and computer-based forms). These pilot questions are included to judge their effectiveness for future exams, but they will not be used in the scoring of this exam. All other questions will be considered in the scoring. All unanswered questions are scored incorrect. Therefore, candidates should answer every question on the exam. There is no set requirement for the distribution of correct answers for the SOA/CAS/CIA multiple-choice preliminary examinations. It is possible that a particular answer choice could appear many times on an examination or not at all. Candidates are advised to answer each question to the best of their ability, independently from how they have answered other questions on the examination.Since the CBT exam will be offered over a period of a few days, each candidate will receive a test form composed of questions selected from a pool of questions. Statistical scaling methods are used to ensure within reasonable and practical limits that, during the same testing period of a few days, all forms of thetest are comparable in content and passing criteria. The methodology that has been adopted is used by many credentialing programs that give multiple forms of an exam.LEARNING OUTCOMESCandidates should be able to use and apply the following concepts in a risk management context:1. General Probability (15-30%)•Set functions including set notation and basic elements of probability•Mutually exclusive events•Addition and multiplication rules•Independence of events•Combinatorial probability•Conditional probability•Bayes Theorem / Law of total probability2. Univariate probability distributions (including binomial, negative binomial, geometric,hypergeometric, Poisson, uniform, exponential, gamma, and normal) (30-50%)•Probability functions and probability density functions•Cumulative distribution functions•Mode, median, percentiles, and moments•Variance and measures of dispersion•Moment generating functions•Transformations3. Multivariate probability distributions (including the bivariate normal) (30-45%)•Joint probability functions and joint probability density functions•Joint cumulative distribution functions•Central Limit Theorem•Conditional and marginal probability distributions•Moments for joint, conditional, and marginal probability distributions•Joint moment generating functions•Variance and measures of dispersion for conditional and marginal probability distributions•Covariance and correlation coefficients•Transformations and order statistics•Probabilities and moments for linear combinations of independent random variablesREFERENCESSuggested TextsThere is no single required text for this exam. The texts listed below may be considered as representative of the many texts available to cover material on which the candidate may be examined. Texts are added and deleted as part of a regular process to keep the list up-to-date. The addition or deletion of a textbook does not change the bank of questions available for examinations. There is no advantage to selecting a text recently added or not using a text recently removed.Not all the topics may be covered adequately by just one text. Candidates may wish to use more than one of the following or other texts of their choosing in their preparation. Earlier or later editions may also be adequate for review.• A First Course in Probability (Eighth Edition), 2009, by Ross, S.M., Chapters 1–8.•Mathematical Statistics with Applications (Seventh Edition), 2008, by Wackerly, D., Mendenhall III, W., Scheaffer, R., Chapters 1-7.•Probability for Risk Management, (Second Edition), 2006, by Hassett, M. and Stewart,D., Chapters 1–11.• Probability and Statistical Inference (Eighth Edition), 2009, by Hogg, R.V. and Tanis,E.A., Chapters 1–5.•Probability and Statistics with Applications: A Problem Solving Text, 2010, by Asimow, L. and Maxwell, M.•Probability: The Science of Uncertainty with Applications to Investments, Insurance and Engineering 2009, by Bean, M.A., Chapters 1–9.Other ResourcesThe candidate is expected to be familiar with the concepts introduced in “Risk and Insurance”.Tables for Exam P/1Exam P/1 Sample Questions and Solutions (1–153)Risk and Insurance。
北美精算师考试教材
P:指定教材:Fundamentals of Probability ¥200 1.5 kgSolution manual of Fundamentals of Probability ¥80A First Course in Probability, 7th Ed ¥150考试manual:ASM版Exam P 9th Edition (2008秋)study manual ¥90 1.5kgASM版Exam P 10th Edition (2009春)study manual ¥200 1.5kgACTEX版Exam P (2009春)study manual ¥180 1.5kgGUO版Exam P (2009春)study manual ¥160 1.5kgDAR新版Exam P Equation Study List公式手册¥20FM:指定教材:Financial Mathematics ¥70.00 1kgMathematics of Investment and Credit, 3rd Edition, 2004 ¥120.00 1kg Mathematics of Investment and Credit Solutions Manual ¥80 0.5kgThe Theory of Interest 2nd Edition ¥55 1kgDerivatives Markets 2nd edition ¥140.00 2kg (这本书fm mfe c都需要用到)Derivatives Markets Solution Manual Second Edition ¥80.00 0.5kg考试manual:ASM版Exam FM 8th Edition (2008秋)study manual ¥160ASM版Exam FM 9th Edition (2009春)study manual ¥200 1.5kgACTEX版Exam FM (2009春)study manual ¥220 1.5kgGUO版Exam FM (2009春)study manual ¥180 1.5kgDAR新版Exam FM Equation Study List公式手册¥20MFE:指定教材:Derivatives Markets 2nd editionDerivatives Markets Solution Manual Second Edition考试manual:ASM版Exam MFE 8th Edition (2008秋)study manual ¥70 1.5kg ASM版Exam MFE 9th Edition (2009春)study manual ¥180 1.5kg ACTEX版Exam MFE (2009春)study manual ¥240 1.5kgGUO版Exam MFE (2009春)study manual ¥200 1.5kgMLC:指定教材:Actuarial Mathematics, 2nd Edition ¥105.00 2kgSolutions Manual for Bowers' et al Actuarial Mathematics ¥80.00 0.5kg Introduction to Probability Models, 8th Edition, 2003 ¥100 1.5kg考试manual:ASM版Exam MLC 7th Edition (2008秋)study manual ¥240 2.5kg ACTEX版Exam MLC (2008春)study manual ¥130 1.5kgGUO版Exam MLC (2009春)study manual ¥260 1.5kgDAR新版Exam MLC Equation Study List公式手册¥30C:指定教材:Loss Models From Data to Decisions ¥90 2kgSolutions Manual to Loss Models From Data to Decisitions ¥80 0.5kg Foundations of Casualty Actuarial Science, 4th Edition, 2001 ¥90 1.5kg 考试manual:ASM版Exam C 8th Edition (2008秋)study manual ¥260 2.5kg ACTEX版Exam C (2008春)study manual ¥185 1.5kgGUO版Exam C (2009春)study manual ¥300 2.5kgDAR新版Exam C Equation Study List公式手册¥30Fap:指定教材,已经全部是最新版的,全套价格为¥900 (非最新版一套为¥600)Fundamentals of Private PensionsUnderstanding Actuarial Management:Enterprise Risk ManagementINVESTMENT SCIENCEIntroduction to Ratemaking&Loss Reserving Third EditionGroup Insurance 5th editionActuarial Aspects of Individual Life Insurance 2nd Edition。