
巴基斯坦进口清关所需要资料及税款计算公式
DDP贸易术语巴基斯坦清关,需要的清关文件如下:
1. Original Commercial Invoice 正本商业发票(SHIPPER提供)
2. Original Packing List 正本装箱单(SHIPPER提供)
3. Original Bill of Lading 正本提单(SHIPPER提供)
4. Certificate of Orgin 原产地证(SHIPPER提供)或是
5. Original Federal Trade Agreement issued by. Chinese Government
bodies. FTA,优惠制原产地证,如果出CO,就不用出FTA
6. Original Insurance Policy 正本保险单(SHIPPER提供)
7. Catalogue/Drawing (Option) 货物的说明(SHIPPER提供)可要可不要
8. Letter of credit / Agreement. (Proof of Payment.) 信用证或是付款证明
9. Contract between Shipper and Consignee 合同
10. Original Cargo Plan 正本货物计划(货代提供给国外清关代理)
11. National Tax Number (Consignee will provide) 税务登记证
12. Sale tax (Consignee will provide)
13.Tax exemption certificate 如果是免税的货,SHIPPER或Consignee要提海关的免税证明14. Consignee Letter Head 如果初次合作,收货人需要提供此证明给清关代理
DDP贸易术语,巴基斯坦进口关税计算公式:
Custom value= CIP Value+1% landed charges
Custom Duty= Custom value @ Custom duty Rate
Sales Tax= (Custom value+ Custom Duty) @ Sales Tax Rate
Income Tax= (Custom value+ Custom Duty) @ Income Tax Rate
Sindh Excise Tax= Custom Value @ Sindh Excise Tax Rate
Total duty and Tax:=Custom Duty+ Sales Tax+ Income Tax+ Sindh Excise Tax
DDP,清关产生的费用项目大致如下:
1.Custom Duty (巴基斯坦海关收取)
2.Sales Tax (巴基斯坦海关收取)
3.Income Tax(巴基斯坦海关收取)
4.Excise & Taxation Officer (巴基斯坦海关收取)
5.Wharfage (码头费)
6.Bill of Entry Charges (文件费)
7.Amendment Fees Paid to Customs (if have) 改单费(如果产生)
8.Devaninig Charges M/s. Cosco Saeed Karachi 拆箱费(如果产生)
9.T.H.C Charges Paid to M/s. Cosco Saeed 码头操作费
10.Registration Fees at Customs/KPT 如果港区,办理KPT费用
11.Customs Examination, Assessment Port Formalties & Completion 海关查验费
mission 国外货代给他们报关代理的佣金(如跟货代已谈清关费用,可拒付)
13.16% sales tax of commission国外货代给他们报关代理的佣金(如跟货代已谈清关费用,
可拒付)。
巴基斯坦税费简介

巴基斯坦税费简介工程项目在巴基斯坦涉及的主要税种简介章节2 –工程项目在巴基斯坦涉及的主要税种简介工程项目在巴基斯坦涉及的主要税种简介根据巴基斯坦当地的相关法律规定,外国企业在巴基斯坦境内开展EPC合同中规定的相关经营活动,必须要在当地建立商业实体。
根据实际需要,贵司可以考虑选择的商业实体形式有分公司和子公司(私人有限公司)两种。
一般情况下,外国企业在巴基斯坦设立子公司的形式或分公司的形式从事EPC工程项目涉及以下主要税种:般情况下外国企业在巴基斯坦设立子公司的形式或分公司的形式从事–企业所得税(Tax on Corporate Income)–利润汇回预提税(Withholding Tax on Profit Distribution)增值税(Value Added Tax)–(Value Added Tax)–个人所得税(Tax on Personal income)–社会保险(Social Security) (社会保险不属于税项,但作为雇主的一项成本,我们将其包含在税种简介中)–员工福利基金(Workers’ Welfare Fund)–其他税种(主要包括关税、联邦消费税、印花税等)工程项目在巴基斯坦涉及的主要税种简介章节2 –工程项目在巴基斯坦涉及的主要税种简介企业所得税在巴基斯坦从事商业经营活动的居民企业和非居民企业(在特定条件下)需要在巴基斯坦缴纳企业所得税收入的性质支付对象预提税税率(在特定条件下)需要在巴基斯坦缴纳企业所得税。
目前巴基斯坦有两种所得税征收制度:净利润制度(NIB)和最终税负制度(FTR)。
–一般而言,巴基斯坦所得税纳税人需要以净利润为基技术服务费和特许权使用费非居民企业15%执行合同取得的收入(包括施工、组装、安装等)居民/非居民企业6%产品销售居民企业 3.5%础计算应税所得并按照35%的税率缴纳所得税;–但是从事特定行业的纳税人需要根据最终税负制度缴纳所得税,其中居民企业(如外国企业当地投资设立的子公司)必须按照最终税负制度缴税,而非居民企股息收入(包括分公司向总公司的利润汇回)居民/非居民企业10%商品进口居民/非居民企业3% 至5%出业(如外国企业在巴基斯坦的分公司)可以选择按照此制度缴税;在最终税负制度下,纳税人需要在取得相关收入时缴纳预提税(由支付人扣缴),并作为所得税最终税负,而无需就相关收入再额外计算缴纳所得税,但相应的也不能对相关经营费用进行扣除。
进口关税计算公式

进口关税计算公式导言进口关税是国家对进口商品征收的一种税收形式。
它既可以作为保护国内产业的手段,也可以作为调节贸易平衡的工具。
进口关税的计算方法直接关系到企业和个人的进口成本,因此了解和掌握进口关税的计算公式对于进口贸易行业非常重要。
本文将介绍进口关税的基本概念和计算公式。
一、进口关税的基本概念进口关税是指国家根据贸易法规定,对进口商品征收的税费。
它主要包括关税税率和关税计算基数两个方面。
关税税率是对进口商品征收的税率,通常以百分比来表示。
关税计算基数是指进口商品的完税价格,即商品的成交价格加上海关处理费、保险费和运费等相关费用。
进口关税的计算公式一般为:进口关税=关税计算基数×关税税率二、关税计算公式的说明1. 关税计算基数的确定关税计算基数由进口商品的完税价格组成。
完税价格是指商品在境外出口国家的销售价格,需要加上一些相关费用。
这些相关费用包括海关处理费、保险费和运费等。
海关处理费是指处理进口商品所需的相关费用,包括检验、检疫、清关等。
保险费是进口商品在运输过程中所需的保险费用。
运费是指商品从出口国家到进口国家所需的运输费用。
这些费用的加入,可以更准确地反映出进口商品的真实成本。
2. 关税税率的确定关税税率是根据国家贸易政策和国际贸易协定等因素来确定的。
关税税率通常以百分比来表示,并根据不同的商品分类进行规定。
在世界贸易组织框架下,各国之间签订了多项贸易协定和自由贸易协定,这些协定对于关税税率的确定有一定的规定。
因此,在进口商品时,需要根据商品的分类和相关贸易协定来确定关税税率。
3. 进口关税的计算根据以上说明,可以将进口关税的计算公式简化为:进口关税=完税价格×关税税率。
当然,在实际操作中,可能还需要考虑其他因素,如加工贸易、特殊关税减免等。
这些因素将根据具体情况来确定具体的计算方法。
三、进口关税计算的实际应用进口关税的计算方法直接影响着进口商品的成本和价格,因此在进口贸易中有着极其重要的应用价值。
进出口税费征缴和计算—进出口关税的计算
完税价格=CFR价格/(1-保险费率)
一、进口关税的计算
计算实例:
• 2019年国内某公司向香港购进日本丰田牌轿车8辆,成交价格合计为FOB香港100 000.00 美元,实际支付运费4000美元,保险费600美元。已知汽车的规格为4座位,汽缸容量2 000cc,已知其适用的基准汇率为1美元=人民币6.74元,计算应征进口关税。
一、进口关税的计算
2.从量关税 从量关税是进口商品表示的数量、体积、重量等以计征关税的方法。计
税时以计量单位表示的货物的数量乘以每单位应纳税金额即可得出该货物的 关税税额。
计算公式: 从量税应征税额=货来自数量×单位税额一、进口关税的计算
计算实例:
• 2019年国内某公司从香港购进口柯达彩色胶卷40 000卷(宽度:35mm,长 度不超2m),规格为135/36,成交价格合计为CIF境内某口岸8.00港币/卷, 已知1港币=人民币0.86元,计算应征进口关税。
一、进口关税的计算
• 采用复合税率的有:录像机、放像机、摄像机、 非家用型摄录一体机、部分数字照相机等。
二、出口关税的计算
实行从价计征标准的出口关税税额的计算方法: 应征出口关税税额=完税价格×出口关税税率 完税价格=FOB÷(1+出口关税税率)
二、出口关税的计算
计算实例:
2019年某进出口公司从深圳出口硅铁(按重量计含硅量在55% 以上)90吨,每吨价格为110美元。已知其适用的基准汇率为1 美元=人民币6.74元,计算出口关税。
进出口关税的计算
一、进口关税的计算
1.从价关税 从价关税是以进口货物的完税价格作为计税依据,以应征税额
进口关税税款的计算
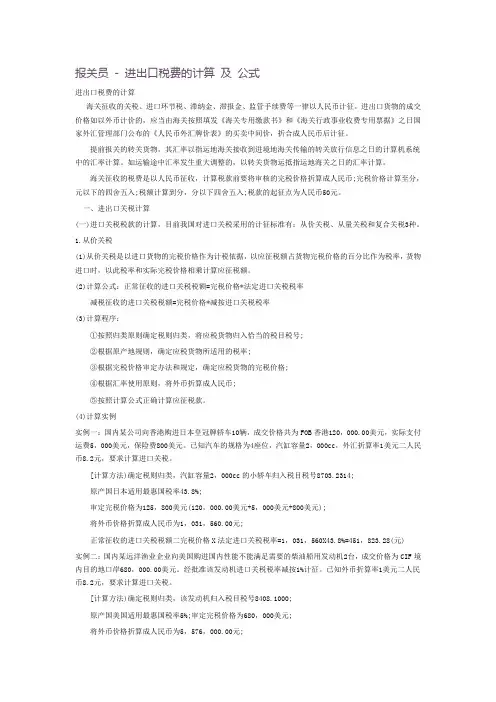
报关员- 进出口税费的计算及公式进出口税费的计算海关征收的关税、进口环节税、滞纳金、滞报金、监管手续费等一律以人民币计征。
进出口货物的成交价格如以外币计价的,应当由海关按照填发《海关专用缴款书》和《海关行政事业收费专用票据》之日国家外汇管理部门公布的《人民币外汇牌价表》的买卖中间价,折合成人民币后计征。
提前报关的转关货物,其汇率以指运地海关接收到进境地海关传输的转关放行信息之日的计算机系统中的汇率计算。
如运输途中汇率发生重大调整的,以转关货物运抵指运地海关之日的汇率计算。
海关征收的税费是以人民币征收,计算税款前要将审核的完税价格折算成人民币;完税价格计算至分,元以下的四舍五入;税额计算到分,分以下四舍五入;税款的起征点为人民币50元。
一、进出口关税计算(一)进口关税税款的计算,目前我国对进口关税采用的计征标准有:从价关税、从量关税和复合关税3种。
1.从价关税(1)从价关税是以进口货物的完税价格作为计税依据,以应征税额占货物完税价格的百分比作为税率,货物进口时,以此税率和实际完税价格相乘计算应征税额。
(2)计算公式:正常征收的进口关税税额=完税价格*法定进口关税税率减税征收的进口关税税额=完税价格*减按进口关税税率(3)计算程序:①按照归类原则确定税则归类,将应税货物归入恰当的税目税号;②根据原产地规则,确定应税货物所适用的税率;③根据完税价格审定办法和规定,确定应税货物的完税价格;④根据汇率使用原则,将外币折算成人民币;⑤按照计算公式正确计算应征税款。
(4)计算实例实例一:国内某公司向香港购进日本皇冠牌轿车10辆,成交价格共为FOB香港120,000.00美元,实际支付运费5,000美元,保险费800美元。
已知汽车的规格为4座位,汽缸容量2,000cc,外汇折算率1美元二人民币8.2元,要求计算进口关税。
[计算方法)确定税则归类,汽缸容量2,000cc的小轿车归入税目税号8703.2314;原产国日本适用最惠国税率43.8%;审定完税价格为125,800美元(120,000.00美元+5,000美元+800美元);将外币价格折算成人民币为1,031,560.00元;正常征收的进口关税税额二完税价格X法定进口关税税率=1,031,560X43.8%=451,823.28(元)实例二:国内某远洋渔业企业向美国购进国内性能不能满足需要的柴油船用发动机2台,成交价格为CIF境内目的地口岸680,000.00美元。
关税怎么计算

关税怎么计算现在我们的对外贸易还是很发达的,涉及进⼝和出⼝贸易的,这样的话就是需要申报缴纳关税的,⼀般分为进⼝和出⼝关税的,税率是不同的,分为⼏种情况的,下⾯就由店铺⼩编给⼤家讲解⼀下有关海关关税的计算⽅法等法规。
关税怎么计算计算关税的相关公式1.从价税,适⽤于:⼀般的(出)⼝货物计算公式:应纳税额=应税进(出)⼝货物数量*单位完税价格*适⽤税率2.从量税,适⽤于:进⼝啤酒、原油等计算公式:应纳税额=应税进⼝货物数量*关税单位税额3.复合税,适⽤于:进⼝⼴播⽤录录像机、⽅像机、摄像机等计算公式:应纳税额=应税进⼝货物数量*关税单位税额+应税进⼝货物数量*单位完税价格*适⽤税率4.滑准税,适⽤于:进⼝规定适⽤滑准税的商品计算公式:进⼝商品价格越⾼。
(⽐例)税率越低;税率与商品进⼝价格反⽅向变动。
海关监管货物说明海关监管货物是指所有进出境货物,包括海关监管时限内的进出⼝货物,过境货物、转运货物、通运货物,特定减免税货物,以及暂时进出⼝货物、保税货物和其他尚未办结海关⼿续的进出境货物。
(1)⾃向海关申报起到出境⽌的出⼝货物;(2)⾃进境起到办结海关⼿续⽌的进⼝货物;(3)⾃进境起到出境⽌的过境、转运和通运的货物按货物进出境的不同⽬的划分,可以分成五⼤类:1.⼀般进出⼝货物。
指从境外进⼝,办结海关⼿续直接进⼊国内⽣产或流通领域的进⼝货物,及按国内商品申报,办结出⼝⼿续到境外消费的出⼝货物。
2.保税货物。
指经海关批准未办理纳税⼿续⽽进境,在境内储存、加⼯、装配后复运出境的货物。
此类货物⼜分为保税加⼯货物和保税物流货物两类。
3.特定减免税货物。
指经海关依据有关法律准予免税进⼝的⽤于特定地区、特定企业、有特定⽤途的货物。
4.暂准进出境货物。
指经海关批准,凭担保进境或出境,在境内或境外使⽤后,原状复运出境或进境的货物。
5.其他进出境货物。
指由境外启运,通过中国境内继续运往境外的货物,以及其他尚未办结海关⼿续的进出境货物。
关税计算公式及举例分析
关税计算公式及举例分析关税是指进口商品进入一个国家时,根据相关法律规定,由进口商向该国政府支付的税费。
关税的计算是根据一定的公式进行的,下面将介绍关税计算的公式,并通过举例分析来说明关税的具体计算方法。
关税计算公式:关税 = 进口商品的完税价格×关税税率。
其中,进口商品的完税价格是指商品的成交价格加上运输、保险等费用,即进口商需要支付的总费用。
关税税率是由进口国家根据不同商品制定的税率,通常以百分比表示。
举例分析:假设某国家对进口汽车征收关税,关税税率为20%,某进口商从国外购买一辆汽车,成交价格为10000美元,运输、保险等费用为2000美元。
根据以上公式,可以计算出该汽车的关税费用:关税 = (10000 + 2000) × 20% = 12000 × 20% = 2400美元。
这意味着进口商需要向该国政府支付2400美元的关税费用,才能将汽车引入该国销售。
在实际情况中,不同国家对不同商品的关税税率和计算方法可能有所不同,有些国家还会根据进口商品的特定属性进行分类,并对不同分类的商品征收不同的关税税率。
因此,进口商在进行进口商品时需要了解目标国家的关税政策,并根据相关的关税计算公式进行计算,以便合理安排进口商品的成本和定价。
此外,关税的计算还可能受到一些特定因素的影响,例如贸易协定、关税配额等。
在一些国际贸易组织或双边贸易协定中,可能会规定一些特殊的关税优惠政策,例如降低关税税率、免除关税等,以促进贸易自由化和促进经济发展。
因此,进口商还需要考虑这些因素,并结合实际情况进行关税的计算和申报。
总之,关税是国际贸易中不可或缺的一环,其计算方法是根据一定的公式和相关政策进行的。
通过以上的公式和举例分析,我们可以更好地理解关税的计算方法,并在实际的进口贸易中进行合理的成本控制和风险管理。
希望本文能对读者有所帮助,谢谢阅读!。
巴基斯坦增值税额计算方法
销售税是联邦政府根据《销售税法案1990》针对货物(包括进口)和服务的销售供应征收的一种税。
*概念梳理进项税(Input Tax):进项税额是税号注册人对他所购买或取得的应税商品和劳务支付的税款。
销项税(Output Tax):销售或供应货物或服务时征收的销售税。
消费税的调整(增值税):以商品(含应税劳务)在流转过程中产生的增值额作为计税依据而征收的一种流转税。
公式:销项税-进项税:进项税额调整是指从销项税中扣除进项税额,达到纳税人应纳税额的净额。
由于销售税是一种增值税,在每一个增值阶段都要征收。
为避免双重征税,对进项税进行调整,计算出正确的政府应纳税额。
例:如果一个注册的人购买了成本为100卢比的商品,而他/她被收取15%(即为15卢比)的销售税(进项税),那么他的总购买价就会变成115卢比。
如果后来他/她以200卢比的价格销售货物,并收取15%(即30卢比)作为销项税,则他的总销售价格将变为230卢比。
此时他/她的应税款额即增值税为:30-15=15卢比。
* Sales Tax Records 销售税记录税号注册人须在经营过程中,用英文或乌尔都语对所有提供、购买或进口的商品和服务进行记录。
* Record of Sales 销售记录销售记录应注明提供的货物或服务的下列细节:description; 描述quantity; 数量value; 价值name and address of the customer; 客户名称和地址amount of tax charged 收取的税额文章内容摘自《Sales Tax Guide(Taxpayer's Facilitation Guide) Brochure 015 January,2008》,仅供参考。
各国进口所需清关文件和产地证(外贸篇)
各国进⼝所需清关⽂件和产地证(外贸篇)1、⼀般产地证(C/O),⼀般原产地证是证明货物原产于某⼀特定国家或地区,享受进⼝国正常关税(最惠国)待遇的证明⽂件,它的适⽤范围是:征收关税、贸易统计、歧视性数量限制、反倾销和反补贴、原产地标记、政府采购等⽅⾯。
任何国家都可以做CO。
全称:CERTIFICATE OF ORIGIN 。
2、FORM A普惠制原产地证明书,是具有法律效⼒的我国出⼝产品在给惠国税率基础上进⼀步减免进⼝关税的官⽅凭证。
世界给予我国优惠的国家有38个(也就是说,只有出⼝到这些国家才做F/A):欧盟27国(⽐利时、丹麦、英国、德国、法国、爱尔兰、意⼤利、卢森堡、荷兰、希腊、葡萄⽛、西班⽛、奥地利、芬兰、瑞典、波兰、捷克、斯洛伐克、拉脱维亚、爱沙尼亚、⽴陶宛、匈⽛利、马⽿他、塞浦路斯、斯洛⽂尼亚、保加利亚、罗马尼亚)、挪威、瑞⼠、⼟⽿其、俄罗斯、⽩俄罗斯、乌克兰、哈萨克斯坦、⽇本、加拿⼤、澳⼤利亚和新西兰。
全称:GENERALIZED SYSTEM OF PREFERENCES CERTIFICATEOFORIGIN 。
3、FORM E 是中国-东盟⾃贸区使⽤的优惠性原产地证书。
⽬前,我国对外签发FORM E证书的国家包括⽂莱、柬埔寨、印度尼西亚、⽼挝、马来西亚、缅甸、菲律宾、新加坡、泰国、越南10国。
FORM D 是东盟⾃贸区原产地证书。
(FORM D等于FORM E,⼀般国外喜欢叫FORM D) 。
4、中国—智利⾃由贸易区原产地证书(FORM F) 中华⼈民共和国政府和智利共和国政府⾃由贸易协定 ,单个中国-智利⾃贸区FORM F原产地证书!5、《〈中国与巴基斯坦⾃由贸易区〉优惠原产地证明书》(FORM P) 对巴基斯坦可以签发《〈中国与巴基斯坦⾃由贸易区〉优惠原产地证明书》,2006年1⽉1⽇起双⽅先期实施降税的3000多个税⽬产品,分别实施零关税和优惠关税.原产于中国的486个8位零关税税⽬产品的关税将在2年内分3次逐步下降,2008年1⽉1⽇全部降为`零,原产于中国的486个8位零关税税⽬产品实施优惠关税,平均优惠幅度为22%.给予关税优惠的商品其关税优惠幅度从1%到10%不等。
进出口税费的计算与缴纳实例
进出口税费的计算与缴纳实例1. 引言进出口业务在国际贸易中扮演着重要角色,但在进行进出口业务时,需要了解和计算相关的税费,以确保交易的合法性和利润。
本文将以进出口税费的计算与缴纳实例为主题,介绍进出口税费的计算方法和实际操作。
2. 进口税费的计算与缴纳2.1 进口税费的种类进口税费主要包括关税、增值税和消费税等。
关税是根据商品的类别和产地等因素确定的,增值税和消费税是根据商品的价值确定的。
进口税费的类型和税率根据国家和地区的政策而有所不同。
2.2 进口税费的计算公式进口税费的计算公式如下:总进口税费 = 关税 + 增值税 + 消费税其中,关税的计算公式为:关税 = 关税税率 × (进口商品的完税价格 + 运费 + 保险费)增值税的计算公式为:增值税 = (进口商品的完税价格 + 关税 + 运费 + 保险费) × 增值税税率消费税的计算公式为:消费税 = (进口商品的完税价格 + 关税 + 运费 + 保险费) × 消费税税率进口税费的缴纳通常由进口商负责。
进口商需要根据海关提供的进口税费计算结果,按规定的时间和方式缴纳相应的税款。
通常,进口商可选择自行办理进口税费的缴纳,或委托专业的报关公司代为办理。
3. 出口税费的计算与缴纳3.1 出口税费的种类出口税费主要包括关税和退税等。
关税是根据商品的类别和目的地等因素确定的,退税是根据商品的出口价值确定的。
3.2 出口税费的计算公式出口税费的计算公式如下:总出口税费 = 关税 - 退税出口税费的缴纳通常由出口商负责。
出口商需要根据海关提供的出口税费计算结果,按规定的时间和方式缴纳相应的税款。
通常,出口商可选择自行办理出口税费的缴纳,或委托专业的报关公司代为办理。
4. 进出口税费的实际操作4.1 进口税费的实际操作进口商在进行进口业务时,需要按照以下步骤进行进口税费的计算和缴纳:1.获取进口商品的完税价格,即商品的成交价格加上运费和保险费。
巴基斯坦关税2
Chapter 98(SERVICES)Heading Description FED98.019801.1000 9801.2000 9801.3000 9801.4000 9801.5000 9801.60009801.7000 9801.9000Services provided or rendered by hotels, restaurants, marriage halls, lawns, clubsand caterers.Services provided or rendered by hotelsServices provided or rendered by restaurantsServices provided or rendered by marriage halls and lawnsServices provided or rendered by clubsServices provided or rendered by caterers, suppliers of food and drinksAncillary services provided or rendered by hotels, restaurants, marriage halls, lawns,caterersServices provided or rendered by messes and hostelsOther16% of the charges98.02 9802.1000 9802.2000 9802.3000 9802.4000 9802.5000 9802.9000Advertisements.Advertisement on T.V.Advertisement on radioAdvertisement on closed circuit T.V.Advertisement in newspapers and periodicalsAdvertisement on cable T.V networkOther16% of the charges98.03 9803.1000 9803.1100 9803.2000 9803.2100 9803.9000Facilities for travel.Travel by air of passengers within the territorial jurisdiction of Pakistan.Travel by air of passengers embarking on international journey from PakistanDomestic travel by trainInternational travel by trainOther16% of the charges98.04 9804.1000 9804.2000 9804.9000Services provided or rendered for inland carriage of goods.Carriage of goods by airCarriage of goods by trainOther16% of the charges98.05 9805.1000 9805.2000 9805.2100 9805.3000 9805.4000 9805.5000 9805.5100 9805.6000 9805.7000 9805.8000 9805.9000 9805.9100 9805.9200 9805.9090Services provided or rendered by persons authorized to transact business on behalfof others.Shipping agentsStevedoresShip management serviceFreight forwarding agentsCustoms agentsTravel agentsTour operatorsRecruiting agentsAdvertising agentsShip chandlersShare transfer agentSponsorship servicesBusiness support servicesOther16% of the charges9807.0000 Services provided or rendered by property developers and promoters. 16% of the charges 9808.0000 Courierservices. 16% of the charges9809.0000 Services provided or rendered by persons engaged in contractual execution of workor furnishing supplies.16% of the charges9810.0000 Services provided or rendered for personal care by beauty parlours/clinics,slimming clinics and others.16% of the charges 9811.0000 Services provided or rendered by laundries, dry cleaners. 16% of the chargesHeading Description FED98.12 9812.1000 9812.1100 9812.1200 9812.1210 9812.1220 9812.1300 9812.1400 9812.1500 9812.1600 9812.1700 9812.1710 9812.1720 9812.1910 9812.1920 9812.1930 9812.1940 9812.1950Telecommunication services.Telephone servicesFixed line voice telephone serviceWireless telephoneCellular telephoneWireless Local Loop telephoneVideo telephonePayphone cardsPre-paid calling cardsVoice mail serviceMessaging serviceShort Message service (SMS)Multimedia message service (MMS)Shifting of telephone connectionInstallation of telephone extensionProvision of telephone extensionChanging of telephone connectionConversion of NWD connection to non NWD or vice versa16% of the charges9812.1960 9812.1970 9812.1990 9812.2000 9812.2100 9812.2200 9812.2300 9812.2400 9812.2500 9812.2900 9812.3000 9812.4000 9812.5000 9812.5010 9812.5090 9812.6000 9812.6100 9812.6110 9812.6120 9812.6121 9812.6122 9812.6123 9812.6124 9812.6125 9812.6129Cost of telephone setRestoration of telephone connection OthersBandwidth servicesCopper line basedFibre-optic basedCo-axial cable basedMicrowave basedSatellite basedOthersTelegraphTelexTelefaxStore and forward fax servicesOthersInternet servicesInternet services including e-mail services Dial-up internet servicesBroadband services for DSL connection Copper line basedFibre-optic basedCo-axial cable basedWireless basedSatellite basedOthers9812.6130 9812.6140 9812.6190 9812.6200 9812.6210 9812.6220 9812.6230 9812.6240 9812.6250 9812.6290 9812.6300 9812.6310 9812.6320 9812.6390 9812.9000 9812.9100 9812.9200 9812.9300 9812.9400 9812.9410 9812.9490 9812.9500 9812.9090Internet/e-mail/Data/SMS/MMS services on WLL networksInternet/e-mail/Data/SMS/MMS services on cellular mobile networks OthersData Communication Network services (DCNS)Copper Line basedCo-axial cable basedFibre-optic basedWireless/Radio basedSatellite basedOthersValue added data servicesVirtual private Network service (VPN)Digital Signature serviceOthersAudiotext servicesTeletext servicesTrunk radio servicesPaging servicesVoice paging servicesRadio paging servicesVehicle tracking services.Burglar alarm services.OthersHeading Description FED98.139813.1000 9813.1100 9813.1200 9813.1300 9813.1400 9813.1500 9813.1600 9813.2000 9813.3000 9813.3010 9813.3020 9813.3030 9813.3090 9813.3900 9813.4000 9813.4100 9813.4200 9813.4300 9813.4400 9813.4500 9813.4600 Services provided or rendered by banking companies, insurance companies,cooperative financing societies, modarabas, musharikas, leasing companies,foreign exchange dealers, non-banking financial institutions and other personsdealing in any such services.Services provided or rendered in respect of insurance to a policy holder by an insurer,including a reinsurer.Goods insuranceFire insuranceTheft insuranceMarine insuranceLife insuranceOther insuranceServices provided or rendered in respect of advances and loansServices provided or rendered in respect of leasing.Financial leasingCommodity or equipment leasingHire-purchase leasingOtherServices provided or rendered in respect of musharika financingServices provided or rendered by banking companies in relation to:GuaranteeBrokerageLetter of creditIssuance of pay order and demand draftBill of exchangeTransfer of money including telegraphic transfer, mail transfer and electronic transfer16% of the charges9813.4700 9813.4800 9813.4900 9813.4910 9813.5000 9813.6000 9813.7000 9813.8000 9813.8100 9813.9000 Bank guaranteeBill discounting commissionSafe deposit lockersSafe vaultsIssuance, processing and operation of credit and debit cardsCommission and brokerage of foreign exchange dealings.Automated Teller Machine operations, maintenance and management.Service provided as banker to an issueOtherService provided or rendered by a foreign exchange dealer or exchange company or money changer98.14 9814.1000 9814.2000 9814.3000 9814.4000 9814.9000Services provided or rendered by architects, town planners, contractors, propertydevelopers or promoters, interior decorators.Architects or town plannersContractors of building (including water supply, gas supply and sanitary works), roads andbridges, electrical and mechanical works (including air conditioning), horticultural works,multi-discipline works (including turn-key projects) and similar other worksProperty developers or promotersLandscape designersOther16% of the charges98.15 9815.1000 9815.2000 9815.3000 9815.4000 9815.5000 9815.6000 9815.9000Services provided or rendered by professionals and consultants etc.Medical practitioners and consultantsLegal practitioners and consultantsAccountants and auditorsManagement consultantsTechnical, scientific, engineering consultantsSoftware or IT based system development consultantsOther consultants16% of the charges9816.0000 Services provided or rendered by pathological laboratories. 16% of the chargesHeading Description FED98.17 9817.1000 9817.2000 9817.3000 9817.4000 9817.9000Services provided or rendered by medical diagnostic laboratories including X-Rays,CT Scan, M.R. Imaging etc.Scientific laboratoriesMechanical laboratoriesChemical laboratoriesElectrical or electronic laboratoriesOther such laboratories16% of the charges98.18 9818.1000 9818.2000 9818.3000 9818.9000Services provided or rendered by specialized agencies.Security agencyCredit rating agencyMarket research agencyOther such agencies16% of the charges98.19 9819.1000 9819.1100 9819.1200 9819.1300 9819.1400 9819.2000 9819.3000 9819.4000 9819.5000 9819.6000 9819.7000 9819.8000 9819.9000 9819.9100 9819.9200 9819.9300 9819.9400 9819.9500 9819.9090 Services provided or rendered by specified persons or businesses.StockbrokersUnder writersIndentersCommission agentsPackersMoney exchangerRent a carPrize bond dealersSurveyorsDesignersOutdoor photographerArt painterCable TV operatorsAuctioneersPublic relations servicesManagement consultantsTechnical testing and analysis serviceService provided by a registrar to an issueOthers16% of the charges98.20 9820.1000 9820.2000 9820.3000 9820.4000 9820.9000Services provided or rendered by specialized workshops or undertakings.Auto-workshopsWorkshops for industrial machinery construction and earth-moving machinery or otherspecial purpose machinery etc.Workshops for electric or electronic equipments or appliances etc. including computerhardwareCar washing or similar service stations.Other workshops16% of the charges98.21 9821.1000 9821.2000 9821.3000 9821.4000 9821.5000 9821.9000Services provided or rendered in specified fields.Healthcare centres, gyms or physical fitness centres etc.Indoor sports and games centresBaby care centresBody massage centresPedicure centresSimilar other centers16% of the charges98.22 9822.1000 9822.2000 9822.3000 9822.4000 9822.9000Services provided or rendered for specified purposes.Fumigation servicesMaintenance or cleaning servicesJanitorial servicesDredging or desilting servicesOther similar services16% of the charges9823.0000 Franchiseservices 16% of the charges 9824.0000 Construction services 16% of the chargesChapter 99SPECIAL CLASSIFICATION PROVISIONSNotes.1. The provisions of this Chapter are not subject to the rule of specificity in General Interpretative Rule 3(a) and have over-riding effect onclassifications made under Chapters 1 to 97.2. Classification in Chapter 99 is subject to,-(i) determination of eight digit classification under a tariff item in chapter 1 to 97;(ii) determination of four digit classification under chapter 99 and fulfillment of conditions mentioned in the Chapter, Sub-chapters, Headings; and(iii) such other conditions, limitations and restrictions as Federal Board of Revenue or the Federal Government may impose from time to time.3. In case of sale or disposal of goods in violation of the prescribed condition, limitation or restriction, duty shall be recovered at the rates specifiedin Chapter 1 to 97 without prejudice to any other action required under the Customs Act, 1969.SUB-CHAPTER -IIMPORTS BY PRIVILEGED PERSONS, ORGANIZATIONS, AND OTHER DIGNITARIES.Note.1. For the purpose of sub-chapter 1, the following conditions shall apply:(i) The importer shall make a declaration on the bill of entry for exemption claimed.(ii) Any article other than a motor vehicle, sold or otherwise disposed of before the expiration of three years from its importation shall be liable topayment of customs duties, which would have been leviable at the time of importation.(iii) A motor vehicle shall not be sold or otherwise disposed of in Pakistan without payment of customs duties, which would have been leviable atthe time of importation as provided under the procedure prescribed therefor by the Board.PCT CODE Description CD (%)(1) (2)(3) 9901 Goods imported by various agencies of the United Nations under the United Nations (PrivilegesandImmunities) Act,1948(XX of 1948), as certified by the Ministry of Foreign Affairs, Government ofPakistan.9902 Goods imported by Diplomats/Embassies/ Consulates under the Diplomatic and Consular PrivilegesAct, 1972 (Act IX of 1972) as certified by the Ministry of Foreign Affairs, Government of Pakistan.9903 Goods imported by privileged personnel/organizations under grant-in-aid agreements signed by theEconomic Affairs Division (EAD) Government of Pakistan, duly concurred by the Federal Board ofRevenue.9904 Vehicles in CKD condition, imported by recognized local manufacturer for supply to diplomat,diplomatic mission, privileged person (as per model rules) and organizations etc eligible to import dutyfree vehicles subject to the procedure laid down by the Board.9905 Household articles and personal effects including vehicles and goods for donation to projectsestablished in Pakistan, imported by the rulers and following dignitaries of UAE and Qatar subject tothe conditions mentioned below and the conditions mentioned in sub-chapter notes:-Dignitaries of UAE1. H.H.Sheikh Khalifa Bin Zayed Al-Nahyan, Crown Prince of Abu Dhabi and Deputy SupremeCommander of UAE Armed Force.2. H.E.Sheikh Suroor Bin Mohammad Al-Nahyan, Chamberlain of the Presidential Court, Abu Dhabi.3. H.E.Sheikh Mohammad Bin Khalid Al-Nahyan, Member of the ruling family of Abu Dhabi.4. H.E.Sheikh Mubarak Bin Mohammad Al- Nahyan, Member of the ruling family of Abu Dhabi.5. H.E.Sheikh Sultan Bin Hamdan Al-Nahyan, Member of the ruling family of Abu Dhabi.6. H.H.General Sheikh Mohammad Bin Zayed Al-Nahyan Chief of Staff of UAE Armed Forces.7. H.E.Sheikh Tahnoum Bin Mohammad Al-Nahyan, Member of the ruling family of Abu Dhabi.8. H.E. Sheikh Rashid Bin Khalifa Al-Makhtoum, Member of the ruling family of Dubai.9. H.H.Sheikh Sultan Bin Zayed Al-Nahyan, Deputy Prime Minister of the UAE.10. H.H.Sheikh Hamdan Bin Zayed Al-Nahyan, Minister of State for Foreign Affairs, Government ofthe United Arab Emirates.11. H.H. Sheikh Muhammad Bin Rashid Al Maktoum, Vice President, Prime Minister, Minister ofDefence and Ruler of Dubai.12. H.H. Sheikh Hamdan Bin Rashid Al-Maktoum, Deputy Ruler of Dubai, Minister of Finance &Industry, UAE.13. H.H. Maj. Gen. Sheikh Ahmed Bin Rashid Al-Maktoum, Member of the Ruling Family of Dubai &Head of Central Military Command.14 H.H. Maj. Gen. Sheikh Nahyan Bin Zayed, Member of the Ruling Family of Abu Dhabi andCommander of Royal Guard.PCT CODE Description CD (%)(1) (2) (3) Dignitaries of Qatar: 1. H.E. Shaikh Faisal Bin Thani Bin Jassim Al-Thani 2. H.E. Shaikh Ali Bin Abdullah Bin Thani Al-Thani.3. H.E. Shaikh Abdullah Bin Jassim Bin Fahad Al-Thani.4. H.E. Shaikh Mubarak Bin Khalifa Bin Saud Al-Thani5. H.E. Shaikh Abdullah Bin Ali Bin Abdullah Al-Thani.6. H.E. Shaikh Abdul Rahman Bin Nasser Bin Jassim Al-Thani7. H.E.Shaikh Ali Bin Ahmed Al-Ahmed Al-Thani8. H.E.Shaikh Faisal Bin Jassim Bin Faisal Al-Thani(i) A complete list of all vehicles showing name of the owner, details of imports and present custodian etc shall be provided by UAE/Qatar Ambassador. This information shall be provided by 31-7-2004 showing comprehensive positions as on 31-12-2003.(ii) The list shall be updated every six months i.e. on 31st July and 31st January to show status as on 1st July & 1st January.(iii) UAE/Qatar Rulers must make and disclose alternate arrangements for maintenance of their fleet by their employees and not by any Pakistani posing as their agents or authorized representatives. (iv) UAE/Qatar Embassy should undertake that no Pakistani will be allowed use of their duty free vehicles and that they will abide by the true spirit in which this concession is available to the UAE/Qatar Rulers.(v) In order to avail the duty concession, an exemption certificate to this effect shall be issued by the Ministry of Foreign Affairs, Government of Pakistan9906 (i) Goods imported under the President’s Salary, Allowances and Privileges Act, 1975(Act LVIII of 1975).(ii) Goods imported under the Prime Minister’s Salary, Allowances and Privileges Order,1975 (ActLIX of 1975).(iii) Goods imported under the Governor’s Salary, Allowances and Privileges, Order,1975(President’s Order No.5 of 1975).(iv) Goods imported under the Acting Governer’s (Allowance and Privileges) Order,1978(President’s Order No.19 of 1978).(v) Furniture, and spare parts in respect of official cars, river craft or air craft imported orpurchased out of bond for the President, Prime Minister, Governor or Acting Governor.SUB-CHAPTER–IIIMPORT OF RELIEF GOODS, GIFTS, SAMPLESPCT CODE Description CD (%)(1) (2) (3) 9907 Goods imported for the President’s Fund for Afghan Refugees. Bonafide relief goods donated for the Afghan Refugees through the Chief Commissioner or the Provincial Commissioner of the Afghan Refugees subject to a certificate from the Chief Commissioner for the Afghan Refugees that the imported goods or equipment are menat for free distribution amongst Afghan Refugees or for relief wrok and that the same would not be sold or otherwise disposed of without the prior approval of the Federal Board of Revenue9908 Goods received as gift by Pakistani organizations from Church World Services or the Catholic Relief Services as are certified by the Ministry of Health, that these imports are made under agreements signed by the Government of Pakistan with the Church World Service and with the Catholic Relief Service9909 Articles, value of which does not exceed Rs.20,000/- per parcel, if imported through post or courier service as unsolicited gift parcel.9910 Samples of no commercial value imported by manufacturers subject to the following conditions:- a) raw materials and products of such dimensions/ specifications that are useless except for purposesof demonstration;b) articles of non-precious materials affixed to cards or put up as samples in the manner usual in thetrade provided that there is not more than one of each size or kind;c) raw materials and products, and articles thereof rendered useless, except for purposes ofdemonstration, by slashing, perforation, indelible marking or by any other effective method;d) products which cannot be put up as samples of no commercial value in accordance with clauses (a)to (c) and which consist of:(ot (2) oods of an individual value not exceeding US$ 100 or its equivalent in any1) non-consumable goods of an individual value not exceeding US$ 100 or its equivalent in anyher currency and provided there is not more than one sample of each kind or quality; and consumable g currency even if they consist wholly or partly of samples of the same kind or quality, provided the quantity and the manner in which they are put up preclude their being used otherwise than as samples9911 (i) R ted for free distribution among the victims of natural disaster or other catastrophe, as are certified by the authorized officer of Federal/Provincial Governmentelief goods dona (ii) Plant, machinery and equipment imported by way of donation for installation in the earthquakehit districts as certified by ERRA/National Disaster Management Authority.otepurpose of sub-chapter III the expression:(i) “Charitable Institution” and “Charitable non-profit m ans an institution approved for the purpose of section 2(36C) ofthe Income Tax Ordi (ii) “Gifts or Donations” include goods other y the donorsresiding abroad. However, ambulances received as gift or donati road shall be eligible for the benefit provided that the same are imported as per Serial No. 116 of Customs General Order No.12 of 2002, dated the 15th June, 2002; andPCT CODE CD (%) SUB-CHAPTER IIIIMPORTS BY CHARITABLE, EDUCATIONAL, SCIENTIFIC INSTITUTIONS AND HOSPITALS.N For the aking institution” me nance, 2001;than v of the First Schedule to the said Act, donated b ehicles of chapter 87on from ab (iii) “Competent Authority” means:(i) in case of educational and research institutions falling in the jurisdiction of the Federal Government, the Ministry of Education orMinistry of Science & Technology or any other relevant Ministry of the Federal Government;(ii) in case of an institution falling within the jurisdiction of a Provincial Government, the Director of Education or Technical Educationor PublicInstitution or any other relevant authority of the Provincial Government; andnized by the University Grants Commission, the Registrar of the University.(iii) in case of a university recogDescription(1) (2) (3)9912 Fo imported by Abdul Sattar Edhi Foundation and Bilques Edhi Foundation, subject tofu oor Edhi at the time of case may be, by Bilquis Edhi Foundation. (In the case of goods at serial No. 14,15,16, the words "Edhi Foundation" or "as the case may be , Bilquis on "are inscribed at some prominent place on the body of each vehicle, aeroplane or helicopter); .04)ze, bandages and similar articles (for example, er, poultices) impregnated or coated stances.(30.05) ods (30.06) 09)n apparatus (85.15) al or surgical usses; splints and other fracturey, hearing aids and other appliances which are worn or r a defect or disability(90.21)al uses, control panels and desks,(90.22).0 llowing goods rnishing of a certificate by Maulana Abdul Sattar Edhi son of Haji Abdul Shak import of each consignment to the effect that the goods are meant for use by Edi Foundation or, as the Edhi Foundati 1. Butter oil(04.05) 2. Rice(10.06) 3. Grains(10.07)4. Cooking oil(Chapter 15)5. Vitamins(29.36)6. Hormones.(29.37)7. Pencillin (29.41) s(308. Medicament9. Waddings, gua dressings, adhesive plast ical sub with pharmaceut 10. Pharmaceutical go .11. Worn clothing(6312. Wireless transmissio 13. Wireless reception apparatus.(85.27) 14. Ambulances.(87.03)15. Mobile radiological units(87.05)16. Helicopters, aeroplanes (88.02)d aeroplanes (Respective headings) 17. Parts of helicopters an 18. Instruments and appliances used in medic sciences.(90.18)s, including crutches, surgical belts and tr 19. Orthopaedic appliance appliances, artificial parts of the bod carried, or implanted in the body, to compensate fo 20.Apparatus based on the use of X-rays for medical or surgic like screens, examination or treatment tables, chairs and the 9913 eived by a charitable non-profit making hospital or institution, solely for the (i) (ii) o the respective Collector ofGifts or donations rec purpose of advancing the declared objectives of such hospital or institution, subject to the following conditions, namely:-no condition is attached to the gift or donation by the donor and the receiving institution or hospitalis at liberty to use the same in accordance with its declared objectives; andthe receiving institution or hospital furnishes an undertaking in writing t Customs to the effect that such gifts or donations will not be sold, utilized or disposed of otherwise than for the purpose for which the same have been received and binds itself to pay the leviable duties in the event of a breach of the undertaking.9914 Equipment, apparatus, reagents, disposables and spares, imported by: -(i) charitable non profit making institutions operating hospitals of fifty beds or more; and(ii) hospitals run by the Federal Government or a Provincial Government,-Subject to the following conditions: -(a) the importing institution or hospital furnishes an undertaking in writing to the respective Collector ofCustoms to the effect that such equipment, apparatus, reagents, disposable and spares will not besold, utilized or disposed of otherwise than for the purpose for which the same have been importedand binds itself to pay the leviable duty and sales tax in the event of breach of the undertaking.(b) the importing institution operating a hospital of fifty beds or more shall furnish a proof thereof to thesatisfaction of the respective Collector of Customs.9915 Goods imported by or donated to non profit making educational and research institutions subject to thefollowing conditions:(i) the imported goods have an educational and scientific character;(ii) the importing or receiving institutions are recognized, aided or run by the Federal Government ora Provincial Government, a City Government or a District Government;(iii) the importing or receiving institution shall produce a certificate from the competent authority that –(a) goods of equivalent educational and scientific value are not produced in Pakistan; and(b) the imported goods will be used exclusively under the control and responsibility of the importing orreceiving institution.SUB-CHAPTER-IVIMPORT OF REPLACEMENT GOODSPCT CODE Description CD (%)(1) (2) (3) 9916 Goods supplied free of cost as replacement of identical goods previously imported including goodsimported within warranty period not exceeding one year or such extended period as allowed by theCollector of Customs, subject to the following conditions:-(i)the goods were imported in pursuance of firm contract of sale, and not under a contract of sale orreturn, on approval; on consignment for sale or on similar terms;(ii) the goods at the time of importation were not in accordance with the terms of contract in respect oftheir description, quality, state or condition or had been damaged or defected;(iii) the goods were not used except in circumstances in which limited use was indispensable to revealany inherent defect in the imported goods or to establish that they do not conform to the conditions ofthe contract;(iv) if the goods are returned abroad, they are returned to the supplier and if they are not returned,they are deposited with customs for further disposal.SUB-CHAPTER-VIMPORTS MADE BY THE UNITS LOCATED IN EXPORTS PROCESSING ZONES (EPZ)PCT CODE Description CD (%)(1) (2) (3) 9917 Goods imported into and exported (except to tariff area of Pakistan) from the Export Processing Zonesestablished under the Export Processing Zone Authority Ordinance, 1980 (IV of 1980) and anyenactment relating to Gwadar Special Economic Zone, subject to such conditions, limitations andrestrictions as the Federal Board of Revenue may impose from time to time.SUB-CHAPTER-VITEMPORARY IMPORT OR EXPORTPCT CODE Description CD (%)(1) (2) (3) 9918 Goods not produced or manufactured in Pakistan which are re-imported by industrial concerns afterhaving been exported and have not undergone any process outside Pakistan since their exportation.In case the goods have undergone any alterations, renovations, addition or repairs prior to their re-import into Pakistan, the cost incurred on such alterations, renovations, additions or repairs (excludingthe element of freight and other incidentals) shall be liable to duty as leviable under its respective PCTheading determined at the time of original import provided the machinery was exported under acontract of alteration, renovation, adddition or repairs and that the supplier and the receiver as well asthe make, model, weight and other specifications remain the same as were at the time of the originalimport of the goods.9919 Goods mentioned below, imported temporarily for a period not exceeding 6 months into Pakistan witha view to subsequent exportation, subject to furnishing of bank guarantee or other security/guaranteeas determined by Federal Board of Revenue equivalent to customs duty chargeable at the ratesspecified in Chapter 1 to 97 of the lst Schedule to the Act for such goods and other taxes leviablethereon.1. Packing material used or required to be used as external or internal covering of goods, or asholders of goods, or as holders on which goods rolled, wound or attached provided such material donot change their original shape or form. Packing material if imported filled, it may be re-exportedempty, and if imported empty it may be re-exported filled.2. Machinery and equipment for repair imported by manufacturer or authorized agents based inPakistan, representing foreign manufacturers duly registered with the Sales Tax Authorities, having inhouse facility for repair, Refurbishment or value addition of machinery.3. Professional equipment imported by scientists, IT experts, technicians, doctors, engineers, etc.either imported in their own name or in the name of the company in Pakistan for which these areimported.4. Tubes or cops of metal plastic or other durable material which are imported wrapped with yarn.5. Goods imported for demonstration , display, test or trial purposes.6. Dry fruits imported from Afghanistan.9920 Goods mentioned below, imported temporarily into Pakistan with a view to subsequent exportation,subject to furnishing of undertaking/bond by the importers as well as their sponsoring Ministry/Department/ Embassy:1. Excavation equipment and consumable stores imported by a foreign archaeological mission towhom a license for archaeological excavation has been granted by the Federal Government or aProvincial Government.2. Scientific and educational equipment imported for Scientific, educational or cultural seminars inPakistan on the recommendation of the concerned Ministry.3. Goods imported for display at international or single country exhibition organized by foreignmissions or imported by or through the Ministry of Commerce or the Ministry of Foreign Affairs.4. Machinery imported by the representatives of foreign commercial firms for demonstration purposesimported by or through the Ministry of Commerce or the Ministry of Foreign Affairs.5. Equipment and materials imported by foreign nationals such as journalists, press photographers,members of television teams, broadcasting units and film companies subject to endorsement on theirpassports. The duties shall be charged if such importer fails to prove their re-export at the time ofdeparture.6. Equipment, materials and special food stuff imported by mountaineering expeditions. In case theequipment and material is not exported the expeditions may donate such equipment and produce acertificate from the Secretary of that club to the effect that the equipment and material so imported hasbeen donated by that expedition to that club. Special food stuff can however, be consumed by them.9921 Container for transportation of cargo (PCT No.86.09) if imported by the shipping companies for useon board the ships and for transportation of cargo to and from inland container depots or containerfreight stations subject to the furnishing of indemnity bond by the shipping lines, equal to the amountof duty and taxes to the respective Collector of Customs. The indemnity bond is to be discharged onreceipt of proof of export of the containers.9922 Ship spares, stores and equipment imported for use in ships registered in Pakistan under theMerchant Shipping Act, 1923 (XXI of 1923) subject to the condition that the importer satisfies therespective Collector of Customs that the items imported would be used by such vessels.SUB-CHAPTER-VIIMISCELLANEOUSPCT CODE Description CD (%)(3)(1) (2)9923 Currency Notes, unused stamps 09924 Eyecornea 0machines, hemodialyzers, A.V. fistula needles, hemodialysis fluids &hemodialysiskidneys,9925 Artificialpowder, blood tubing tines for dialysis, reverse osmosis plants for dialysis, double lumen catheter fordialysis, catheters for renal failure patients, peritoneal dialysis solution and cardiac catheters.9926 Machinery and equipment, not manufactured locally, namely navigational equipment, fish finders,storage and handling equipment, if imported by fish farming or catching stage operators, who willenjoy the status of indirect exporters.9927 Pharmaceutical raw materials if imported for manufacture of contraceptives in accordance with theinput out put ratios determined by the Directorate of Input Output Co-efficient Organization.Contraceptives and accessories thereof.9928 Omitted.。