
外文翻译--中国企业跨国并购绩效的决定因素
译文:中国企业跨国并购绩效的决定因素摘要:采用了独特的数据上设置的跨境合并和收购活动在中国的证券交易所上市的公众公司,我们收购前的性能和国有股比例对收购公司的表现产生积极的影响。
关键词:跨国兼并和收购,中国企业,国际化1.介绍在过去的30年里,中国经历了快速的经济增长。
在此期间,大量的中国企业已经成长起来和具备竞争力,有一些甚至已经涉足海外投资,以寻找新的增长来源。
国际化扩张的方式之一就是收购现有企业,在国外,所谓的跨国兼并和收购(M&A)。
虽然这个数字是低,规模小的,但最近比过去的趋势明显加快。
这种现象值得密切关注,以便更好地了解在这个问题上。
跨国兼并和收购是指一个企业购买在国外的另一家公司的股份或资产的行动。
显然,跨国兼并和收购是在两个或两个以上国家的公司的控制权之间的交易。
虽然跨国并购的目标常常被说成是为股东创造价值的收购公司,结果相距较远的规定的目标。
系统研究表明,有相当数量的跨国兼并和收购以失败而告终。
除了在母国和东道国的市场环境之间的差异,收购公司的竞争力和比较优势被认为是更重要的。
这些优势包括公司治理,高层管理人员的长期竞争力,学习能力,以及其他。
因此,有必要看一看公司的特定因素影响的性能,跨境并购本研究的主要目的是确定的因素,影响结果的跨国兼并和收购中国公司,特别是在最近几年收购公司的经济表现。
近年来,中国企业的跨国兼并和收购的规模稳步上升。
根据联合国贸易与发展会议,中国企业的跨国兼并和收购总额为8.139亿美元,这个时间是1988年至2003年,其中大部分是1997年后发生。
虽然平均金额每年只有2.16亿美元,1988年和2003年间,在2003年,就达到了1.647亿美元的水平。
有一些广为人知的案例:上海电气集团在2002年购买了日本印刷机制造商,TCL收购德国施耐德在2003年和2004年,联想收购IBM PC业务的。
所有这些情况表明,中国企业的跨国兼并和收购已经进入了一个时代。
收购公司的经济表现的不同结果这样的公司的行动。
一些差异可能涉及到的国际化扩张的动机。
例如,有些公司这样做,因为在国内市场的竞争压力,而寻求资源,如原材料和技术,大概有几个甚至鼓励政府的政策措施。
尽管他们的动机的不同,许多公司因此增加了困难,在跨国并购的整合风险,并没有一个明确的概念成功因素导致性能上的差别。
因此,它必须有一个很好的理解中国和国际的关系,中国企业海外并购和决定因素之间的关系。
虽然这个问题是很重要的,许多严肃的学术研究中是很难找到的。
通过系统搜索的网站,其中列出了所有在中国的学术期刊上发表给我们接近千条跨国并购的中国国家知识基础设施大多数仅仅是现有的理论,说明目前的情况下,或简单的个案研究的评论。
我们的研究试图分析系统的经济性能,近年来,中国企业的跨国并购世界儿童之友协会的决定因素。
除了促进跨境并购的文献,我们也希望研究结果可以提供有益的指导对外直接投资的中国企业中所持的信念。
跨国并购是不是新的。
本文拟作出贡献是解释企业层面的海外并购,中国企业的因素和表现。
由于跨国并购表现受多种因素影响,我们采用了多种理论观点,特别是组织学习的观点与代理理论。
作为我们讨论的早期,我们还发现一个发达的数据库的跨境中号和一个,因此,我们开发我们自己的一个数据库覆盖165中号和一个情况下,通过搜索,通过各种数据源,包括公司网站,年度报告,报纸上,并在互联网。
本文的组织如下。
在第2条中的跨境并购活动的中国企业的特点进行了讨论。
经过短暂的文献回顾,一些假设的基础上的理论观点。
第4节讨论的方法和结果报告的结论性意见之前在第5。
2.跨境并购中国公司的特点跨国并购的中国企业开始在20世纪80年代,位于美国,加拿大和香港的大部分目标公司。
该公司涉及的基本上是大型国有企业,如中信,中化集团,首都钢铁,中国的资源。
例如,北京首都钢铁集团购买的美国工程公司MASTA的70%的股份,于1988年7月为US $340百万。
在20世纪90年代,越来越多的中国公司开始从事海外并购。
除了国有企业,私营和集体企业还联合游戏。
进入21世纪后,中国企业在跨国兼并和收购,几个大的情况下发生,如购买由上海汽车工业总公司和韩国双龙汽车公司汽车公司收购IBM的PC业务变得更具侵略性联想。
传闻观测结果显示几个趋势:1)量和交易金额的增加随着时间的推移。
图0.1显示了中国企业的跨国兼并和收购所涉及的金额。
多年来虽然涉及的金额有所不同,但趋势是往上走。
2)现金收购要约的采购方法扩展到各类款项,如杠杆收购和交换的股票的。
例如,TCL法国的汤普森在其收购的资产注入股份交换的方法。
3)虽然大跨境并购交易中占主导地位的国有企业,收集国有和民营企业也成为近年来活跃在。
4)涉及的行业领域延伸至国内垄断行业,如能源,化学制品制造业普遍。
3.学术评论有大量文献国内和跨国兼并和收购,主要是基于发达国家的经验。
有一些中国学者研究了在国内市场的兼并和收购的情况下。
例如,冯武(2001),使用会计数据及因素分析,制定一个整体的企业绩效评价函数。
他们没有找到的M&A公司的业绩在今年显着的变化,但在一年后性能提高,在第三年下降。
朱和王(2002)的股本回报率(ROE)和资产收益率(ROA)为收购方和目标公司于1998年67兼并和收购的情况下,分析改进。
张(2003年),采用事件研究法和会计分析方法,分析了中国上市公司的兼并,收购和重组。
他发现,兼并,收购和重组,目标公司的价值,但对股东收购公司的收入及财务表现产生了负面的影响。
佳(2003)报道,收购公司的表现,和他们以前的收购经验之间存在着倒U形关系。
我们没有发现,中国企业的跨国兼并和收购的实证研究。
在下面的章节中,我们将开发一些假设的基础上的跨境并购案例表现的可能的影响因素,当时的理论。
4.假设发展跨国并购的成果至少2大因素。
首先,它依赖于外部环境,如在本国的经济增长和竞争程度,东道国的政治和文化环境的变化等。
其次,取决于收购公司的资源和能力。
这是,我们要着眼于后者。
因此,几个假设,以反映的跨国并购公司的特点和性能之间的关系4.1预收购公司的收购表现控制权的分配和可能的协同作用,经常被用来解释收购前的性能和收购行为。
它们也可以用来解释收购与目标公司收购后的表现。
韦斯顿等。
(1990)提出,协同效应的主要来源,其中的收购增加值,这意味着经济效率提高后,企业的兼并与不同的管理能力。
一个比较有效的投标人购买效率较低的目标公司,并通过改善目标公司的效率,增加合并后的公司的价值。
从目标公司的角度来看,市场对公司控制权理论认为,它是一个公司的市场价值之间的差异,其实际价值,决定公司是否将被收购。
此外,收购公司和目标公司的管理效率之间的差异,确定目标公司的收购后的表现。
从收购公司的观点,市场对公司控制权的理论预测,收购前表现的无罪坚定的正相关,其收购的性能。
例如,郎咸平等。
(1989)发现,在要约收购中,收购公司和股东的利益的托宾Q 值呈正相关。
Servaes(1991)发现,与托宾Q值的收购方,收购方和被收购公司的股东收益是正相关。
在这些研究中,托宾的Q定义为公司的市场价值除以它的重置成本,作为一个公司的收购前业绩和管理能力的一个指标。
在此,我们制定以下假设:假设1:收购前的中国公司(收购方)和跨国并购性能表现呈正相关。
4.2自由现金流代理理论描述了股东与经理人之间的关系为委托代理关系。
委托人和代理人的不同,经常发生冲突的利益。
一位经理认为自己的利益为先,在做决策时,可能无法在股东的最佳利益。
詹森和麦克林(1983)定义了一个公司作为一个承上启下的合同,,争夺代理成本是不可避免的公众公司。
一类代理成本与自由现金流量是指后留在该公司的所有净现值为正的投资项目,涵盖了需要的现金数额的大小。
大量的自由现金流,可能会导致更高的代理成本收购公司的企业管治是不完善的。
当一家公司有一个大型的免费现金流,但没有或只是一个小的债务,股东和管理人员可能会面临着严重的利益冲突股息政策。
为了使自己的利益最大化,管理者不想分发的免费现金派息,并保留在公司内部的现金流。
因此,他们可以用这些资金不仅为他们个人的私人利益或过度投资,同时也为在未来可能损失的补偿(詹森,1986)。
如果没有良好的控制系统,以确保运营效率,自由的现金流可能导致代理成本高。
在这情况下,收购不能是一个明智的决定。
另一方面,自由的现金流是可再发行的金融资源,因此在收购公布,并把它变成更有效率的使用。
詹森还预测自由现金流行业的集中度的特点,表现出的自由现金流可以是一个严重的问题,公司大量的自由现金流和低增长的前景,特别是必不可少的公司注定要缩小。
这些企业面临的最严重的情况,在不盈利的项目投资上的浪费现金。
我们认为在中国的上市公司,自由的现金流可能会导致相同的代理成本。
派息降低了资源管理器的控制下,因此,经理人更愿意使用免费的现金流投资,而不是派发股息,即使这种投资可能不会产生积极的股东回报。
因此,我们假设有足够的现金流,收购公司在收购前收购后的表现不佳。
假设2:收购前的现金流中国公司(收购方)和其收购的性能是负相关的。
原文:Determinants of Cross-Border Merger & Acquisition Performance of Chinese EnterprisesAbstract:Using a unique data set on the cross-border merger and acquisition activities of the public companies listed at China's stock exchanges, we show that pre-acquisition performance and proportion of the state shares have a positive impact on performance of acquiring companiesKeywords: Cross-border mergers and acquisitions; Chinese enterprises; International-alization1. IntroductionIn the past thirty years China has experienced a rapid economic growth. In that period, a large number of Chinese enterprises have grown up and gained compositeness, a few have even ventured abroad to search for new sources of growth. One way of international expansion is to acquire existing businesses abroad, so called cross-border mergers and acquisitions (M&A). Although the number was low and the scales were small in the recent past, the trend is clearly picking up. It warrants a close look at this phenomenon to gain a better understanding on this matter.Cross-border M&A refers to a corporate action of purchasing the shares or assets of another company in a foreign country. Obviously, cross border M&A is a transaction of control rights between companies in two or more countries. Although the goals of cross-border M&A are often said to be creating value for the shareholders of acquiring companies, the results are far apart from the stated objective. Systematic studies show a considerable number of cross-border mergers and acquisitions end up in failure. In addition to differences in market environments between home and host countries, the competitive and comparative advantages of the acquiring companies are considered more important. Those advantages include corporate governance, top management term competence, learning ability, among others. Therefore, it s necessary to take a look at the firm specific factors that influence the performance of cross-boarder M&A. The main purpose of this study is to identify the factors that influence the outcomes of cross-border M&A made by Chinese firms in recent years, particularly, economic performance of the acquiring firms.The scale of cross-border mergers and acquisitions by Chinese firms has increased steadily in recent years. According to the United Nation Conference on Trade and Development, cross-border mergers and acquisitions by Chinese firms totaled US$ 8.139 billion in the period of 1988 to 2003, most of which occurred after 1997. While the average amount each year was only $ 216 million between 1988 and 2003, it reached the level of $ 1.647 billion in2003. There are a few well publicized cases: Shanghai Electric Group purchased a Japanese printing machine manufacturer in 2002, TCL acquired Schneider in Germany in 2003 and Lenovo purchased PC business of IBM in2004. All these cases show Chinese enterprises have entered an era of cross-border mergers and acquisitions.The economic performance of acquiring firms differs as a result of such corporate action. Some of the differences may relate to the motives of the international expansion. For example, some companies do it because of competitive pressure at home market, while others seek resources such as raw materials and technologies, and probably a few are even encouraged by government policy measures. Despite thevariety in their motives, many companies underestimate difficulties and integration risks in cross-border M&A and don’t have a clear idea about success factors that contribute to the difference in performance. Therefore it is imperative to have a good understanding of the relationship between performance of Chinese overseas mergers and acquisitions and determinant factors.Although the issue is clearly important, many serious academic studies are hard to find. A systematic search through the website of the China National Knowledge Infrastructure that lists all academic journals published in China give us nearly one thousand articles on cross-boarder M&A. Most are merely reviews of existing theories, descriptions of current situations or simple case studies.Our study attempts to analyze systematically economic performance and its determinants of cross border M&A made by Chinese companies in recent years. In addition to contribute to cross-border M&A literature, we also hope that the findings can provide useful guidance to outward foreign direct investment by Chinese enterprises in the future.Cross-border M&A is not new. What this paper intends to contribute is to explain the firm level factors and performance of overseas M&A by Chinese enterprises. Because the M&A performance are influenced by multiple factors, we adopt a multiple theoretical perspectives, specifically, organization learning perspective and agency theory.As we discussed early, we have not yet found a well developed database on the cross-border M&A, therefore we develop on our own a database covering 165 M&A cases by searching through various data sources including company websites, annual reports, newspapers, and the internet.The paper is organized as follows. The features of cross-border M&A activities of Chinese firms are discussed inspection 2. After a short literature review, a number of hypotheses are developed based on a number of theoretical perspectives. Section 4 discusses the methodology and results are reported in section 5 before the concluding remarks.2. Features of Cross-border M&A by Chinese CompaniesCross-border M&A by Chinese companies began in the 1980s, with most of the target companies located in the US, Canada and Hong Kong. The firms involved were basically large state-owned enterprises, such as CITIC, SINOCHEM, Capital Steel and China Resources. For example, Beijing Capital Steel Group purchased 70% shares of an American engineering company MASTA for US $3.4 millions in July 1988. In the 1990s, more and more Chinese companies start engaging acquisitions overseas. In addition to the state-owned enterprises, privately and collectively owned enterprises also joint the game. After entering into the 21 century, Chinese firms become more aggressive in cross-border mergers and acquisitions, several large cases occurred, such as the purchase of Korean company Sang Yong Motor Company by Shanghai Automotive Industry Corporation and the purchase of PC business of IBM by Lenovo.Anecdotal observations show a few tendencies: 1) volume and sum of transactions increase over time. Figure.1shows amounts of money involved in that cross-border mergers and acquisitions of Chinese enterprises. Although the amounts of money involved vary over the years, but the trend is going up. 2) The purchasing method extended from cash offer into various kinds of payments, such as leveraged acquisitions and swap of equity shares. For example, TCL used the methods of asset injection and shares swap in its acquisition of Thompson of France. 3) Although the state-owned corporations dominate in big cross-border M&A deals, collectedly owned and private enterprises also become active in recent years. 4) The industries covered extended from domestically monopolized industries such as energy, chemicals to manufacturing industry in general.3. Literature ReviewThere is a vast literature on both domestic and cross-border mergers and acquisitions, mostly based on the experiences from developed countries. There are a few Chinese scholars have studied mergers and acquisitions casein domestic markets. For example, Feng and Wu (2001), using accounting data and factor analysis, formulate an overall evaluation function of corporate performance. They do not find significant change in firm performance in the year of M&A, but the performance improves in the year after and falls back in the third year. Zhu and Wang (2002) analyze improvement of return on equity (ROE) and returns on assets (ROA) for both acquirer and target companies in 67 mergers and acquisitions cases in 1998. Zhang (2003), using event study method and accounting an alytical method, analyzes the mergers, acquisitions and reorganizations of Chinese publicly listed companies. He found that mergers, acquisitions and reorganizations add value to the target company, but had a negative influence upon shareholders’ income and financial performance in the acquiring company. Jia (2003) reports a reverse U shape relationship exists between performance of acquiring companies and their previous acquisition experience. We do not find empirical study on cross-border mergers and acquisitions of Chinese companies. In the following section,we are going to develop a few hypotheses based on the prevailing theories on possible factors that influence the performance of cross-border M&A cases.4.Hypotheses DevelopmentThe outcomes of cross-border M&A depends at least on 2 broad factors. First of all, it depends on external environment, such as economic growth and degree of competition at home country, changes of political and cultural environment of host country and so on. Secondly, it depends on resources and capability of the acquiring company.It is the latter that we are going to focus on. A few hypotheses therefore are developed to reflect the relations between acquiring firm characteristics and performance of cross-border M&A.4.1 Pre-Acquisitions Performance of Acquiring FirmsAllocation of control rights and possible synergy are often used to explain pre-acquisition performance and acquisition behavior. They are also used to explain post-acquisition performance for both acquiring and target firms.Weston et al. (1990) proposes that synergy effect is one of the main sources in which acquisition adds value, which means economic efficiency can improve after mergers of firms with different management capabilities. A relatively efficient bidder purchases a less efficient target firm and increases the value of the merged firm through improving target firm’s effectiveness.From target firm perspective, market for corporate control theory argues that it is the difference between a company’s market value and its actual value that determines whether a firm will be acquired. Moreover, the difference of management efficiency between the acquiring firm and the target firm determines the target company's post-acquisition performance. From the acquiring firm s viewpoint, market for corporate control theory predicts that pre-acquisition performance of the acquitting firm is positively related to its acquisition performance.For example, Lang et al. (1989) found that in tender offers, Tobin Q value of acquiring firms and shareholders’interests are positively related. Servaes (1991) found both acquirer’s and acquired company’s shareholders gainsare positively associated with the Tobin Q value of the acquirer. In these studies, Tobin s Q, defined as the market value of a company divided by its replacement cost, is used as an indicator of a company s pre-acquisition performance and management capacity. Hereby we develop the following hypothesis:Hypothesis 1: Pre-acquisition performance of Chinese company (the acquirer) and its cross-border acquisition performance are positively related.4.2 Free Cash FlowAgency theory describes that the relationship between shareholders and managers as a principal-agent relationship. The principal and agent have different and often conflict interests. A manager considers his own interest first when making decisions that may not at the best of interest of shareholders. Jensen & Meckling (1983)define a firm as a nexus of contracts, contending that agency cost is unavoidable in public companies.One kind of agency costs is associated with the magnitude of free cash flow that refers to the amount of cash leftin the company after covering the need of all investment projects with positive net present value. Large amounts of free cash flow can cause higher agency cost when corporate governance of acquiring company is imperfect. When a company has a large free cash flow but no or just a little debt, shareholders and managers may face a serious conflict in interests regarding dividend policy. In order to maximize their interests, managers prefer not distributing the free cash as dividend payout and to keep free cash flow within the company. Therefore they can use that cash not only for their personal private benefits or over-investment, but also for compensation of possible losses in the future(Jensen, 1986). If there is no good control system in place to ensure efficiency in operations, free cash flow may lead to high agency cost. Under that circumstance, acquisition cannot be a sound decision. On the other hand, free cash flow is redistributable financial resource thus released in acquisitions, and put it into more productive use.Jensen also predicts the characteristics of the free cash flow concentrated industries, showing that the free cashflow can be a serious problem for companies with large amounts of free cash flow and low growth prospect, and especially essential for companies doomed to shrink. These companies face the most serious situation for wasting cash on investments in non profitable projects.We argue free cash flow can cause the same agency cost in China’s publicly listed companies. Dividend payout lowers the resources under manager’s control; therefore managers prefer using free cashflow to invest instead of dividend payment, even though such investment may not generate positive returns to shareholders. Therefore, we hypothesize that acquiring company with sufficient cash flow before acquisition has poor post acquisition performance.Hypothesis 2: Pre-acquisition free cash flow Chinese company (the acquirer) and its acquisition performance are negatively related.References[1] Eisenhardt, K.M., 1989. Agency Theory: An Assessment and Review. The Academy of Management Review, 14(1): 57-74.[2] Feng, Genfu and Linjiang Wu, 2001. Empirical Study of Performance of Mergers and Acquisitions of Chinese Public Companies. EconomicResearch, 1, in Chinese[3] .Fowler, K. L. & Schmidt, D. R., 1989. Determinants of tender offer post-acquisition financial performance. Strategic Management Journal, 10(4): 339.[4] Franks, J., R. Harris & S. Titman, 1991. The post-merger share-price performance of acquiring firms. Journal of Financial Economics, 29. pp.81-96.[5] Haleblian, J. & S. Finkelstein, 1999. The influence of organizational acquisition experience on acquisition performance: A behavioralperspective. Administrative Science Quarterly, 44 (1): 29.[6] Harrison J. S., M. A. Hitt, R. E. Hoskisson & R. D. Ireland, 1991. Synergies and Post Acquisition Performance: Differences Versus Similaritiesin Resource Allocations. Journal of Management, 17: 173-190.[7] Hayward, M. L. A., 2002. When do firms learn from their acquisition experience? Evidence from 1990—1995. Strategic Management Journal,23 (1): 21.[8] Hitt, M., Harrison, J., Ireland, R. D., & Best, A., 1998. Attributes of Successful and Unsuccessful Acquisitions of US Firms. British Journal ofManagement, 9 (2): 91.。
中国企业跨国并购影响因素分析
中国企业跨国并购影响因素分析一、引言随着中国企业走向互联网时代,跨国并购成为了其推进国际化的一种重要方式,也是提高自身实力和国际竞争力的必由之路。
然而,跨国并购也存在很多风险和不确定性,尤其是涉及到跨越不同国家和文化的复杂交易时,涉及的因素更是复杂多变。
因此,为了让中国企业能够更好地进行跨国并购,在此我们就对于中国企业跨国并购影响因素进行一番探讨。
二、经济环境因素1、宏观经济环境宏观经济环境是指国家总体经济发展状况,包括GDP、通货膨胀率、利率、国际收支等等。
对于跨国并购来说,对于基础的宏观经济环境很敏感,因为这和企业的融资和对于资本市场的影响有直接关系,如果宏观经济环境波动较大,上市融资就可能出现不稳定的情况,从而阻碍了企业的跨国并购。
2、财务管理要素企业的财务管理状况是影响企业跨国并购的重要因素之一。
现代金融流通越来越便利,企业的财务管理不仅包括国内的会计体系、财务报表等等,也要对跨国交易涉及到的国际财务情况和法律法规做到深入了解。
企业应根据自身的实际情况来提出合理的财务管理和风险控制方案,保证跨国并购交易的顺利完成。
3、税收政策在跨国并购过程中,税收政策的调整对企业的合并与收购能否成功也有很大的影响。
政府可以通过税收鼓励跨国并购,给出税收减免优惠政策。
同时,发达国家往往会采取一系列措施限制国外企业在其领土内进行跨国并购,比如对于某些国际投资者的针对性税制,企业需要做好税收政策的分析,以兼顾各种利益。
三、监管政策因素1、监管机构跨国并购过程涉及到多种监管机构,包括国内外监管机构和各级政府部门,如外交部、财政部、商务部等。
在跨国并购过程中,各种监管机构的授权和审批影响企业是否能够获取相应的资质,从而达成交易。
除了这些机构,其他的民间组织和非政府机构也对于这样的交易过程产生影响。
2、政策法规各国之间在政治和法律走向上的差异不可避免,跨国并购因此需要遵守各种相关的政策法规。
跨国并购反垄断和竞争法、劳动法、知识产权法、国家安全法等等,都需要在交易过程中进行合适的措施和调查,避免对于交易各个方面产生影响。
我国上市公司跨国并购绩效的影响因素研究的实证分析

我国上市公司跨国并购绩效的影响因素研究的实证分析我国上市公司跨国并购绩效的影响因素研究的实证分析引言随着全球化的加深和经济一体化的推进,跨国并购已成为当今世界上一个重要的经济活动。
作为一个经济发展迅速的国家,中国的上市公司也积极参与国际市场竞争,通过跨国并购来获取资源、技术和市场等方面的优势。
然而,尽管跨国并购给公司带来了发展机遇,却也伴随着一系列的挑战和风险。
因此,深入研究我国上市公司跨国并购绩效的影响因素,对于指导企业战略决策、提高绩效和实现可持续发展具有重要意义。
一、文献综述1.1 跨国并购绩效的定义与衡量指标跨国并购绩效是指在跨国并购过程中,公司通过收购或合并方式获取新的资产、技术、市场等资源后所产生的经济和商业效益。
通常用于衡量跨国并购绩效的指标有市场价值、财务绩效、战略绩效等。
1.2 影响跨国并购绩效的因素影响跨国并购绩效的因素包括企业因素、市场因素和环境因素等。
企业因素主要包括公司规模、资本实力、管理能力等。
市场因素主要包括市场开放程度、行业竞争激烈程度等。
环境因素主要包括政治、法律、文化等因素。
二、方法论2.1 研究数据本研究选取了2010年至2020年间我国上市公司进行的跨国并购案例作为研究对象,共计100个案例。
2.2 研究模型本研究基于现有的理论框架,构建了跨国并购绩效的影响因素研究模型。
模型包括企业因素、市场因素和环境因素三个主要影响因素。
2.3 数据分析方法本研究主要采用定量研究方法,通过对跨国并购案例数据进行统计分析,并利用SPSS等工具进行实证分析。
三、实证分析结果3.1 企业因素对跨国并购绩效的影响研究结果表明,企业的规模、资本实力和管理能力对跨国并购绩效有着显著影响。
规模较大的企业更容易在并购过程中获取更多的资源和优势,资本实力较强的企业更能够承担风险和挑战,管理能力较强的企业更能够实现资源的整合和优化。
3.2 市场因素对跨国并购绩效的影响研究结果表明,市场开放程度和行业竞争激烈程度对跨国并购绩效有一定的影响。
我国上市公司跨国并购绩效的影响因素研究的实证分析
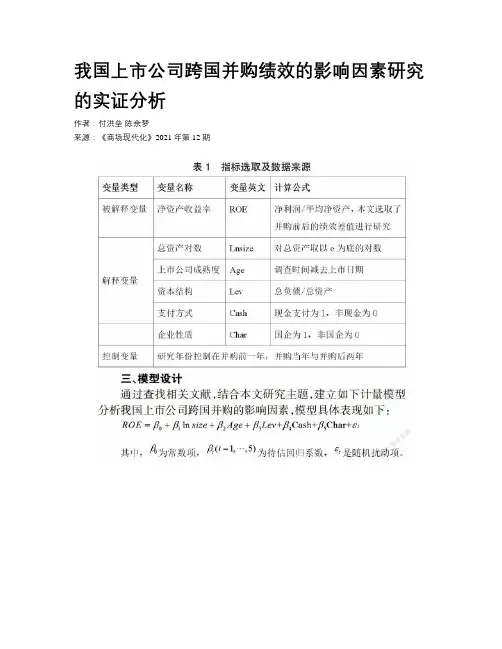
我国上市公司跨国并购绩效的影响因素研究的实证分析作者:付洪垒陈余梦来源:《商场现代化》2021年第12期摘要:在经济全球化的背景下,越来越多的中国企业开始加入到跨境并购的行列中。
尽管跨界并购活动在全球范围内变得更加激烈,但是我们仍然不能忽视其潜在的风险和问题。
因此,本文选取企业跨国并购的绩效为指标,研究了影响企业跨国并购绩效评价的几个主要因素,让企业跨国并购时少走弯路,并提供合理的参考意见。
关键词:跨国并购;公司绩效;实证分析一、研究假設1.企业规模对跨国并购前后企业绩效的影响企业规模越大,企业拥有的资金就越雄厚,而资金的充裕度能为企业并购提供必要的物质基础,但企业规模越大,企业容易引发“大企业毛病”,能用企业资金解决的问题都不是大问题,但这可能导致大企业在并购之前尽职调查可能做得不够深入,企业并购后在企业经营战略方面面临较大差异,此时企业双方因战略不明、经营不善,引发企业并购经营存在人为干扰或阻碍,此时企业并购绩效会比较差。
基于此,假设H1:企业规模与我国上市企业跨国并购绩效负相关2.企业上市年限对企业跨国并购前后绩效的影响企业的上市年限可以体现出企业的发展时间跨度和经营理念的成熟度,企业经营理念越成熟,企业并购经验也会越丰富,容易让并购方企业与被并购方企业更好融合,实现企业之间的经营交叉与合并,剔除一些较差的资产,集中优势整合双方的优质资源,实现双方企业之间的资源最优化配置,在改善双方企业主营业务的同时,提升并购企业的绩效。
基于此,假设H2:上市公司年限与我国上市企业跨国并购绩效正相关3.企业资本结构对企业跨国并购前后绩效的影响负债在一定的程度上可以体现出企业的经营能力。
企业负债经营,虽然会产生利息,企业额外付出成本,但在不发生偿债危机的情况下,企业借入资金进行跨国并购,企业在支付利息同时,利用财务杠杆整合双方资源,求同存异,提升与扩展企业的经营范围,实现企业绩效的提升。
基于此,假设H3:企业资本结构与我国上市企业跨国并购绩效正相关4.企业支付方式对企业跨国并购后绩效的影响企业在支付方式中涉及现金支付与非现金支付,支付方式的差异使得企业并购的绩效也有所不同,具体表现为当企业采用现金支付时,会使股民对企业产生良好的印象。
跨国公司海外并购绩效评估与影响因素研究

跨国公司海外并购绩效评估与影响因素研究海外并购是当今全球经济中跨国公司面临的一个重要战略选择。
然而,并购的成功与否对公司业绩产生深远的影响,因此对于跨国公司来说,对海外并购的绩效评估以及影响因素的研究具有重要的意义。
本文将从绩效评估的角度出发,探讨跨国公司海外并购的绩效评估方法,并分析影响并购绩效的主要因素。
一、绩效评估方法1. 财务绩效评估:财务绩效是评估并购的重要指标之一。
可以通过分析收入、利润、资产利润率和现金流量等财务数据,对并购后的公司财务状况进行比较。
同时,还可以考虑经济附加值(EVA)等指标,以评估并购对公司价值的影响。
2. 市场绩效评估:市场绩效是另一个重要的评估指标。
可以通过分析并购后公司的市值、股价表现以及市场份额的变化等指标,评估并购对市场竞争地位的影响。
3. 组织绩效评估:组织绩效评估关注的是并购对公司内部业务流程和组织结构的影响。
可以通过分析员工满意度、组织效率以及创新能力等指标,评估并购对公司内部运营的影响。
二、影响因素分析1. 并购目标选择:并购目标的选择是影响并购绩效的关键。
应当考虑并购目标的国别、行业、规模与公司战略的一致性。
行业差异性、文化差异性等因素也需要被纳入考虑范畴。
2. 并购整合能力:并购整合能力是决定并购绩效的重要因素。
并购后如何高效整合两个公司的资源和能力,如何实现业务的协同,都将直接影响并购的绩效。
公司应该制定相应的整合计划,并建立有效的沟通渠道,以便将并购目标与本身的能力紧密结合。
3. 领导力与管理团队:领导力与管理团队是并购绩效的决定性因素。
具备良好的领导力和管理团队能够有效应对并购过程中的挑战,带领公司实施整合计划,确保并购的顺利进行。
4. 文化融合:公司文化的融合是影响并购绩效的重要因素之一。
跨国并购往往伴随着不同国家和地区的文化差异,如果不能很好地融合文化,可能会导致组织冲突和员工困扰,对绩效产生负面影响。
5. 法律与政策环境:法律与政策环境是跨国并购绩效的外部因素。
我国企业跨国并购绩效影响因素的研究

我国企业跨国并购绩效影响因素的研究随着中国企业国际化进程的加速,跨国并购成为了企业走向国际市场的一种常见方式。
但是,并购过程中的不确定因素较多,可能会影响并购后的绩效。
因此,本文就国企业跨国并购绩效影响因素进行了研究。
一、管理层有效性企业管理层的有效性是影响跨国并购绩效的关键因素之一。
在跨国并购中,对于两家企业的管理层来说,要实现文化融合和经验共享,必须足够开放、合作和互信。
而且,跨国并购中管理层沟通和决策的有效性,也非常重要。
如果在并购过程中,管理层的意见分歧和决策失误,就会对并购后的绩效产生不利影响。
二、文化差异文化是影响跨国并购绩效的重要因素之一。
通过并购,企业可以获得新的市场和资源,但是,不同公司之间的文化差异也是很大的。
这些文化差异包括语言障碍、风俗习惯、价值观等方面。
如果不能充分了解对方企业的文化差异,就难以进行有效的跨国合作,这对跨国并购的绩效产生不利影响。
三、重组过程跨国并购过程中的重组是影响并购后绩效的重要环节之一。
重组是指企业在并购过程中对原有的组织和业务进行重新设计和调整。
重组成功与否,对企业的绩效影响非常大。
如果重组过程中没有充分考虑到人员的流动、业务品种和管理制度等因素,就会导致重组后的企业出现问题,从而影响并购的绩效。
四、目标企业的经营状况目标企业的经营状况也是影响跨国并购绩效的重要因素。
在并购过程中,如果目标企业经营状况较差,企业并购后需要投入更多资源来调整经营,从而影响并购后绩效。
因此,在进行跨国并购时,对目标企业的经营状况进行充分的考察,可以有效避免出现这种状况。
综上所述,管理层有效性、文化差异、重组过程和目标企业的经营状况是影响国企业跨国并购绩效的关键因素。
企业在进行跨国并购时,应该充分考虑这些因素,并采取相应的措施来实现最大程度的融合和协作,从而提高并购后的绩效。
跨国并购 外文翻译原文

Analysis of Merger and Acquisition Strategy of Multinationals in China and ChineseEnterprises CountermeasuresAbstractMergers and acquisitions of transnational corporations in China presents the strategic trends in recent years. Merger and acquisition strategy of multinationals in China to successfully implement, not only objective necessity of political reform and economic development in China, there are also accidental by Chinese enterprises and government of the subjective errors caused. To prevent risk of multinational merger and acquisition in China, Chinese enterprises should raise awareness of multinational merger and acquisition, carefully chosen joint venture partners, build complete learning system in joint venture/cooperative, enhanced learning capabilities, and enhanced management of merger and acquisition strategies.Key words: Multinational corporations; Merger and acquisition strategy; Joint venture; CooperationIn the late 1990 of 20th century, multinational companies merger and acquisition activity in China is increasing, from all indications, merger and acquisition of multinational corporations in China in recent years had a profound international background, this is a strategic merger behaviors. Grasping the nature of multinationals merger and acquisition strategy in China, it is the important basis for understanding transnational corporation mergers and acquisitions in China.1.THE NATURE OF MERGER AND ACQUISITION STRATEGY OF MULTINATIONALS IN CHINADifferent from the previous financial mergers and acquisitions or buy shells of mergers and acquisitions, merger and acquisition motives of multinational corporations in China in recent years, not for implementation of speculative gains, but through the merger and monopoly of the world markets for goods and investment, to seize the material and technical and human resources, successful implementation of global management strategy. It can be said that mergers and acquisitions of strategic motives of transnational corporations presents the strategic trends. To multinational recently on China equipment manufacturing enterprise for multiple mergers and acquisitions as cases, although so far, multinational only respectively on some backbone Enterprise for mergers and acquisitions, under effect in domestic various forces, has not been to implement overall of strategic, and systematic of mergers and acquisitions (is on domestic different area, and same industry several backbone enterprise ofmergers and acquisitions), has not been constitute of threat on China entire equipment manufacturing of key industry, and main area. But the trend of mergers and acquisitions to systematic, high specification, such as, after the United States Caterpillar company mergers and acquisitions in Shandong engineering machinery company, seek merging domestic construction machinery industry of key enterprises, such as Xiamen engineering machinery company, Weifang diesel power company,and Shanghai diesel power company of, reflects this trend.2. COMPREHENSIVE ANALYSIS OF MERGER AND ACQUISITION STRATEGY OF MULTINATIONALS IN CHINA2.1 Charctristics of Mergers and Acquisitions IndustryMultinational merger and acquisition in China in recent years mainly concentrated in three main areas: first, the area of production and supply of electric power and other energy; the second is basic materials area, such as steel, chemical raw materials industries; the third is consumer goods production area of beers, soft drinks, skin care products and so on. These industries have the following in common: with foreign investment in these sectors are relatively mature industry, foreign capital has formed a certain scale of production and capital accumulation in the domestic; these are industries that has been or is being lifted; Mergers and acquisitions industry has the characteristics of potential of large scale and high growth potential. In recent years, as China’s economy continues to grow, rising standards of living, potential size and growth potential in the consumer goods industry began to emerge, so as to drive the demand for energy and basic materials industry rapidly rising, making it difficult to meet the market demand for the production capacity of these industries. In order to quickly dominate the market, transnational corporations have used mergers and acquisitions or expansion of investment into China.2.2 Acquisition ways characteristicsIn General, mergers of transnational corporations in China in the following three ways: first, the restructured holdings acquisition, that is, through participation in the restructuring of domestic enterprises, acquisition of 50% per cent of its equity, to achieve control of enterprise management purposes. For example,In March 2001, China tire industry leading enterprise --China Tire and Rubber Compa ny and the world’s largest tire manufacturer-Michelin formed a joint venture company, Michelin 70% stocks, venture companies invest US $ 320 million reverse takeover of tire rubber company’s core business and assets. Second, increased capital holdings acquisition, that is, in the original on the basis of China-foreign joint ventures, foreign capital increase and share, Chinese does not participate in the capital increase, lower the shares, so that the foreign share holdings. For example,In April 1994, Dalian Motor factory and Singapore Wester motor company established a joint venture of Wester (Dalian) Motor Co., Ltd. In April 2004, Wester further mergers and acquisitions the shares held by the Chinese side of Dalian motor company. Third, the share acquisition, that is, foreign companies at the same time offering a-shares and b-shares, or h-shares, acquired not circulation of legal person shares by agreement or holdings of a large number of b-shares, or h-shares, achieve the purpose of shares or holdings. Such as Beijing wagon limited companyand Japan Isuzu motors and Itochu Shoji Corporation signed a cooperation agreement, Isuzu and Itochu joint agreements to purchase, one-time purchase of North brigade not listing circulation of legal person shares 4 20,000 shares of the company, 25% per cent of total share capital of Beijing wagon limited company, become the largest shareholder of Beijing wagon limited company.Characteristics of Acquired EnterpriseAcquired enterprise general is State or State holding enterprise has development years in domestic, has popularity high of brand, sound of market sales network, more advanced of technology, but due to management system does not perfect, history causes, has into business dilemma, enterprise was forced to overall sold or transfer part quality assets, such as: Dalian Motor Factory, Jiamusi Combine Harvester Factory, and Northwest Bearing Factory, and Shenyang Chisel Rock Machinery Company and so on, these enterprises are industry of leader or challenger, but into cash flow problems due to various reasons, shrinking sales, business difficult to continue, in order to enliven the State-owned assets, resolve some of the workers’ employment, enterprises are forced to overall sold or transfer some good assets and joint venture with multinationals. Or for promoting the progress of technology and management need to seek foreign investment.2.4 Characteristics of Merger and Acquisition StrategyIn recent years, merger and acquisition strategy of multinationals in China is clear, they tend to choose the establishment of China-foreign joint ventures and foreign-controlled, final adoption of the foreign capital merger and acquisition, to a wholly foreign-owned enterprises. Even some multinational corporations seeking holding status when they established joint ventures. Then, in the business course of China-foreign joint venture enterprise, marketing channels is controlled by foreign enterprises, implementation of “high and low” strategy, transfer of profits, or do not want to put in new technology, numerous contradictions with China,Cause in fact of business losses, forcing the Chinese transfer of ownership to the foreign, foreign acquisitions China shares, desire for realization of wholly-owned .For example, Fu Anjie railway bearing (Ningxia) Ltd., Wester (Dalian) Motors Ltd., Dalian Burton Motors Ltd , such these joint ventures were turned into a wholly foreign-owned enterprises by foreign merger and acquisition of Chinese shares .3. ANALYSIS OF THE REASONS FOR THE SUCCESS OF THE MERGER AND ACQUISITION STRATEGY OF MULTINATIONALS IN CHINAMerger and acquisition of multinationals in China has an obvious strategic, but why the merger and acquisition strategy of multinationals in Chinacan be successfully implemented? There are the objective inevitability of both political and economic reform and development in China,also with Chinese enterprises and Government error led to the contingency subjective.3.1 the objective necessity of transnational companies successfully implement the strategy of Merger and Acquisition in china3.1.1 Reform of State-Owned Enterprises Offers a Number of Opportunities to Multinational Mergers and Acquisitions Strategy in ChinaReform of State-owned enterprises had a high demand on foreign funds. There are nearly 400,000 State-owned enterprises in China, many companies will need restructuring or reorganization, there are three areas of funding gap in restructuring or reorganization process: first, the social security funds; the second is the restitution of fun ds banks ‘ bad loans in State-owned enterprises; The third is the sale of State-owned assets of the funding gap in a competitive business. There are three ways to cover the financing gap: country financial; absorbing domestic and foreign investment; State can no longer provide huge amounts of money for the reform of State-owned enterprises, absorbing domestic investments, because lack of non-State-owned investment capacity and willingness and impossible to large-scale implementation domestic investment, which provides opportunities for transnational corporation mergers and acquisitions of State-owned enterprises in China.3.1.2 Conversion from Joint Venture and Cooperation Mode to Wholly-Owned Mode is the Inevitable of Chinese Economic Reform and DevelopmentCooperative and owned is two patterns of internationalization of multinational companies. Due to transnational corporations initial entry into the host country, transnational corporations did not familiar on host country policies, culture, market environment, host country governments development of a number of barriers to entry, sole risk higher than joint venture and cooperation. However, as changes in the he host country environment caused location advantage of enhancements, transnational corporations increases experience through studying, enhancements and strengthened ownership advantage strategic motives of transnational corporations, risk and return of the wholly-owned and joint venture and cooperation mode has changed, wholly-owned gradually replaced so that joint venture and cooperation, replacing a variety of ways, merger and acquisition is one of the most important way. There are three reasons promoting the successful implementation of a merger and acquisition strategy of multinationals in China. First, the rapid development of China’s economy for many years, China’s growing importance in the world economy, the world’s largest potential market is gradually maturing and Chinese market position gradually growing in the global strategy of transnational corporations in China, thus increasing the multinationals take sole mode of income. Second, after joining the WTO, China gradually open industries, lowering the barrier to entry of multinational merger and acquisition enterprises in China, thereby reversing the multinational joint ventures and wholly-owned of risk and return ratio. Third, the multinational companies operating in China for a period of time, get to know China and Chinese markets, which reduces the investment risk.3.2 THE SUBJECTIVE CONTINGENCIES OF TRANSNATIONAL CORPORATIONS SUCCESSFUL IMPLEMENTATION MERGER AND ACQUISITION STRATEGY IN CHINA3.2.1 Failure of Chinese Enterprises Implementation Joint Venture and Cooperation StrategyMore important reason of Multinational companies from the joint venture and cooperation to the holding and to a wholly-owned strategy success is Chinese joint-venture, cooperation strategy failed.First, the Chinese enterprises lack of knowledge on the complexity of the joint venture and cooperation. Joint venture and cooperation is a wide range of more complex problems ona variety of cultural, enterprises and strategies. To achieve the strategic purpose of the joint venture and cooperation, joint ventures, cooperation between the two sides have to properly address issues such as cultural conflict, distribution and disposal of the proceeds, technology learning and protection. China business knowledge on the complexity of the joint venture and cooperation is often not enough, more attention to possible benefits brought by joint venture and cooperation, ignoring the risk of joint venture and cooperation, results to run some of the poor handling of the conflict, affecting the normal operation of the joint venture and cooperative enterprises, or foreign opportunism of inadequate preparations, finally was forced to participate in mergers and acquisitions.Second, Selected not appropriate for joint ventures and cooperation partners.When choosing a partner for Chinese enterprises are often too look at the size of the transnational corporations, technology and management of advanced degrees, and ignore the foreign joint venture of mind, ignored the two parties on the cultural fit, complementary capabilities and resources, as well as position in the joint venture and cooperative enterprises, and many other issues. Making some multinational companies not only to low cost entry into the Chinese market, and dominate in the joint venture and cooperative enterprises, for further mergers and acquisitions Chinese companies with an opportunity.Third, the failure of joint ventures and cooperative learning mechanism in the process. Learning advanced technology and management experience is the main causes of Chinese enterprises and multinational companies to form joint ventures and cooperative enterprises, but Chinese enterprises often do not have to establish a learning mechanism in the process of joint-venture and cooperation. Learning mechanism failure caused results of China enterprise joint venture and cooperation loss of marke t, but haven’t learned skills and experience.3.2.2 Failure of The Merger and Acquisition of Chinese Enterprises StrategyFirst, goals of participating in transnational merger and acquisition is fuzzy and negotiation failure. When Chinese enterprises participating in transnational merger and acquisition, have only good intentions, there is a lack of long-term strategic objectives and effective negotiating routes design, eager to reorganization of assets, high quality assets on multinational mergers and acquisitions, bad assets, debt and the burden of bureaucracy has left China’s parent company. High quality assets are joint ventures with transnational corporations and have not good grasped of commercial negotiation conditions and patterns, and give up control of a joint venture, parent company lost its core competitiveness, lost technology, brand and marketing, enterprise techniques and technology research and development in the future depends on the strategy arrangements of transnational corporation. Second, choosing the merger and acquisition of foreign investors misconduct. Different types of merger and acquisition of foreign investors, determine the effect of mergers and acquisitions different. International multinational consortium with strong financial strength, can easily mobilize huge amounts of money, holding and acquisitions of Chinese companies, and asset consolidation, packing, then go to the foreign or domestic capital markets for cash, earn high profits. China to introduce such investors, although can avoid to be controlled on the technology and production, access to financial support for the time being, are unable to obtain knowledge of manufacturing technologies and production, marketing, does not help enterprises to raise the level of technology and management, and even lose the basis forlong-term development. When many Chinese companies involved in mergers and acquisitions, without carefully assessing and weighing the introduction of different foreign investor to bring effects and interest and blindly participating in transnational mergers and acquisitions, resulting in counterproductive.4. COUNTERMEASURES OF CHINESE ENTERPRISE FACES MULTINATIONALS MERGER AND ACQUISITION STRATEGY IN CHINA4.1 Increasing Awareness of Multinational Merger and Acquisition strategyFirst, clear understanding of the nature of merger and acquisition strategy of multinationals in China. Multinational merger and acquisition in China has not only access to markets, but sought trade monopolies and globally integrated supply chain. Second, fully understand the risks of joint venture/cooperative, understand the advantages and disadvantages of mergers and acquisitions, raising awareness of risk prevention. Joint venture, cooperation and mergers and acquisitions has a double-edged sword effect, to fully assess the risks of losing markets, brands and core technology in the process of joint-venture, cooperation and mergers and acquisitions, and increased awareness of risk prevention, to take effective measures to prevent risks to organization structure design, patent protection, and other aspects. Thirdly, recognizing the importance that keep own business brand and core technology for sustainable development. Brand and core technology is the key source of enterprise’s core competitiveness, loss of brand and core technology will reduce the bargaining power of competition and cooperation of Chinese enterprises and transnational corporations, eventually reduced to matching supply of vendors of multinational corporations has a core competence .4.2 carefully choosing a foreign joint Venture PartnersWhen select partners in joint ventures, to thoroughly understand and analysis the strategic intent the foreign, final judgment goal of foreign joint ventures take acquisitions as a strategy only get into the Chinese market in the early days, aimed at bypassing the Chinese industry control, or for long-term business cooperation with Chinese enterprises. If the foreigner is for long-term business cooperation, Chinese companies should identify own real needs, maintain their unique resources and advantages, from the practical needs of enterprises and the advantages complementary between the two sides, carefully chosen joint venture partners.4.3. strengthening strategic Management capabilities of Mergers and Acquisitions4.3.1 Enhanced Ability to Develop Rational Merger and Acquisition StrategyAt the time of acquisition, Chinese enterprises should have clear targets and strategies of merger and acquisition. As backbone enterprise, to research itself market status, confirmed whether needs participate in transnational mergers and acquisitions; if must by assets restructuring out dilemma, whether must by multinational mergers and acquisitions; if had to looking for multinational mergers and acquisitions, to clear the target by mergers and acquisitions, and developed specific programme of mergers and acquisitions negotiations, using itself of resources, keep on joint venture enterprise of control right, especially to clear Enterprise for technology route of led right; if mergers and acquisitions must to gave upindependent development for premise, seeking borne the original debt and redundant staff placement by multinational enterprises. Otherwise, the value involved in mergers and acquisitions will be greatly reduced.4.3.2 Enhanced Ability to Identify Qualified Acquisition Investor based on reasonable estimation of the enterprise’s own development bottleneck is shortage of technology, shortage of funds, or the shortage of market-oriented, Chinese enterprise careful comparison and calculation of industrial investors and financial investors, commercial investors to enterprise resources and benefits, conditions and cost of the enterprise delivered, choose different types of mergers and acquisitions investors.4.3.3 Strengthen The Capacity of Protection Brand and Technology in Mergers and Acquisitions Process First, before implement mergers and acquisitions, should correctly awareness and assessment brand assets value, China enterprise should hired authority assessment institutions, used advanced of brand value assessment system to assessment brand assets, to prevent the local brand value of loss in foreign and joint venture enterprise mergers and acquisitions process; on the other hand, when mergers and acquisitions, high popularity and reputation of brand must to keep more independence, not easily is controlled by multinationals, this is key involved brand life .。
中资企业海外并购绩效影响因素及并购建议
OVERSEAS INVESTMENT & EXPORT CREDITS摘 要:影响中资企业海外并购绩效的因素有宏观战略因素、行业企业因素、交易操作因素等。
中资企业要以国家政策为导向,充分评估合理性和可行性,谨慎开展海外并购,重视咨询顾问作用,积极采用多元化支付和融资方式,推动海外并购行稳致远。
关键词:中资企业海外并购王一剑朱硕晟中资企业海外并购绩效影响因素及并购建议一、中资企业海外并购的现状和趋势(一)海外并购规模从高峰逐年回落2008年国际金融危机爆发后,低估值的海外资产成为中资企业“出海”的首选对象,中资企业海外并购快速增长。
2016年中资企业海外并购规模创历史最高。
2017年,随着国内监管逐步收紧和规范、海外审查趋严以及国际局势不断变化,海外并购非理性交易得到抑制,投资逐渐回归理性,交易数量与金额都大幅降低。
据商务部的统计数据,2018年中资企业共实施完成海外并购项目405起,实际交易总额703亿美元。
2019年中资企业完成海外并购项目591起,总金额686亿美元,交易金额进一步下降。
(二)海外并购特点近年来,随着宏观经济、国内外政策与法律法规、企业投融资环境变化,中资企业海外并购呈现出一些新趋势。
1.美欧发达国家比重下降,亚洲及“一带一路”沿线国家比重上升美国和欧洲曾经一直是中资企业海外并购的首选目的地。
据Dealogic数据库统计,2015年中资企业对发达国家企业的并购占中国海外并购总额的2/3左右。
受美欧贸易保护政策影响,中资企业海外并购目的地在2019年开始明显转向,亚洲已跃升为最受中资企业欢迎的海外并购目的地,投资金额占比超过三成,而在欧洲和北美洲的并购则大幅度减少。
①同时,中资企业对“一带一路”沿线国家的海外并购明显上升, 2016年海外并购22起,交易金额为19亿美元;2017年海外并购增至135起,交易金额升至216亿美元。
2018—2019年“一带一路”沿线国家并购金额虽小幅下降,但数量仍保持增长。
海外并购对企业绩效的影响分析
海外并购对企业绩效的影响分析随着全球化的加速发展,海外并购的方式已经成为许多企业扩张国际市场的重要方式之一。
与此同时,随着海外并购成为共识,也出现了不少质疑发声,更何况在一些海外并购案的成功与失败之间的界限往往异常模糊。
那么,究竟海外并购对企业绩效有何影响呢?在本篇文章中,我们将深入探讨海外并购对企业绩效的影响因素,并尝试从不同的角度阐述这一问题。
一、影响因素1.行业特性行业特性是影响海外并购对企业绩效的一个重要因素。
某些行业的市场地位和企业生命周期较为明显,这对海外并购的获取和整合都会产生深远影响。
以某些知名企业在冶金、石油、化工、机械制造等领域的海外并购为例,这些行业的市场需求量大、开发周期长、技术难度大,这些因素共同作用下会带来很高的技术费用,因此海外并购会成为某些行业成长过程中的一项重要资金来源之一。
2.文化因素文化因素也是影响海外并购对企业绩效的一个重要因素。
企业文化在决定组织内部运作的同时,也会影响企业和外部环境的互动。
同时,企业文化会直接影响员工的价值观和工作态度,从而间接影响企业绩效。
在海外并购中,企业文化的融合和交叉可能会出现困难,阻碍企业整合和协调,进而影响海外并购的绩效。
3.整合能力整合能力是影响海外并购对企业绩效的一个极其重要的因素。
在海外并购中,企业合并、兼并或收购后必须整合各种资源,协调合理的可增加企业绩效的机制,并尽可能地减少可能带来的融合成本。
如果企业在整合方面出现了问题,就有可能导致海外并购的业绩下滑。
如果企业在整合过程中合理的调整了自己的资源、人员、技术优势并用合理的风险管理方式保证企业的稳健性,那么海外并购就会对企业绩效产生良好的促进作用。
二、利好影响1.拓宽市场和客户资源在全球经济一体化的大背景下,海外并购带来的最大效益之一就是扩大市场和客户资源。
表现为:新进入的市场通常是经济成长快速、需要资源和技术的国家或地区,在这些市场中企业可以拓展和拓宽业务,提高销售量和客户基础,增加新的收入来源和利润点。
企业跨国并购绩效及影响因素论文
企业跨国并购绩效及影响因素论文【摘要】从政府角度,我国政府应该对跨国并购的企业提供支持,完善反垄断法及《上市公司收购管理办法》,规范我国的并购行为。
在支持海外并购的同时也要关注到民族企业的发展。
与其他国家建立良好的经济往来,保持政治经济稳定,为跨国并购营造一个良好的环境基础。
一、引言跨国并购与普通的并购并无太大差异,只在并购企业所属地上不同。
联合国贸易与发展会议(UNCTAD)定义跨国并购为东道国企业与他国企业合并,或者是收购另一国企业的股份超过10%,使该企业的资产和经营控制权转移到收购企业。
跨国并购为的就是收获正的并购绩效。
并购绩效从根本上讲就是提高企业的盈利能力、营运能力、优化资源配置效率、降低风险与成本。
从表现上来说,并购绩效可能表现为是股价或者公司估值的上涨下跌,或者是财务数据财务指标等。
跨国并购更多的还想要打开海外市场,实现国际化进程。
二、跨国并购绩效对于并购的绩效,无论是否跨国,都是褒贬不一。
按照人们的认知,跨国并购可以开拓企业的海外市场,迅速地进入国外市场并占领一定市场份额,也可以拥有并购所带来的协同效应、整合资源、分散风险等效益,增加企业的价值。
当然,跨国并购能够提高企业的绩效也是一直有学者证明,并且也都研究表明了中国的企业实行跨国并购,能够提高企业的经营绩效。
顾露露和Robert Reed(2011)通过对1994~2009年中国157个海外并购事件进行实证分析,结果表明并购对企业的经营绩效显著为正,中国企业跨国并购在中长期整体上取得了非负的超常回报率。
Jensen and Ruback(1983)指出成功的并购活动会给目标公司股东带来超常收益,收购公司股东获得的超常收益较小。
大多数学者也认同其观点,在并购中,被并购的公司实现正收益,收购过后,股价往往都会上涨,但是并购公司的股价几乎无上涨甚至呈现负收益。
在跨国并购中除了上述学者所研究表明的为企业带来超额收益外,也有学者证明了跨国并购并未为其带来收益。
中国企业跨国并购绩效影响因素的实证研究
注 :一 、 0 F 、 2 F 1 F 、 1F 分别表示并购前一年、 并购 当年、 并购
后 一 年 及 并 购后 两 年该 行 业样 本 企 业 的 综 合 绩 效 。
信息业 、 纺织业 、 机械制造 业 、 家电业 、 交
6 经济论坛 2 0 ・7 O 0 71
维普资讯
—■■l
市场经纬・ A K T M R E
中 企 跨 并 绩 影向 素 实 研 国业 国购 效 Ⅱ 的证 究 因
文/ 窦义 粟
2 世纪 9 年 代以来 , 0 0 在全球范围 内 的产业 升级 、 技术转移 、 放松 管制和一体 化 浪潮等 因素的推动下 ,全球 企业 跨 国 并购 的活动掀 起高 潮 。 而 , 2 0 然 从 0 1年 起, 随着 9 1 等恐 怖 活动 、 争 因素的 ・l 战 影响以及全球各 国企业对跨 国并购实际 效果 的冷静思考 ,全球跨 国并 购的浪潮 逐渐趋 于平静 。就在全球跨 国并购落下 帷幕的同时 ,中国企业却掀起 了跨 国并 购浪潮 , 中国企业 的 “ 出去 ”战略似乎 走 取得 了全 面的成 功。 而 , 然 繁荣 背后却有
购完成后的第 1 年有较大 的提 升 ,但可
点
年代 以后 ,世界 范围的并购 主要集 中于
在过去 的 2 0年 中 , 国 出现 了 三 次 中
金融服务业 和汽车业 。我 国企业 的跨 国 并购 以 电子信 息业 和机 械制 造业为 主 , 两 个产 业 的样 本 企 业数 量 占总样 本 的
效的影响 ,揭 示出 中国企业跨 国并 购过
程 中面 临 的更 微 观 的 问题 。
企 业的综合绩效则继续下降 。 但是 , 到了