
非居民纳税人税收居民身份信息报告表
Declaration:
我谨声明,我为需享受税收协定缔约对方税收居民,我成为缔约对方税收居民并非为了获得税收协定利益而安排。
I hereby declare that I am a tax resident of the other contracting party to the tax treaty and the purpose of becoming such a tax resident is not to obtain the tax treaty benefits.
Telephone number in China
非居民纳税人在居民国(地区)的联系电话
Telephone number in resident state (region)
非居民纳税人的居民国(地区)
Resident state (region)
非居民纳税人享受税收协定名称
Name of the applicable tax treaty
三、扣缴义务人使用信息
Ⅲ.Information for Use by Withholding Agent
提示:“税收居民”是指符合缔约国国内税法中对居民定义的人,包括企业和个人。如果非居民纳税人不是需享受税收协定缔约对方的税收居民,则不能享受税收协定待遇。
Note: The term "tax resident" means any person (e.g. an enterprise or individual) who, under the domestic tax law of a contracting state to the tax treaty, shall be regarded as a resident. If the non-resident taxpayer is not a resident of the other contracting party to the tax treaty, it shall not be entitled to the treatment under the tax treaty.
3.请引述非居民纳税人构成缔约对方税收居民的缔约对方国内法律依据:
Please cite the domestic legal basis based on which the non-resident taxpayer qualifies as a tax resident of the other contracting party:
非居民税人在居民国(地区)名称
Name of non-resident taxpayer in resident state (region)
非居民纳税人在居民国(地区)的纳税人识别号
Tax identification number of non-resident taxpayer in resident state (region)
□不具有独立纳税地位的营利实体
Business entity without independent taxpayer status
□政府
Government
□非营利组织
Non-profit organization
□其他
Others
*2.非居民纳税人在缔约对方的组织类型如为“其他”,请说明
Please explain if the answer to Question 1 is "others".
○扣缴申报 Withholding declaration
○退税 Tax refund
一、扣缴义务人基本信息Ⅰ.Basic Information of Withholding Agent
扣缴义务人名称
Name of withholding agent
扣缴义务人纳税人识别号
Tax identification number of withholding agent
非居民纳税人签章或签字年月日
Seal or signature of the non-resident taxpayer Y M D
1.非居民纳税人在缔约对方的组织类型
The organization type of the non-resident taxpayer in the other contracting party
□具有独立纳税地位的营利实体
Business entity with independent taxpayer status
非居民纳税人在中国联系地址和邮政编码
Contact address and postal code in China
非居民纳税人在居民国(地区)联系地址和邮政编码
Contact address and postal code in resident state (region)
非居民纳税人在中国的联系电话
非居民纳税人税收居民身份信息报告表(企业适用)
Information Reporting Form of Tax Residence Status of Non-resident Taxpayer
(For Enterprises)
填报日期: 年月日
Filling date: Y M D
○自行申报
Self-declaration
二、非居民纳税人基本信息Ⅱ.Basic Information of Non-resident Taxpayer
非居民纳税人中文名称
Chinese name of non-resident taxpayer
非居民纳税人在中国的纳税人识别号
Tax identification number of non-resident taxpayer in China
4.请简要说明非居民纳税人构成缔约对方税收居民的事实情况:
Please briefly describe the facts based on which the non-resident taxpayer qualifies as a tax resident of the other contracting party:
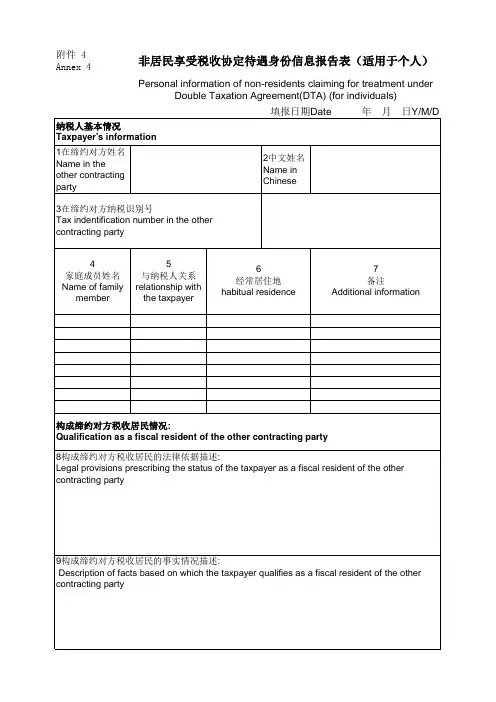
非居民享受税收协定待遇身份信息报告表(适用于个人)
26是否取得在中国的长期居留权 Does the taxpayer have the right to permanently stay in China? □是 Yes □否 No
27在最近纳税年度内在中国连续或累计停留天数 Number of days of continuous stay or cumulative stays in China in the past taxable year
填报日期Date 年 月 日Y/M/D
纳税人基本情况
Taxpayer's information
1在缔约对方姓名 Name in the other contracting party
2中文姓名 Name in Chinese
3在缔约对方纳税识别号 Tax indentification number in the other contracting party
附件 4 Annex 4
非居民享受税收协定待遇身份信息报告表(适用于个人)
Personal information of non-residents claiming for treatment under Double Taxation Agreement(DTA) (for individuals)
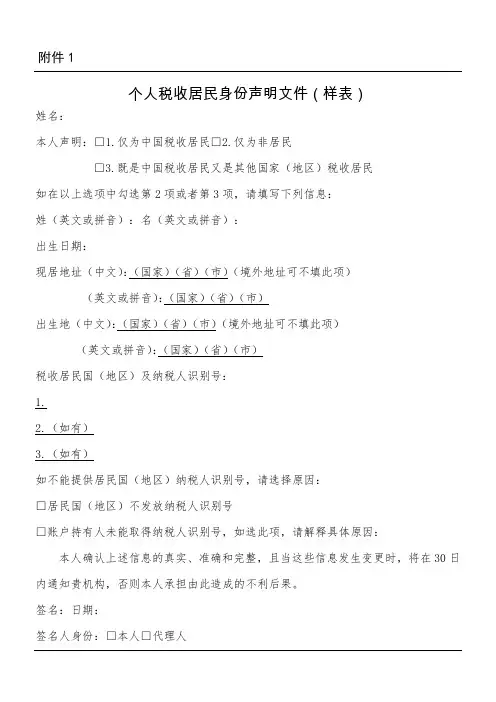
个人税收居民身份声明文件样表
附件1
个人税收居民身份声明文件(样表)
姓名:
本人声明:□1.仅为中国税收居民□2.仅为非居民
□3.既是中国税收居民又是其他国家(地区)税收居民
如在以上选项中勾选第2项或者第3项,请填写下列信息:
姓(英文或拼音):名(英文或拼音):
出生日期:
现居地址(中文):(国家)(省)(市)(境外地址可不填此项)
(英文或拼音):(国家)(省)(市)
出生地(中文):(国家)(省)(市)(境外地址可不填此项)
(英文或拼音):(国家)(省)(市)
税收居民国(地区)及纳税人识别号:
1.
2.(如有)
3.(如有)
如不能提供居民国(地区)纳税人识别号,请选择原因:
□居民国(地区)不发放纳税人识别号
□账户持有人未能取得纳税人识别号,如选此项,请解释具体原因:本人确认上述信息的真实、准确和完整,且当这些信息发生变更时,将在30日内通知贵机构,否则本人承担由此造成的不利后果。
签名:日期:
签名人身份:□本人□代理人
说明:
1.本表所称中国税收居民是指在中国境内有住所,或者无住所而在境内居住满一年
的个人。
在中国境内有住所是指因户籍、家庭、经济利益关系而在中国境内习惯性居住。
在境内居住满一年,是指在一个纳税年度中在中国境内居住365日。
临时离境的,不扣减日数。
临时离境,是指在一个纳税年度中一次不超过30日或者多次累计不超过90日的离境。
2.本表所称非居民是指中国税收居民以外的个人。
其他国家(地区)税收居民身份
认定规则/aeoi_index.html)。
3.军人、武装警察无需填写此声明文件。
非居民机构税收居民身份声明文件(样表).doc

存款机构指在日常经营活动中吸收存款的机构;(2)托管机构是指近三个会计年度总 收入的 20%以上来源于为客户持有金融资产的机构,机构成立不满三年的,按机构存续 期间计算;(3)投资机构是指符合以下条件之一的机构:A.近三个会计年度总收入的 50%以上收入来源于为客户投资、运作金融资产的机构,机构成立不满三年的,按机构 存续期间计算;B.近三个会计年度总收入的 50%以上收入来源于投资、再投资或者买卖 金融资产,且由存款机构、托管机构、特定保险机构或者 A 项所述投资机构进行管理并 作出投资决策的机构,机构成立不满三年的,按机构存续期间计算;C.证券投资基金、 私募投资基金等以投资、再投资或者买卖金融资产为目的而设立的投资实体。(4)特 定的保险机构指开展有现金价值的保险或者年金业务的机构。本办法所称保险机构是指 上一公历年度内,保险、再保险和年金合同的收入占总收入比重 50%以上的机构,或者 在上一公历年度末拥有的保险、再保险和年金合同的资产占总资产比重 50%以上的机 构。 4. 消极非金融机构是指:(1)上一公历年度内,股息、利息、租金、特许权使用费(由 贸易或者其他实质经营活动产生的租金和特许权使用费除外)以及据以产生前述收入的 金融资产转让收入占总收入比重 50%以上的非金融机构;(2)上一公历年度末拥有的 可以产生上述收入的金融资产占总资产比重 50%以上的非金融机构,可依据经审计的财 务报表进行确认;(3)税收居民国(地区)不实施金融账户涉税信息自动交换标准的
□ 账户持有人未能取得纳税人识别号,如选此项,请解释具体原因:
五、本人确认上述信息的真实、准确和完整,且当这些信息发生变更时,将在 30 日内通知
贵机构,否则本人承担由此造成的不利后果。
签名:
日期:
(签名人身份须为机构授权人)
《中华人民共和国非居民企业所得税年度纳税申报表(2019年版)》及填报说明.doc

六、实际应纳所得税额(28+29-30-31)
33
减:本年累计实际已缴纳的所得税额
34
七、本年应补(退)所得税额(32-33)
汇总纳税税款分配
35
主要机构、场所填报
本机构、场所本年应分摊所得税额(36+37+38)
36
其中:主要机构、场所直接分摊所得税额
37
主要机构、场所财政集中分配所得税额
38
2.第1行“利润总额”:填报当期财务会计报表中的利润总额。
3.第2行“境外所得”:填报纳税人当期取得的发生在境外但与境内机构、场所有实际联系的所得数额。当期为境外盈利的,以正数表示;当期为境外亏损的,以负数表示。
4.第3行“纳税调整增加额”:填报纳税人会计处理与税收规定不一致,进行纳税调整增加的数额。本行根据《纳税调整项目明细表》(表F210)“调增数额”列填报。
行次
项目
据实计算
申报金额
核定征收
申报金额
1
一、利润总额
2
减:境外所得
3
加:纳税调整增加额(填报F210)
4
减:纳税调整减少额(填报F210)
5
减:免税、减计收入及加计扣除
6
其中:项目①(减免性质代码)
7
项目②(减免性质代码)
8
项目③(减免性质代码)
9
项目④(减免性质代码)
10
项目⑤(减免性质代码)
11
主要机构、场所从事主体生产经营业务分摊所得税额
39
减:本机构、场所本年累计实际已缴纳的所得税额
40
本机构、场所本年应补(退)所得税额(35-39)
41
其他机构、场所填报
《非居民纳税人享受协定待遇信息报告表》(附填表说明)

【分类索引】 业务部门 国际税务司 业务类别 自主办理事项 表单类型 纳税人填报 设置依据(表单来源) 政策规定表单 【政策依据】 《国家税务总局关于发布<非居民纳税人享受协定待遇管理办法>的公告》(国家税务总局公告2019年第35号) 【表单】
contracting jurisdiction to prove the residence status of
non-resident taxpayer for the year or its previous year during which
the payment is received
14.享受协定待遇所得金额 Amount of the income with respect to which tax treaty benefits are claimed
11.享受协定名称 The applicable treaty
8.在居民国(地区) 的联系电话 Telephone number in resident jurisdiction 10.电子邮箱 E-mail address 12.适用协定条款名 称 Applicable articles of the treaty
17.我谨声明:根据缔约对方法律法规和税收协定居民条款,我为缔约对方税收居民,相关安排 和交易的主要目的不是为了获取税收协定待遇。我自行判断符合协定待遇条件,自行享受协定待 遇,承担相应法律责任。我将按规定归集和留存相关资料备查,接受税务机关后续管理。 I hereby declare: According to the laws, regulations of the other contracting jurisdiction and the article of resident of the tax treaty, I am a resident of the other contracting jurisdiction, the principal purpose of the relevant arrangement and transaction is not to obtain tax treaty benefits. Through self-assessment, I believe that I am in conformity with the conditions for claiming tax treaty benefits, so I will enjoy tax treaty benefits. Therefore, I take due legal responsibilities. I will collect and retain relevant materials for review in accordance with the regulations, and accept the follow-up administration of the tax authority.
A03058《非居民纳税人享受税收协定待遇情况报告表(个人所得税C表)》(填写样例)

A03058《非居民纳税人享受税收协定待遇情况报告表(个人所得税C 表)》非居民纳税人享受税收协定待遇情况报告表(个人所得税C表)Reporting Form for Non-resident Taxpayer Claiming Tax TreatyBenefits(Form C for Individual Income Tax)(享受税收协定财产收益、其他所得条款待遇适用)(Applicable to Tax Treaty Benefits under the Articles of CapitalGains or Other Income)填表日期:20XX年X月X日Filling date: Y M D 货币单位:元人民币Currency unit: RMB〇自行申报〇扣缴申报〇退税Self-declaration Withholding declaration Tax refund(据实勾选)一、扣缴义务人基本信息I. Basic Information of Withholding Agent扣缴义务人名称Name of withholding agent XX市XX公司扣缴义务人纳税人识别号Taxidentificationnumber ofwithholdingagent9144XXXXXXXXXXXXXX二、非居民纳税人基本信息II. Basic Information of Non-resident Taxpayer非居民纳税人中文名称Chinese name ofnon-resident taxpayer XXX非居民纳税人在居民国(地区)姓名Name ofnon-residenttaxpayer inresident state(region)XXXXXX非居民纳税人身份证件类型Type of ID certificate 护照/......非居民纳税人身份证件号码Number of IDcertificateXXXXXX非居民纳税人享受税收协定名称Name of theapplicabletax treatyXXXXXX 享受税收协定待遇条款Name of the applicable article○财产收益○其他所得Capital gains Other income (据实勾选)三、享受财产收益条款待遇(扣缴义务人使用信息)III. Claiming Tax Treaty Benefits under the Article of Capital Gains (Information for Use by Withholding Agent)请选择所转让财产类型(据实勾选)Please select the type of alienated property(1)□位于中国的不动产Immovable property situated in China(2)□非居民纳税人设在中国的常设机构或固定基地营业财产部分的动产Movable property forming part of the property of a non-resident taxpayer's permanent establishment or fixed base in China(3)□从事国际运输(海运、空运、陆运)的船舶、飞机、陆运车辆、国际运输中使用的集装箱,或属于经营上述船舶、飞机、陆运车辆、集装箱的动产Ships, aircraft or land vehicles operated in the international traffic (marine traffic, air traffic or land traffic), containers used in the international traffic, or movable property pertaining to the operation of such ships, aircrafts, land vehicles or containers(4)□公司股份、参股或其他权利取得的利益Shares, participation or other rights in the capital of a company (5)□合伙企业或信托中的利益Interests in a partnership or trust(6)□其他财产Other type of property(一)转让从事国际运输(海运、空运、陆运)的船舶、飞机、陆运车辆、国际运输中使用的集装箱,或属于经营上述船舶、飞机、陆运车辆、集装箱的动产(I) Alienation of Ships, Aircraft or Land Vehicles Operated in the International Traffic (Marine Traffic, Air Traffic or Land Traffic) , Containers Used in the International Traffic, or Movable Property Pertaining to the Operation of Such Ships, Aircraft, Land Vehicles or Containers1.请说明所转让财产具体类型Please indicate the specific type ofalienated propertyXXX(如实填写)(二)转让公司股份、参股或其他权利取得的利益(II) Alienation of Shares, Participation or Other Rights in the Capital of a Company2.被转让公司股份是否为证券交易所上市的股票?Are the alienated shares listed in stock exchanges?□是请填写具体上市信息 Yes. Please fill in specific information of listing status□否 No (据实勾选)证券交易所名称Name of stock exchange XXXXX上市股票代码Stock codeXXXXX3.被转让公司的财产的不动产构成情况Composition of immovable property in assets of the alienated company(1)被转让公司直接持有位于中国的不动产占总资产比例Percentage of immovable property which is situatedin China and directly owned by the alienated company inits total assetsXX%(2)被转让公司直接或间接持有位于中国的不动产占总资产比例Percentage of immovable property which is situatedXX%in China and directly or indirectly owned by the alienated company in its total assets(3)在转让之前的36个公历月份内(不含转让当月)是否曾出现被转让公司直接或间接持有位于中国的不动产价值占公司全部财产价值的比率在50%以上的情况?Is the immovable property which is situated in China and directly or indirectly held by the alienated company of at least 50% of the total asset, at any time during the 36 month period preceding such alienation (excluding the month of alienation)?□是 Yes □否 No (据实勾选)4.持有被转让公司股份情况Information of shareholdings in the alienated company directly or indirectly owned by the non-resident taxpayer(1)转让前直接持股比例Percentage of direct shareholdings before thealienationXX%(2)转让后直接持股比例Percentage of direct shareholdings after thealienationXX%(3)转让前,非居民纳税人是否有通过其他名义参与人持有被转让公司股份,且非居民纳税人对该股份享有排他性资本参与利益,并实质承担资本参与风险?Before the alienation, does the non-resident taxpayer hold any share in the alienated company through other nominee participants, having exclusive participating interests and taking substantial participating risks?□是 Yes □否 No (据实勾选)(4)转让前,非居民纳税人是否通过具有10%以上(含10%)直接资本关系的单层或多层公司或其他实体间接参与该被转让公司的资本?Before the alienation, does the non-resident taxpayer indirectly participate in any capital of the alienated company via one or multiple tier companies or other entities within which it owns a direct capital participation of 10% or above?□是 Yes □否 No (据实勾选)(5)转让前,与非居民纳税人具有显著利益关系的关联集团内其他成员,是否在该被转让公司直接参与或者通过具有10%以上(含10%)直接资本的单层或多层公司或其他实体间接参与该被转让公司的资本?Before the alienation, does a related party which has a substantial interest in or connection with thenon-resident taxpayer indirectly participate in the capital of the alienated company via one or multiple tier□是 Yes □否 No (据实勾选)companies or other entities which it owns direct capitalparticipation of 10% or above?(6)转让前关联集团持股合计比例Total percentage of shareholdings owned by the groupcomprised of qualified related parties before thealienation计算公式:所求比例=(1)直接持股比例+(3)通过其他名义参与人持股比例+(4)通过其他公司或实体间接持股比例+(5)关联集团内其他成员直接或间接持股比例Calculation formula: Total percentage = (1) Percentage ofdirect shareholdings + (3)Percentage of indirectshareholdings via other nominee participants + (4)Percentage of indirect shareholdings via other qualifiedcompanies and entities + (5) Percentage of direct orindirect shareholdings owned by qualified related partiesXX%*(7)如果关联集团合计持股比例低于25%(不含25%),转让行为发生前12个月内关联集团持股比例是否曾经达到25%或以上(含25%)?If the total percentage of shareholdings owned by the group comprised of qualified related parties before the alienation is less than 25% (excluding 25%), does such percentage ever reach 25% or more (including 25%) at any time during the 12 month period preceding the alienation?□是 Yes □否 No (据实勾选)(三)转让合伙企业或信托中的利益(III) Alienation of Interests in a Partnership or Trust5.被转让合伙企业或信托的财产的不动产构成情况Composition of immovable property in assets of the alienated partnership or trust (1)被转让合伙企业或信托直接持有位于中国的不动产占总资产比例Percentage of immovable property which is situatedin China and directly owned by the alienated partnershipor trust in its total assetsXX%(2)被转让合伙企业或信托直接或间接持有位于中国的不动产占总资产比例Percentage of immovable property which is situatedin China and directly or indirectly owned by the alienatedpartnership or trust in its total assetsXX%(3)在转让之前的36个公历月份内(不含转让当月)是否曾出现被转让合伙企业或信托直接或间接持有位于中国的不动产价值占合伙企业或信托全部财产价值的比率在50%以上的情况?Is the immovable property which is situated in China and directly or indirectly held by the alienated partnership or trust of at least 50% of the its total asset, at any time during the 36 month period preceding such alienation (excluding the month of alienation)?□是 Yes □否 No (据实勾选)(四)转让其他财产(IV) Alienation of Other Type of Property6.请简要说明“其他财产”的具体类型Please briefly indicate the specific type of property.XXX(如实填写)(五)其他信息(V) Other Information7.请简要说明非居民纳税人认为应享受财产收益条款税收协定待遇的其他法律依据、事实情况或理由Please briefly indicate other legal basis, facts or reasons provided by thenon-resident taxpayer to support the non-resident taxpayer's claiming for tax treaty benefits under article of capital gains.8.享受财产收益条款收入总额Total amount of income under tax treaty treatment ofthe article of capital gainsXXX.XX成本费用扣除总额Total amount of deductible costs and expensesXXX.XX享受财产收益条款减免税额Total amount of tax reduction or exemption under taxtreaty treatment of the article of capital gainsXXX.XX四、享受财产收益条款待遇(税务机关管理使用信息)IV. Claiming Tax Treaty Benefits under the Article of Capital Gains (Information for Use by Tax Authorities)9.非居民纳税人的居民国(地区)对此项财产收益所得所征所得税税率(免税或不征税请填"0")Applicable income tax rate for this capital gain incomein the resident state (region) of the non-residenttaxpayer (Please fill in "0" for the case of tax exemptionor non-taxation)XX%*10.非居民纳税人持股情况具体信息Detailed information on shareholdings owned by the non-resident taxpayer(1)第4题(3)中所述其他名义参与人信息Information of the other nominee participants referred in item 3 of Question 4序号No. 名称Name持有被转让公司股份比例Percentage ofshareholdingsin thealienatedcompany居民国(地区)Residentstate(region)与非居民纳税人关系Relationship with thenon-resident taxpayer1 XXX XX%XX国(地区)XXX2 ……3(2)第4题(4)中所述公司或其他实体信息Information of the companies and other entities referred in item 4 of Question 4序号No. 名称Name持有被转让公司股份比例Percentage ofshareholdingsin thealienatedcompany非居民纳税人通过该公司或其他实体持有被转让公司股份比例Percentage ofshareholdings inalienated company ownedby the non-residenttaxpayer via othercompanies or entities居民国(地区)Resident state(region)1 XXX公司XX%XX%XX国(地区)2 ……3(3)第4题(5)中所述关联集团内其他成员信息Information of related parties referred in item 5 of Question 4序号No. 名称Name持有被转让公司股份比例Percentage ofshareholdingsin thealienatedcompany居民国(地区)Residentstate(region)与非居民纳税人关系Relationship with thenon-resident taxpayer1 XXX XX%XX国(地区)XXX2 ……3*11.转让行为前的12个月非居民纳税人直接或间接持股比例变化情况The changes of shareholding ratio directly or indirectly owned by the non-resident taxpayer, at any time during 12 month period preceding the alienation序号No.持股人名称Name ofshareholders持股比例变化时间Time ofpercentagechange变化前持股人持股比例Percentagebeforechanging变化后持股人持股比例Percentageafterchanging关联集团持股比例合计Totalpercentage ofshareholdingsowned by thegroup comprisedof qualifiedrelated parties1 XXX20XX年X月X日XX%XX%XX%2 ……312.非居民纳税人近三年是否有来源于中国境内其他地区的同类所得?Has the non-resident taxpayer received any income of the same type sourced in other regions within China over the past three years?□是 Yes □否 No (据实勾选)*13.非居民纳税人近三年是否就来源于中国境内其他地区的同类所得享受过税收协定待遇?Has the non-resident taxpayer claimed tax treaty benefits for the income of the same type sourced in other regions within China over the past three years?□是 Yes □否 No (据实勾选)*14.请说明非居民纳税人近三年就来源于中国境内其他地区的同类所得享受税收协定待遇的情况 Please indicate the details of any tax treaty benefits claimed by the non-resident taxpayer for the same type of income sourced in other regions within China over the past three years.主管税务机关In-charge tax authority 时间(年份)Time (year)所得金额Amount of income减免税金额Amount of taxreduction orexemption(1)20XX年X月X日XXX.XX XXX.XX (2)……(3)(4)(5)五、享受其他所得条款待遇V. Claiming Tax Treaty Benefits under the Article of Other Income特别提示:只有其他税收协定条款皆不适用时,才能适用“其他所得”条款。
非居民纳税人享受税收协定待遇情况报告表(个人所得税A表)
金额: Amount:
币种: Currency:
*3.贷款资金是否存在以下情况 Do any of the following circumstances apply in respect of the loaned monies?
(1)□ 由税收协定缔约对方符合条件的政府或机构间接提供资金 The loaned monies are indirectly provided by government or institution of the other tax treaty contracting party in
■ 是 Yes □ 否 No
(3)非居民纳税人据以取得该项所得的有关权利或财产是否为获得税收协
定的减免税利益而安排? With respect to the property or rights from which the non-resident taxpayer
derives the income, have arrangements been made in such a way so as to gain
which such insured loans qualify for benefits under the terms of the treaty
*4.如贷款资金由税收协定缔约对方符合条件的政府或机构间接提供资金 、担保或保险,请填写符合条件的政府或机构全称
Please provide the full name of the qualified government or institution if loans/funds, a guarantee or insurance are indirectly provided by a qualified government or institution of the other tax treaty contracting party
非居民纳税人享受税收协定待遇情况报告表(个人所得税D表)以及填报说明
Yes. Please indicate the specific type
aircraft or land vehicle operated in international traffic by an enterprise of the other of the traffic vehicle
Contracting State?
非居民纳税人享受税收协定待遇情况报告表(个人所得税D表)
Reporting Form for Non-resident Taxpayer Claiming Tax Treaty Benefits (Form D for Individual Income Tax)
(享受非独立个人劳务、演艺人员和运动员、退休金、政府服务、 教师和研究人员、学生条款,或国际运输协定待遇适用)
7.非居民纳税人从事的活动属于以下哪种情况
Type of activities exercised by the non-resident taxpayer
(1)□政府间文化交流计划
Cultural exchange program agreed upon by the governments of both Contracting States
(2)□ 由中国政府资金或公共资金资助 请说明资助者名称 Substantially supported by Government of China, or its public funds Please indicate the name of the sponsor
(3)□其他 Other cases
system or public welfare plan?
11.非居民纳税人在中国居住或计划居住时间 Actual or estimated residence period in China of the non-resident taxpayer
非居民纳税人税收居民身份信息报告表(个人适用)
(个人适用)
Information Reporting Form of Tax Residence Status of Non-resident Taxpayer (For Individuals)
○ 自行申报 Self-declaration
填报日期: 年 月 日
Tax identification number of withholding agent
二、非居民纳税人基本信息 II. Basic Information of Non-resident Taxpayer
非居民纳税人中文姓名 Chinese name of nonresident taxpayer
Filling date: Y M D
○ 扣缴申报 Withholding declaration
○ 退税 Tax refund
一、扣缴义务人基本信息 I.Basic Information of Withholding Agent
扣缴义务人名称 Name of withholding agent
扣缴义务人纳税人识别 号
domicile in China, the individual has lived in China for one year. According to such
provision, is the taxpayer a tax resident of China?
5、非居民纳税人在中国境内是否有住所? Does the non-resident taxpayer have a domicile in China?
非居民纳税人签章或签字 Seal or signature of the non-resident taxpayer
《非居民纳税人享受税收协定待遇情况报告表(个人所得税A表)》
非居民纳税人享受税收协定待遇情况报告表(个人所得税A 表)Reporting Form for Non-resident Taxpayer Claiming Tax Treaty Benefits(Form A for Individual Income Tax)(享受税收协定股息、利息、特许权使用费条款待遇适用)(Applicable to Tax Treaty Benefits under Articles of Dividends, Interest or Royalties)填表日期: 年 月 日Filling date: Y M D货币单位:元人民币Currency unit: RMB〇 自行申报 〇 扣缴申报 〇 退税 Self-declaration Withholding declar tion国家税务总局监制【表单说明】一、本表适用于取得来源于我国的股息、利息、特许权使用费所得,需享受我国对外签署的避免双重征税协定(含与港澳避免双重征税安排)中的股息、利息、特许权使用费条款的税收协定待遇的个人所得税非居民纳税人。
I. This form is applicable to non-resident individual income taxpayer who receives dividends, interest or royalties sourced in China, and claims tax treaty benefits under the article of dividends, interest or royalties of a Double Taxation Agreement (DTA) signed by China (including the DTAs with Hong Kong and Macau Special Administrative Regions).二、本表可用于自行申报或扣缴申报,也可用于非居民纳税人申请退税。