
芬斯特拉版《国际宏观经济学》课后习题答案第4章
Exchange Rates II: The Asset Approach in the Short Rune the money market and FX diagrams to answer the following questions about therelationship between the British pound (£) and the U.S. dollar ($). The exchange rate is in U.S. dollars per British pound, E $/£. W e want to consider how a change in the U.S. money supply affects interest rates and exchange rates. On all graphs, label the initial equilibrium point A.a.Illustrate how a temporary decrease in the U.S. money supply affects the moneyand FX markets. Label your short-run equilibrium point B and your long-run equilibrium point C .Answer:See the diagram below.S-23i $i 1$i 2$2$DR 1DR2E 1E E $/£M 1US P 1US M 2US P 1USing your diagram from (a), state how each of the following variables changesin the short run (increase/decrease/no change): U.S. interest rate, British interestrate, E $/£, E e $/£, and the U.S. price level.Answer: The U.S. interest rate increases, the British interest rate does notchange, E $/£decreases, E e $/£does not change, and the U.S. price level does notchange.ing your diagram from (a), state how each of the following variables changesin the long run (increase/decrease/no change relative to their initial values atpoint A ): U.S. interest rate, British interest rate, E $/£, E e $/£, and U.S. price level.Answer:All of the variables return to their initial values in the long run. This isbecause the shock is temporary, implying the central bank will increase themoney supply from M 2to M 1in the long run.e the money market and FX diagrams from (a) to answer the following questions.This question considers the relationship between the Indian rupees (Rs) and the U.S.dollar ($). The exchange rate is in rupees per dollar, E Rs /$. On all graphs, label the ini-tial equilibrium point A .a.Illustrate how a permanent increase in India’s money supply affects the money andFX markets. Label your short-run equilibrium point B and your long-run equi-librium point C .Answer:See the following diagram. Thick arrows indicate temporary movementwhile thinner ones indicate the movements in the long run. In the short run,prices are fixed. Therefore the real money supply changes from MS 1to MS 2, thustemporarily lowering the domestic interest rate. In the long run, as prices rise,the real money supply and interest rate return to their original level. In the for-eign exchange market, FR shifts to the right and stays there permanently becauseof an expected depreciation of rupees.S-24Solutions ■Chapter 4(15) Exchange Rates II: The Asset Approach in the Short Runi Rs i 1Rs i 2Rs1Rs2Rs12E 1E 2E 3M 2INP 2IN E Rs/$M 1IN P 1IN M 2IN P 1INb. By plotting them on a chart with time on the horizontal axis, illustrate how eachof the following variables changes over time (for India): nominal money supply M IN , price level P IN , real money supply M IN /P IN , India’s interest rate i Rs , and the exchange rate E Rs /$.Answer:See the following diagrams.ing your previous analysis, state how each of the following variables changesin the short run (increase/decrease/no change): India’s interest rate i Rs , E Rs/$E e Rs/$,and India’s price level P IN .Answer: India’s interest rate decreases, the U.S. interest rate remains unchanged,E Rs /$increases, E e Rs /$increases, and India’s price level remains unchanged.ing your previous analysis, state how each of the following variables changesin the long run (increase/decrease/no change relative to their initial values atpoint A ): India’s interest rate i Rs , E Rs/$E e Rs/$, India’s price level P IN .Answer: India’s interest rate remains unchanged, the U.S. interest rate remainsunchanged, E Rs /$increases, E e Rs /$increases (remains unchanged in transition fromshort to long run), India’s price level increases.e.Explain how overshooting applies to this situation.Answer:The short-run exchange rate overshoots its long-run value, E E as in the text Figure 4-13 (15-13). W e can see this in the impulse response diagrams shown previously. The overshooting is caused by the investors’ adjustment of exchange rate expectations coupled with lower domestic interest rates. Since the rupees in-terest rate falls, investors must be compensated by a rupee appreciation for UIP with U.S. interest rate to hold. For a rupee appreciation to be possible, it must depreciate more in the short run than its longer-run value.Solutions ■Chapter 4(15) Exchange Rates II: The Asset Approach in the Short Run S-25M IN P IN i RsT T nE Rs/$M IN /P IN M IN /P IN11223.Is overshooting (in theory and in practice) consistent with purchasing power parity?Consider the reasons for the usefulness of PPP in the short run versus the long run and the assumption we’ve used in the asset approach (in the short run versus the long run). How does overshooting help to resolve the empirical behavior of exchange rates in the short run versus the long run?Answer:Y es, overshooting is consistent with PPP. Investors forecast the expected ex-change rate based on the theory of PPP.When there is some change in the market, the investors know the exchange rate will change to equate relative prices in the long run.This is why we observe overshooting in the short run—the investors incorporate this information into their short-run forecasts. Exchange rates are volatile in the short run.The theory’s implication that there is exchange rate overshooting (in response to per-manent shocks) is one explanation for short-run volatility in exchange rates.e the money market and foreign exchange (FX) diagrams to answer the followingquestions. This question considers the relationship between the euro (€) and the U.S.dollar ($). The exchange rate is in U.S. dollars per euro, E$/€. Suppose that with fi-nancial innovation in the United States, real money demand in the United States de-creases. On all graphs, label the initial equilibrium point A.a.Assume this change in U.S. real money demand is temporary. Using the FX andmoney market diagrams, illustrate how this change affects the money and FXmarkets. Label your short-run equilibrium point B and your long-run equilib-rium point C.Answer: See the following diagram. The long-run values are the same as the ini-tial values because the shock is temporary. Also because the shock is temporary,we assume that the reversal of real money demand occurs before the price leveladjusts—that is, MD returns from MD2to MD1before the price level changes. S-26Solutions ■Chapter 4(15) Exchange Rates II: The Asset Approach in the Short Run i$i1$i2 $i1$i2$1E1M1US / P1US E2E$/€b.Assume this change in U.S. real money demand is permanent. Using a new dia-gram, illustrate how this change affects the money and FX markets. Label your short-run equilibrium point B and your long-run equilibrium point C.Answer:See the following diagram. In the long run, the price level will have to increase to adjust for the drop in real money demand (assuming the central bank does not change the money supply, M). That is, the nominal interest rate returns to its initial value in the long run. This requires that the price level increase to reduce real money supply. The drop in real money demand will have to be met one-for-one with a drop in real money supply (generated by an increase in the price level). In this case, the expected exchange rate changes because the shock is permanent. Therefore, FR schedule in the forex market also shifts upward.Solutions ■Chapter 4(15) Exchange Rates II: The Asset Approach in the Short RunS-27i 1$i 2$1E 1E 2E 3E $/€i $i 1$i 2$M 1US / P 1US M 1US / P 2US 2c.Illustrate how each of the following variables changes over time in response to apermanent reduction in real money demand: nominal money supply M US , price level P US , real money supply M US /P US , U.S. interest rate i $, and the exchange rate E $/€.Answer:See the following diagrams.M US P US i $T T nE $/⑀M US /P US M US /P US22115.This question considers how the FX market will respond to changes in monetarypolicy. For these questions, define the exchange rate as Korean won per Japanese yen,E WON /¥. Use the FX and money market diagrams to answer the following questions.On all graphs, label the initial equilibrium point A .a.Suppose the Bank of Korea permanently decreases its money supply. Illustrate theshort-run (label the equilibrium point B ) and long-run effects (label the equilib-rium point C ) of this policy.Answer:See the following diagram. In the short run, prices are fixed. Thereforethe real money supply changes from MS 1to MS 2, thus temporarily raising the Ko-rean interest rate. In the long run, as prices fall, the real money supply and interestrate return to their original levels. In the foreign exchange market, FR shifts to theleft and stays there permanently because of an expected appreciation of won.S-28Solutions ■Chapter 4(15) Exchange Rates II: The Asset Approach in the Short Runi won i 1won i 2won1won2wonM 1K / P 1K M 2K / P 2K M 2K / P 1K 1E 1E 3E 2E won/¥2b.Now , suppose the Bank of Korea announces it plans to permanently decrease itsmoney supply but doesn’t actually implement this policy . How will this affect theFX market in the short run if investors believe the Bank of Korea’s announcement?Answer:See the following diagram. I n this case, interest rates on won-denominated deposits don’t change because the Bank of Korea doesn’t cut themoney supply. However, because investors expected the Bank of Korea to cut themoney supply, they expect the won will appreciate relative to the yen, causing adecrease in the return on yen-denominated deposits in the short run. Notice theresulting change in the exchange rate is relatively small (compared with the dra-matic decrease we see in [a]).i won i 1won M 1K / P 1K DR 1E 1E 2E won/¥c.Finally, suppose the Bank of Korea permanently decreases its money supply butthis change is not anticipated. When the Bank of Korea implements this policy,how will this affect the FX market in the short run?Answer:In this case, the expected exchange rate is unchanged because the in-vestors didn’t expect the decrease in the money supply.Solutions ■Chapter 4(15) Exchange Rates II: The Asset Approach in the Short RunS-29i won i 1won i 2won 2won1wonM 1K / P 1K M 2K / P 1K DR 1DR E 1E 2E won/¥ing your previous answers, evaluate the following statements:i.If a country wants to increase the value of its currency, it can do so (tem-porarily) without raising domestic interest rates.ii.The central bank can reduce both the domestic price level and the value ofits currency in the long run.iii.The most effective way to increase the value of a currency is through sur-prising investors.Answer: Though it is theoretically possible, as shown in (b), it is not a good pol-icy because it is bad for the policy makers reputation in the long run.i.True; shown in (b).ii.False; shown in (a) A reduction in price level implies an exchange rate ap-preciation by PPP .iii.False; shown in (b) and (c) compared with (a). The most dramatic appreci-ation in the won occurs when the reduction in M is coupled with investorsanticipating the appreciation in the won. In general, a policy must be cred-ible for it to have an effect in the long run.6.In the late 1990s, several East Asian countries used limited flexibility or currency pegsin managing their exchange rates relative to the U.S. dollar. This question considers how different countries responded to the East Asian Currency Crisis (1997–1998).For the following questions, treat the East Asian country as the home country and the United States as the foreign country. Also, for the diagrams, you may assume these countries maintained a currency peg (fixed rate) relative to the U.S. dollar. Also, for the following questions, you need consider only the short-run effects.a.In July 1997, investors expected that the Thai baht would depreciate. That is, theyexpected that Thailand’s central bank would be unable to maintain the currency peg with the U.S. dollar. Illustrate how this change in investors’ expectations af-fects the Thai money market and the FX market, with the exchange rate defined as baht (B) per U.S. dollar, denoted E B/$. Assume the Thai central bank wants to maintain capital mobility and preserve the level of its interest rate and abandons the currency peg in favor of a floating exchange rate regime.Answer:If Thailand is willing to let its currency float against the dollar, thenThailand’s central bank can maintain monetary policy autonomy and interna-tional capital mobility. See the following diagram:S-30Solutions ■Chapter 4(15) Exchange Rates II: The Asset Approach in the Short Runi baht i 1bahtM 1T / P 1T ERDR 12E 1E 2E baht/$b.I ndonesia faced the same constraints as Thailand—investors feared I ndonesiawould be forced to abandon its currency peg. Illustrate how this change in in-vestors’ expectations affects the Indonesian money market and the FX market,with the exchange rate defined as rupiahs (Rp) per U.S. dollar, denoted E Rp /$. As-sume the Indonesian central bank wants to maintain capital mobility and the cur-rency peg.Answer: If Indonesia wants to maintain the currency peg against the dollar andmaintain international capital mobility, it will have to give up monetary policyautonomy. In this case, Indonesia has to increase the domestic interest rate to keepinvestors from dumping their rupiah-denominated deposits for U.S. dollars andmove their investments out of Indonesia (this would then cause a depreciation inthe rupiah).i rup i 1rup i 2rup 1rup 2rupM 1I / P 1I M 2I / P 1I 12FR E 1E rupiah/$2c.Malaysia had a similar experience, except that it used capital controls to maintainits currency peg and preserve the level of its interest rate. Illustrate how this change in investors’ expectations affects the Malaysian money market and the FX market,with the exchange rate defined as ringgit (RM) per U.S. dollar, denoted E RM/$. Y ou need show only the short-run effects of this change in investors’ expectations.Answer:See the following diagram. In the absence of capital controls Malaysian interest rate would have to rise. However, by preventing investors from taking ad-vantage of arbitrage, Malaysia creates a disequilibrium. The investors require i 2RM to keep their deposits in Malaysia, but they only receive i 1RM . Because of the cap-ital controls imposed by Malaysia, investors cannot withdraw their ringgit-denominated deposits (selling ringgit in exchange for dollars in the FX market).n effect, the foreign market equilibrium diagram shown below does notwork/exist. This allows Malaysia to maintain monetary policy autonomy and a fixed exchange rate at the same time.Solutions ■Chapter 4(15) Exchange Rates II: The Asset Approach in the Short RunS-31i RM i 1RM i 2RM 1RM 2RM M 1M / P 1M 12E 1E RM/$pare and contrast the three approaches just outlined. As a policy maker,which would you favor? Explain.Answer: There is no “correct” answer to this question. The cases above highlight the trilemma because each country can choose a different option depending on their domestic or international priorities. They need to compare the benefits of having any two of (a) fixed exchange rates, (b) monetary autonomy, and (c) in-ternational capital mobility against the cost of not having the third one.7.Several countries have opted to join currency unions. Examples include the Euroarea, the CFA franc union in W est Africa, and the Caribbean currency union. This in-volves sacrificing the domestic currency in favor of using a single currency unit in multiple countries. Assuming that once a country joins a currency union it will not leave, do these countries face the policy trilemma discussed in the text? Explain.Answer: These countries do face the trilemma because they are committed to main-taining the first policy goal of a fixed exchange rate. Joining a currency union effec-tively means a country has a fixed exchange rate without the need for government intervention because the money supply is controlled by a regional central bank for member countries. This effectively reduces the choice to a dilemma between mone-tary policy autonomy versus international capital mobility. T ypically, countries that are parts of a currency union sacrifice monetary policy autonomy; policy decisions are made jointly rather than independently.S-32Solutions ■Chapter 4(15) Exchange Rates II: The Asset Approach in the Short Run8.During the Great Depression, the United States remained on the international goldstandard longer than other countries. This effectively meant that the United States wascommitted to maintaining a fixed exchange rate at the onset of the Great Depression.The U.S. dollar was pegged to the value of gold along with other major currencies,including the British pound, the French franc, and so on. Many researchers haveblamed the severity of the Great Depression on the Federal Reserve and its failure toreact to economic conditions in 1929 and 1930. Discuss how the policy trilemma ap-plies to this situation.Answer: The United States was committed to the fixed exchange rate with gold;consequently, policy makers had to sacrifice either monetary policy autonomy or cap-ital mobility, just as the trilemma suggests. Based on the information given in thequestion, we can assume that the policy did not respond to the U.S. business cycle(policy makers did not exercise monetary policy autonomy). Thus, if we assume in-ternational capital mobility, the United States could not react to the business cyclewith a monetary expansion until it abandoned the gold standard.9.On June 20, 2007, John Authers, investment editor of the Financial Times,wrote thefollowing in his column “The Short View”:The Bank of England published minutes showing that only the narrowest pos-sible margin, 5–4, voted down [an interest] rate hike last month. Nobody fore-saw this. . . . The news took sterling back above $1.99, and to a 15-year highagainst the yen.Can you explain the logic of this statement? Interest rates in the United Kingdomhad remained unchanged in the weeks since the vote and were still unchanged afterthe minutes were released. What news was contained in the minutes that causedtraders to react? Use the asset approach.Answer: The news item indicates that investors did not expect the decision to leaveinterest rates unchanged would be divisive. They thought that any increases in inter-est rates would happen further in the future. Higher interest rates would lead to anappreciation in the pound sterling. When the minutes showed that interest rate in-creases were more likely than previously thought, investors came to expect an appre-ciation sooner rather than later. This caused an appreciation in the current spot ex-change rate.10.W e can use the asset approach to both make predictions about how the market willreact to current events and understand how important these events are to investors.Consider the behavior of the Union/Confederate exchange rate during the CivilW ar. How would each of the following events affect the exchange rate, defined as?Confederate dollars per Union dollar, EC$/$a.The Confederacy increases the money supply by 2,900% between July and De-cember of 1861.Answer: The Confederate money supply increases, the exchange rate increases,and the Confederate dollar depreciates.b.The Union Army suffers a defeat in Battle of Chickamauga in September 1863.Answer: Appreciation in the Confederate dollar is expected because a militaryvictory means a stable economy and monetary policy, implying decreased uncer-tainty and risk, the exchange rate decreases, and the Confederate dollar appreci-ates.c.The Confederate Army suffers a major defeat with Sherman’s March in the au-tumn of 1864.Answer: Just the opposite of (b) above: depreciation in the Confederate dollar isexpected because of military defeat increases economic and monetary uncertaintyand risk; the exchange rate increases, and the Confederate dollar depreciates.。
第4章作业题答案,4174

宏观第四章作业答案1题.(a) IS 曲线上的每一点都代表产品市场中的一个均衡。
于是我们可以从商品市场的均衡条件即总收入等于总支出来推导IS 曲线,由给出的第一、二、三、四,四个等式可得: 0.8(10.5)90050800Y C I G Y i =++=×−×+−+⇒0.4170050Y i ×=−(170050)/0.44250125Y i i ⇒=−=−这就是IS 曲线。
(b) IS 曲线表示产品市场均衡时的利率和收入水平的组合。
它描述了利率和收入的反向变动关系,利率下降会导致支出增加,从而厂商的实际产出增加,收入增加。
(c) LM 曲线上的每一点都代表了货币市场的一个均衡。
于是我们可以从货币市场的均衡条件即货币供给等于货币需求来推导LM 曲线,由(P5)(P6)可得:5000.2562.5(50062.5)/0.25ML Y i Y i P=⇒=×−⇒=+ 2000250Y i ⇒=+这就是LM 曲线。
(d) LM 曲线代表了货币市场处于均衡时候的利率与收入水平的组合,即货币供给等于货币需求时候的利率和收入水平的组合。
它描述了利率和收入水平的同向变动关系,收入增加会引起实际货币余额的需求增加,在货币供给不变的情况下,会导致利率的提高,利率的提高又会减少实际货币余额的需求,并使之重新回到原来的需求水平,与货币供给相等。
(e) IS 曲线和LM 曲线的交点代表了收入和利率的均衡水平。
在这个例子中,有:4250125200025037522506IS LM i i i i ∗=⇒−=+⇒=⇒= 4250125425012563500Y i ∗∗=−=−×=即均衡收入水平是3500,均衡利率是6。
(f) 在IS 曲线和LM 曲线的交点处产品市场和货币市场同时处于均衡,在产品市场,自主支出等与实际产出等于总收入,在货币市场,货币供给等于货币需求。
利率和收入都没有进一步改变的倾向。
宏观经济学-第4章习题答案
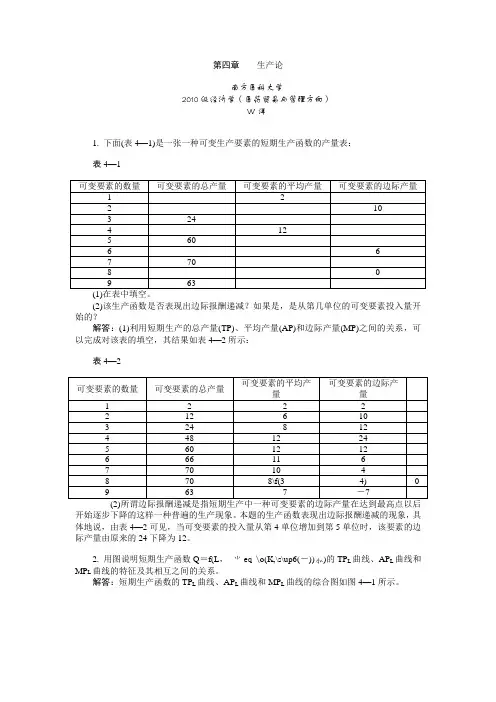
第四章生产论南方医科大学2010级经济学(医药贸易与管理方向)W洋1. 下面(表4—1)是一张一种可变生产要素的短期生产函数的产量表:表4—1(2)该生产函数是否表现出边际报酬递减?如果是,是从第几单位的可变要素投入量开始的?解答:(1)利用短期生产的总产量(TP)、平均产量(AP)和边际产量(MP)之间的关系,可以完成对该表的填空,其结果如表4—2所示:表4—2开始逐步下降的这样一种普遍的生产现象。
本题的生产函数表现出边际报酬递减的现象,具体地说,由表4—2可见,当可变要素的投入量从第4单位增加到第5单位时,该要素的边际产量由原来的24下降为12。
2. 用图说明短期生产函数Q=f(L, eq \o(K,\s\up6(-)) )的TP L曲线、AP L曲线和MP L曲线的特征及其相互之间的关系。
解答:短期生产函数的TP L曲线、AP L曲线和MP L曲线的综合图如图4—1所示。
图4—1由图4—1可见,在短期生产的边际报酬递减规律的作用下,MP L曲线呈现出先上升达到最高点A以后又下降的趋势。
从边际报酬递减规律决定的MP L曲线出发,可以方便地推导出TP L曲线和AP L曲线,并掌握它们各自的特征及相互之间的关系。
关于TP L曲线。
由于MP L= eq \f(d TP L,d L) ,所以,当MP L>0时,TP L曲线是上升的;当MP L<0时,TP L曲线是下降的;而当MP L=0时,TP L曲线达最高点。
换言之,在L =L3时,MP L曲线达到零值的B点与TP L曲线达到最大值的B′点是相互对应的。
此外,在L<L3即MP L>0的范围内,当MP′L>0时,TP L曲线的斜率递增,即TP L曲线以递增的速率上升;当MP′L<0时,TP L曲线的斜率递减,即TP L曲线以递减的速率上升;而当MP′=0时,TP L曲线存在一个拐点,换言之,在L=L1时,MP L曲线斜率为零的A点与TP L曲线的拐点A′是相互对应的。
宏观经济学习题参考答案(部分)

宏观经济学习题参考答案(部分)宏观经济学习题参考答案(部分)本人精心整理的文档,文档来自网络本人仅收藏整理如有错误还请自己查证!宏观经济学习题参考答案(部分)第一章国民收入的核算一、选择题1、D2、C3、A4、C5、B6、B7、A8、E9、C 10、B11、A 12、B 13、E 14、B 15、C16、C 17、A 18、C 19、E 20、C21、C 22、B 23、D 24、D 25、A26、B 27、A二、填空题1. 国民生产总值2. 资本消耗折旧3. 居民厂商政府国际市场4. 用物品和劳务来满足自己需要的行为5. 投资6. 储存不是用于目前消费的收入的行为7. 更新投资净投资8.居民的储蓄厂商的储蓄折旧费不分配的利润9. 增加值10.支出法三、名词解释1.实际国民生产总值是以具有不变购买力的货币单位衡量的国民生产总值国民生产总值通常是以现行货币单位来表现一国在一定时期(通常为一年)内的全部社会最终产品和劳务的总和但由于通货膨胀和通货紧缩会抬高或降低物价因为会使货币的购买力随物价的波动而发生变化为了消除价格变动的影响一般是以某一年为基期以该年的价格为不变价格然后用物价支书来矫正按当年价格计算的国民生产总值而计算出实际国民生产总值2、当前收入中不用于消费的部分即收入减去消费如寸入银行的存款、购买的有价证券、保存在手中的货币等都称为储蓄储蓄包括政府机构储蓄、企业储蓄和个人及家庭储蓄三种国民生产总值(GNP)是以国民原则来核算的国民收入它被定义为经济社会在一定时期(通常是一年)内运用生产要素所生产的全部最终产品的市场价值GNP是一个市场价值概念它测度的是最终产品而不是中间产品的价值是一定时期内所生产而不是所售卖的最终产品价值是流量而不是存量四、计算题(1)按收入法计算GNP得GNP=工资+利息+租金+利润=100+10+30+30=170(2)按支出法计算GNP得GNP=消费+投资+政府支出+(出口-进口)=90+60+30+(60-70)=170(亿元)(3)所得税-转移支付=30-5=25(亿元)所以政府预算赤字=政府支出-政府收入=30-25=5(亿元)(4)家庭将收入分配为消费、储蓄或税收因此收入=消费+储蓄+(税收-转移支付)所以储蓄=收入-消费-(税收-转移支付)=170-90-25=55(亿元)或者由等式(投资-储蓄)+(政府支出-政府收入)+(出口-进口)=0得储蓄=(政府支出-政府收入)+(出口-进口)+投资=5+(60-70)+60=55(亿元)(5)净出口=出口-进口=60-70=-10(亿元)第二章国民收宏观经济学习题参考答案(部分)入的均衡一、选择题1、D2、D3、B4、A5、A6、B7、D二、填空题1. 消费支出可支配收入2. 越大右上方3. 消费支出可支配收入4. 边际消费倾向5. 储蓄可支配收入6. 越多右上方7. 平均储蓄倾向8. 储蓄增量与可支配收入增量之比9. 同反10.自发投资三、名词解释1、消费函数现代西方经济学所谓的消费函数是指消费与决定消费的各种因素之间的依存关系但凯恩斯理论假定在影响消费的各种因素中收入是消费的唯一的决定因素收入的变化决定消费的变化随着收入的增加消费也会增加但是消费的增加不及收入的增加多收入和消费两个经济变量之间的这种关系叫做消费函数或消费倾向2、储蓄函数储蓄与决定储蓄的各种因素之间的依存关系是现代西方经济学的基本分析工具之一由于在研究国民收入决定时假定储蓄只受收入的影响故储蓄函数又可定义为储蓄与收入之间的依存关系四、计算题(1)在C=120+0.75y中令C=1120得y=1333(2)从消费函数知MPC=0.75从而MPS=0.25(3)在C=120+0.75y中令y=3000得C=2370第三章国民收入的变化一、单项选择题1、B2、B3、C4、D5、A6、C7、D8、B9、B二、多项选择题1.AC三、填空题1. 消费支出投资政府支出出口2. 储蓄政府税收进口3. 投资的增加所引起的国民收入增加的倍数1/(1-MPC)4. 具有5. 越大6. 增加支出减少税收增加同量的支出和税收7. 1(1-MPC)MPC/(1-MPC)8. 平衡预算9. 为了达到充分就业的国民收入总支出曲线向上移动的距离10. 为了消除通货膨胀总支出曲线向下移动的距离四、计算题1、(1)由Y=C+I0得Y=8000(亿元)从而C=6500(亿元)S=1500(亿元)I=1500(亿元)(2)因为△I=250(亿元)K=1/(1-MPC)=1/(1-0.75)=4所以△Y=K*△I=4*250=1000(亿元)于是在新的均衡下收入为8000+1000=9000(亿元)相应地C=7250(亿元)S=1750(亿元)(3)若消费函数斜率增大即MPC增大则乘数亦增大反之相反2、(1)可支配收入:Yd=Y-Tn=Y-50消费C=30+0.8(Y-50)=30+0.8Y-40=0.8Y-10均衡收入:Y=C+I+G=0.8Y-10+60+50+50-0.05Y=0.75Y+150得Y=150/0.25 =600......均衡收入(2)净出口余额:NX=50-0.05Y =50-0.05×600=20(3)KI=1/(1-0.8+0.05)宏观经济学习题参考答案(部分)=4(4)投资从60增加到70时Y=C+I+G+NX=0.8Y-10+70+50+50-0.05Y=0.75Y+160 160得Y =150/0.25 =640......均衡收入净出口余额:NX=50-0.05Y=50-0.05×640=50-32=18(5)当净出口函数从NX=50-0.05Y变为X=40-0.05Y时的均衡收入:Y=C+I+G+X=0.8Y-10+60+50+40-0.05Y=0.75Y+140得Y=140/0.25 =560......均衡收入净出口余额NX=40-0.05Y=40-0.05×560=40-28=12(6)自发投资增加10使均衡收入增加40(640-600=40)自发净出口减少10(从NX=50-0.05Y变为NX=40-0.05Y)使均衡收入减少额也是40(600-560=40)然而自发净出口变化对净出口余额的影响更大一些自发投资增加10时净出口余额只减少2(20-18=2)而自发净出口减少10时净出口余额减少8(20-12=8)五、论述题乘数也叫倍数宏观经济学中所运用的乘数是指国民收入函数中由于某个自变量的变化而引起的国民收入的变化投资乘数是指投资量变化数与国民收入变化数的比率它表明投资的变动将会引起国民收入若干倍的变动投资之所以具有乘数作用是因为各经济部门是相互关联的某一部门的一笔投资不仅会增加本部门的收入而且会在国民经济各部门引起连锁反应从而增加其他部门的投资与收入最终使国民收入成倍增长发挥投资乘数作用有三个前提条件:(1)在消费函数或储蓄函数为即定的条件下一定的投资可以引起收入的某种程度的增加即投资的乘数作用可以相当顺利地发挥出来(2)要有一定数量的劳动力可以被利用(3)要有一定数量的存货可以被利用第四章宏观财政政策一、单项选择题1、A2、D3、C4、A5、B6、B7、A8、A9、B 10、A二、填空题1. 通货紧缩通货膨胀2. 财政支出财政收入3. 政府通过改变支出来影响国民收入水平4. 财政收入政策5. 累进的税收制度福利社会支出制度厂商和居民的储蓄6. 增加抑制减少阻碍7. 增加扩张减少收缩8. 直接税间接税公司收入税9. 赤字10. 当政府用增税的方法来偿还债务时人们为了逃避高税率而减少工作时间第五章货币的需求和供给一、填空题1. 人们普遍接受的交换媒介2. 交换媒介计算单位价值储蓄延期支付的手段3. 把货币留在手中的偏好4. 交易预防投机交易余额预防余额投机宏观经济学习题参考答案(部分)余额5. 国民收入利息率6. 作为货币单位的基础的商品7. 货币供给量8. 纸币硬币9. 商业银行的活期存款10. 通货活期存款M1-A 可转让的提款单ATS第六章货币对经济的影响一、填空题1. 货币需求货币供给2. 货币需求量利息率右下方3. 垂直4. 利息率5. 向右下降6. 投资支出利息率右下方7. 货币需求量对利息率变化反映的敏感程度8. 投资的利息弹性9. 货币数量的增加已不能降低利息率10. 价格水平货币数量二、单项选择题1、B2、C3、A4、D5、B6、D7、A8、D9、C第七章宏观货币政策一、单项选择题1、D2、B3、D4、C5、D6、A7、A8、C二、多项选择题1、ABC2、AC三、简答题1、中央银行的主要货币政策工具是:公开市场活动准备金要求以及贴现率2、中央银行的两种主要负债是:中央银行发行的、在流通中的通币以及商业银行在中央银行的存款3、持有货币的三种主要动机是:交易动机预防动机以及投机动机4、有许多货币的组成部分并不支付利息例如通货和活期存款利率是持有货币的机会成本持有货币没有支付利息但放弃了用于其他金融资产时所能得到的利息收入当利息上升时持有货币的成本就增加了因此人们就要减少自己的货币持有量并用货币去购买其它金融资产以便获得更高的利率四、计算题(1)货币乘数时货币供给量(M)与货币基础(MB)的比率:mm=M/MB=5000亿/2022年亿=2.5(2)可以计算a=C/D,b=R/D并用第一题的公式计算货币乘数:a=C/D=1000亿/5000亿=0.2b=R/D=500亿/5000亿=0.1mm= 1+a/a+b = 1+0.2/0.2+0.1 = 1.2/0.3 = 4(3)题中已经给出b=R/D=0.1,但仍需计算a=C/D.从题中可以知道C的值但不知道D的值我们可以根据已知的b和R计算出D=R/b因此D=R/b=500亿/0.1=5000亿a=C/D=1500/5000=0.3mm=1+a/a+b=1+0.3/0.3+0.1=1.3/0.4=3第八章国民收入和货币的均衡一、单项选择题1、A2、A3、B4、C5、A6、A7、C8、D9、C二、多项选择题1、ABD三、名词解释:1、IS曲线--在产品市场达到均衡时收入和利率的各种组合的点的轨迹在两部门经济中IS曲线的数学表达式为I(r)=S(Y)它的斜率为负这表明IS曲线一般是一条向右下方倾斜的曲线一般来说在产品市场上位于IS曲线右方的收入宏观经济学习题参考答案(部分)和利率的组合都是投资小于储蓄的非均衡组合;位于IS曲线左方的收入和利率的组合都是投资大于储蓄的非均衡组合只位于IS曲线上的收入和利率的组合才是投资等于储蓄的均衡组合2、LM曲线--表示货币市场中货币供给等于货币需求时收入与利率的各种组合的点的轨迹LM曲线的数学表达式为M/P=ky-hr 它的斜率为正这表明LM曲线一般是向右上方倾斜的曲线一般说来在货币市场上位于LM曲线右方的收入和利率的组合都是货币需求大于货币供给的非均衡组合位于LM曲线左方的收入和利率的组合都是货币需求小于货币供给的非均衡组合只有位于LM曲线上的收入和利率的组合才是货币需求等于货币供给的均衡组合3、凯恩斯陷阱--又称流动偏好陷阱或流动性陷阱指由于流动偏好的作用利息不再随货币供给量的增加而降低的情况西方经济学认为利息是人们在一定时期内放弃流动偏好的报酬利息率的高低取决于货币的供求流动偏好代表了货币的需求货币数量代表了货币的供给货币数量的多少由中央银行的政策决定货币数量的增加在一定程度上可以降低利息率但是由于流动偏好的作用低于这一点人们就不肯储蓄宁肯把货币保留在手中四、简答题1、计划的总支出是包括自发支出与引致支出在IS-LM模型分析中自发支出取决于利率引致支出取决于实际国民生产总值所以只有当利率与实际国民生产总值为某一特定值的结合时所决定的计划的总支出才能与实际国民生产总值相等从而实现物品市场的均衡2、极端的凯恩斯主义者认为当存在流动性陷阱时人们在即定的利率时愿意持有任何数量的货币所以LM曲线为一条水平线自发支出的增加使IS曲线向右方移动实际国民生产总值增加而利率不变由于财政政策所引起的自发支出增加不会引起利率上升所以也就没有挤出效应财政政策的作用最大而且流动陷阱的情况在现实中是存在的第九章国民收入和价格水平的均衡一、单项选择题1、B2、A3、A4、B5、B6、C7、C8、A9、D第十章失业和通货膨胀一、单项选择题1、A2、B3、B4、B5、B6、D7、B二、多项选择题1、ACE2、ABC3、AC4、AB三、简答题:滞胀(或译停止膨胀)就是实际国民生产总值增长率停滞(不增长甚至下降)与通货膨胀率加剧并存的状况第十一章经济周期一、单项选择题1、C2、B3、B4、B5、A6、A7、C8、A9、A第十二、十三章经济的增长和发展一、单项选择宏观经济学习题参考答案(部分)题1、B2、A3、C4、C5、B6、B7、A8、C9、C 10、A11、D 12、C 13、D 14、A 15、B16、A 17、B 18、D二、简答题1、人均生产函数表明了在技术为既定的情况下人均产量如何随人均存量增加而增加如果资本积累率提高那么人均资本存量也就更迅速地提高这就意味着人均产量迅速增长即更高的增长率可以用沿着人均生产函数的变动来说明这一点2、有几种方法可以克服经济增长的障碍其中已被证明最成功的一种是较为自由的国际贸易的扩大香港、新加坡等国家或地区通过生产自己具有比较优势的产品迅速地增加了人均收入获得国际贸易的好处3、在哈罗德- 多马模型G= S/V 中V=4G=7%从而S=G?V=7%×4=28%三、论述题1、英国经济学家哈罗德、美国经济学家多马把凯恩斯理论的短期比较静态分析扩展为长期动态分析在凯恩斯就业理论的基础上分别建立了自己的增长模型由于二者基本内容大致相同通称为哈罗德-多马模型(1)哈罗德模型哈罗德指出凯恩斯收入均衡论的局限性认为要保证经济长期均衡增长必须要求投资保持一定的增长率为分析实现经济稳定增长的均衡条件哈罗德建立了经济增长模型假设条件有:①全社会只生产一种产品不用于消费部分都用于投资②储蓄倾向不变储蓄由收入水平决定③社会生产中只有劳动和资本两种生产要素两种要素的比例不变而且每单位产品消耗的生产要素也不变④技术水平不变边际资本系数等于平均资本系数即资本产量比率不变⑤资本和劳动的边际生产率递减(2)多马模型投资两重性:一方面投资增加有效需求和国民收入即扩大了需求另一方面投资还增加了资本存量和生产能力即扩大了供给多马认为:通过增加投资解决失业问题就必须在下一时期增加更多的支出(需求)才能保证新增加的资本存量及其潜在的生产能力得到充分利用(3)哈罗德-多马模型的理论观点把哈罗德-模型和多马模型合在一起从哈罗德-多马模型出发可得出以下三个观点①经济稳定增长的条件当一定得合意储蓄率与合意得资本-产量比率决定的经济增长率是有保障的增长率时社会经济就能够实现稳定增长②短期经济波动的原因如果实际增长率与有保障的增长率不相等就会引起经济波动实际增长率和有保证的增长率一致是很少见的、偶然的所以社会经济必然要出现波动在收缩和扩张的交替中发展③经济长期波动的原因有保证的增长率和自然增长率之间的关系变化成为经济社会长期波动的原因宏观经济学习题参考答案(部分)(4)哈罗德-多马模型的理论基础是凯恩斯主义理论它不仅在理论上是投资等于储蓄这一公式的长期化与动态化而且在分析中也沿用了凯恩斯主义的某些脱离现实的抽象心理概念例如对经济增长具有重要作用的有保证的增长率是资本家感到满意并准备继续下去的增长率这里所强调的仍然是资本家的心理预测即凯恩斯所说的资本边际效率这样就和凯恩斯同样把资本家的乐观或悲观的情绪扩大为决定经济发展的因素哈罗德-多马模型关于短期与长期经济波动的分析和其他经济周期理论一样否认了波动的根本原因--资本主义社会的基本矛盾用一些抽象的技术经济关系来说明经济波动的产生哈罗德虽然也承认资本主义社会经济波动的必然性但他仍然相信资本主义是可以实现稳定的长期增长的他的整个分析正是为实现这种稳定增长而出谋划策当然对哈罗德-多马模型如果加以改造或使用不同的解释也可以为我们所借鉴例如把哈罗德-多马模型的储蓄率(s)解释为积累率把产量-资本之比(1/c)解释为投资的经济效果即每单位增加的可以造成的产量的增加那么该模型的公式即可变为国民收入增长率=积累率×投资的经济效果或G= s 1/c式中:投资的经济效果为资本-产出之比的倒数至少在理论上它的数值式可能被事先估算出来的在已知投资经济效果的情况下哈罗德-多马模型可以被认为是表明国民收入增长率和积累率之间的数量关系的公式。
宏观经济学课后习题答案
宏观经济学课后习题答案!!第一章导论1.(1)宏观经济学研究的问题是一个国家整体经济的运行情况以及政府如何运用经济政策来影响国家整体经济的运作。
其核心是国民收入决定理论和就业理论。
(2)宏观经济学研究的是总体经济问题,它涉及经济中商品与劳务的总产出及其增长速度、通货膨胀与失业的程度、经济衰退及其原因、国际收支状况及汇率的变动等。
2.(1)宏观经济学与微观经济学的区别:①研究对象不同。
微观经济学的研究对象是单个经济单位,如家庭、厂商等。
宏观的研究对象则是整个经济,研究整个经济的运行方式与规律,从总量上分析经济问题。
②解决的问题不同。
微观解决的是资源配置问题,即生产什么、如何生产和为谁生产的问题,以实现个体效益的最大化。
宏观则把资源配置作为既定的前提,研究社会范围内的资源利用问题,以实现社会福利的最大化。
③研究方法不同。
微观的研究方法是个量分析,即研究经济变量的单项数值如何决定。
宏观则是总量分析,即对能够反映整个经济运行情况的经济变量的决定、变动及其相互关系进行分析。
④基本假设不同。
微观的基本假设是市场出清(在给定的价格P之下,市场上的意愿供给等于意愿需求,达到均衡状态)、完全理性、充分信息,认为“看不见的手”能自由调节实现资源的优化配置。
宏观则是既定市场机制是不完善的,政府有能力调节经济,通过“看得见的手”纠正市场机制的缺陷。
⑤中心理论不同。
微观的中心理论是价格理论,还包括消费者行为理论、生产理论、分配理论、一般均衡理论、市场理论、产权理论、福利经济学、管理理论等。
宏观的中心理论则是国民收入决定理论,还包括失业与通货膨胀理论、经济周期理论与经济增长理论、开放经济理论等。
(2)宏观经济学与微观经济学的联系:①微观经济分析是宏观经济分析的基础,离开了微观分析这一基础,宏观分析将成为空中楼阁。
②从根本目标上看,宏观经济分析与微观经济分析也是一致的。
③宏观经济学与微观经济学虽然分析的侧重点不同,但二者是不能分开的。
宏观经济学第四章习题及答案
第四单元财政政策与货币政策本单元所涉及到的主要知识点:1.宏观经济政策目标及其种类;2.财政制度及其自动稳定器;3.财政政策与“挤出效应”;4.平衡预算、功能财政与赤字对经济的影响;5.货币乘数;6.货币政策工具与货币政策;7.财政政策与货币政策的组合及其效果比较。
一.单项选择1.扩张性财政政策的本质是(D )。
a.货币供给扩张; b.政府规模扩大;c.物价更稳定; d.增加GDP。
2.紧缩性财政政策的本质是(D )。
a.货币供给紧缩; b.政府规模缩小;c.实现物价稳定; d.减少GDP。
3.以下( D)不能视为自动稳定器。
a.失业救济; b.累进税;c.社会保障; d.国防开支。
4.财政盈余与( B)对均衡GDP水平的影响效果相同。
a.储蓄减少; b.储蓄增加;c.消费增加; d.投资增加。
5.投资支出急剧减少的情况下,为保证经济维持在充分就业状态政府应(C )。
a.使税收和政府支出相等; b.使税收超过政府支出;c.使政府支出超过税收; d.提高税率。
6.如果社会总需求的构成是消费1000亿元,投资400亿元,净出口100亿元,政府购买支出200亿元;充分就业的GDP为1200亿元。
为使价格水平保持稳定政府应( A )。
a.提高税率,并减少政府支出;b.通过降低政府债券的利息率来减少私人储蓄;c.增加政府支出;d.通过降低公司所得税率来鼓励私人投资。
7.经济处于严重衰退时,适当的经济政策应当是( B )。
a.减少政府支出; b.降低利息率;c.使本国货币升值; d.提高利息率。
8.下列叙述中(A )是正确的。
a.内在稳定器能部分地抵消经济波动;b.内在稳定器无法缓解失业;c.内在稳定器可以完全抵消任何经济波动;d.以上都不对。
9.拉弗曲线表明( D )。
a.税率越高,总税收额越高; b.税率越高,总税收额越低;c.税率与总税收额之间不相关; d.某一税率水平上税收总额最大。
10.以下( A )的财政政策是彻底反周期波动的。
宏观经济学课后答案第四章
第四章一、名词解说一般均衡:经过生产因素市场和商品市场以及这两种市场互相之间的供应和需求力量的互相作用,每种商品和生产因素的供应量与需求量在某一价钱下同时趋于相等,社会经济将达到全面均衡状态。
交易动机:指个人和公司为了进行正常的交易活动而需要足够的钱币,现金来支付开发。
慎重动机:为预防不测支出而拥有部分钱币的动机。
投灵活机:人们为了抓住有益的购置有价证券的机遇而拥有一部分钱币。
流动偏好:是指因现金存在流动性,令人们更希望拥有更多的现金。
资本边沿效率:是一种使一项资本物件的使用期内各样预期利润的现值之和等于这项资本品的供应价钱或许重置成本的贴现率。
二、单项选择题1、一般来说,A 、为正ISB曲线的斜率(、为负 CB)、为零D、等于 12、在其余条件不变的状况下,政府购置增添会使IS 曲线( B)A 、向左挪动B 、向右挪动 C、保持不变 D、发生转动3、依据凯恩斯的看法,人们拥有钱币事因为(D)A、交易动机 B 、慎重动机 C 、投灵活机 D、以上都正确4、投资需求增添会惹起 IS 曲线( B)A、向右挪动投资需求曲线的挪动量B、向右挪动投资需求曲线的挪动量乘以乘数C、向左挪动投资需求曲线的挪动量D、向左挪动投资需求曲线的挪动量乘以乘数5、IS 曲线上的每一点表示(A)A、产品市场投资等于积蓄时收入与利率的组合B、使投资等于积蓄时的均衡钱币额C、钱币市场钱币需求等于钱币供应时的均衡钱币额D、产品市场与钱币市场都均衡时的收入与利率组合6、以下惹起 IS 曲线左移的因素是( C)A、投资需求增添 B 、政府购置减少 C 、政府税收增添 D 、政府税收减少7、LM曲线的斜率取决于( D)A、边沿花费偏向B、投资需求对利率改动的反响程度C、钱币需求对收入改动的反响程度D、钱币需求对利率改动的反响程度8、当民众预期( B)时,会拥有更多的钱币。
A 、债券价钱上升B 、债券利率降落C 、债券利率降落D 、估算盈利增添9、钱币的谋利型需求主要取决于( A)A 、利率高低B 、将来收入的水平C 、预防动机D 、利率降落10、在其余条件不变的状况下,钱币供应增添会惹起(A)A 、收入增添B 、收入降落C 、利率上升D 、利率降落三、简答题1、为何说资本边沿效率曲线不可以正确代表公司的投资需求曲线资本边沿效率曲线基本上反应了投资需求与利率之间的反方向改动关系。
芬斯特拉版《国际宏观经济学》课后习题答案第 章
Exchange Rates II: The Asset Approach in the Short Rune the money market and FX diagrams to answer the following questions about therelationship between the British pound (£) and the U.S. dollar ($). The exchange rate is in U.S. dollars per British pound, E $/£. W e want to consider how a change in the U.S. money supply affects interest rates and exchange rates. On all graphs, label the initial equilibrium point A.a.Illustrate how a temporary decrease in the U.S. money supply affects the moneyand FX markets. Label your short-run equilibrium point B and your long-run equilibrium point C .Answer:See the diagram below.S-23i $i 1$i 2$2$DR 1DR2E 1E E $/£M 1US P 1US M 2US P 1USing your diagram from (a), state how each of the following variables changesin the short run (increase/decrease/no change): U.S. interest rate, British interestrate, E $/£, E e $/£, and the U.S. price level.Answer: The U.S. interest rate increases, the British interest rate does notchange, E $/£decreases, E e $/£does not change, and the U.S. price level does notchange.ing your diagram from (a), state how each of the following variables changesin the long run (increase/decrease/no change relative to their initial values atpoint A ): U.S. interest rate, British interest rate, E $/£, E e $/£, and U.S. price level.Answer:All of the variables return to their initial values in the long run. This isbecause the shock is temporary, implying the central bank will increase themoney supply from M 2to M 1in the long run.e the money market and FX diagrams from (a) to answer the following questions.This question considers the relationship between the Indian rupees (Rs) and the U.S.dollar ($). The exchange rate is in rupees per dollar, E Rs /$. On all graphs, label the ini-tial equilibrium point A .a.Illustrate how a permanent increase in India’s money supply affects the money andFX markets. Label your short-run equilibrium point B and your long-run equi-librium point C .Answer:See the following diagram. Thick arrows indicate temporary movementwhile thinner ones indicate the movements in the long run. In the short run,prices are fixed. Therefore the real money supply changes from MS 1to MS 2, thustemporarily lowering the domestic interest rate. In the long run, as prices rise,the real money supply and interest rate return to their original level. In the for-eign exchange market, FR shifts to the right and stays there permanently becauseof an expected depreciation of rupees.S-24Solutions ■Chapter 4(15) Exchange Rates II: The Asset Approach in the Short Runi Rs i 1Rs i 2Rs1Rs2Rs12E 1E 2E 3M 2INP 2IN E Rs/$M 1IN P 1IN M 2IN P 1IN3.Is overshooting (in theory and in practice) consistent with purchasing power parity?Consider the reasons for the usefulness of PPP in the short run versus the long run and the assumption we’ve used in the asset approach (in the short run versus the long run). How does overshooting help to resolve the empirical behavior of exchange rates in the short run versus the long run?Answer:Y es, overshooting is consistent with PPP. Investors forecast the expected ex-change rate based on the theory of PPP.When there is some change in the market, the investors know the exchange rate will change to equate relative prices in the long run.This is why we observe overshooting in the short run—the investors incorporate this information into their short-run forecasts. Exchange rates are volatile in the short run.The theory’s implication that there is exchange rate overshooting (in response to per-manent shocks) is one explanation for short-run volatility in exchange rates.e the money market and foreign exchange (FX) diagrams to answer the followingquestions. This question considers the relationship between the euro (€) and the U.S.dollar ($). The exchange rate is in U.S. dollars per euro, E$/€. Suppose that with fi-nancial innovation in the United States, real money demand in the United States de-creases. On all graphs, label the initial equilibrium point A.a.Assume this change in U.S. real money demand is temporary. Using the FX andmoney market diagrams, illustrate how this change affects the money and FXmarkets. Label your short-run equilibrium point B and your long-run equilib-rium point C.Answer: See the following diagram. The long-run values are the same as the ini-tial values because the shock is temporary. Also because the shock is temporary,we assume that the reversal of real money demand occurs before the price leveladjusts—that is, MD returns from MD2to MD1before the price level changes. S-26Solutions ■Chapter 4(15) Exchange Rates II: The Asset Approach in the Short Run i$i1$i2 $i1$i2$1E1M1US / P1US E2E$/€b.Assume this change in U.S. real money demand is permanent. Using a new dia-gram, illustrate how this change affects the money and FX markets. Label your short-run equilibrium point B and your long-run equilibrium point C.Answer:See the following diagram. In the long run, the price level will have to increase to adjust for the drop in real money demand (assuming the central bank does not change the money supply, M). That is, the nominal interest rate returns to its initial value in the long run. This requires that the price level increase to reduce real money supply. The drop in real money demand will have to be met one-for-one with a drop in real money supply (generated by an increase in the price level). In this case, the expected exchange rate changes because the shock is permanent. Therefore, FR schedule in the forex market also shifts upward.Solutions ■Chapter 4(15) Exchange Rates II: The Asset Approach in the Short RunS-27i 1$i 2$1E 1E 2E 3E $/€i $i 1$i 2$M 1US / P 1US M 1US / P 2US 2c.Illustrate how each of the following variables changes over time in response to apermanent reduction in real money demand: nominal money supply M US , price level P US , real money supply M US /P US , U.S. interest rate i $, and the exchange rate E $/€.Answer:See the following diagrams.M US P US i $T T nE $/⑀M US /P US M US /P US22115.This question considers how the FX market will respond to changes in monetarypolicy. For these questions, define the exchange rate as Korean won per Japanese yen,E WON /¥. Use the FX and money market diagrams to answer the following questions.On all graphs, label the initial equilibrium point A .a.Suppose the Bank of Korea permanently decreases its money supply. Illustrate theshort-run (label the equilibrium point B ) and long-run effects (label the equilib-rium point C ) of this policy.Answer:See the following diagram. In the short run, prices are fixed. Thereforethe real money supply changes from MS 1to MS 2, thus temporarily raising the Ko-rean interest rate. In the long run, as prices fall, the real money supply and interestrate return to their original levels. In the foreign exchange market, FR shifts to theleft and stays there permanently because of an expected appreciation of won.S-28Solutions ■Chapter 4(15) Exchange Rates II: The Asset Approach in the Short Runi won i 1won i 2won1won2wonM 1K / P 1K M 2K / P 2K M 2K / P 1K 1E 1E 3E 2E won/¥2b.Now , suppose the Bank of Korea announces it plans to permanently decrease itsmoney supply but doesn’t actually implement this policy . How will this affect theFX market in the short run if investors believe the Bank of Korea’s announcement?Answer:See the following diagram. I n this case, interest rates on won-denominated deposits don’t change because the Bank of Korea doesn’t cut themoney supply. However, because investors expected the Bank of Korea to cut themoney supply, they expect the won will appreciate relative to the yen, causing adecrease in the return on yen-denominated deposits in the short run. Notice theresulting change in the exchange rate is relatively small (compared with the dra-matic decrease we see in [a]).i won i 1won M 1K / P 1K DR 1E 1E 2E won/¥c.Finally, suppose the Bank of Korea permanently decreases its money supply butthis change is not anticipated. When the Bank of Korea implements this policy,how will this affect the FX market in the short run?Answer:In this case, the expected exchange rate is unchanged because the in-vestors didn’t expect the decrease in the money supply.Solutions ■Chapter 4(15) Exchange Rates II: The Asset Approach in the Short RunS-29i won i 1won i 2won 2won1wonM 1K / P 1K M 2K / P 1K DR 1DR E 1E 2E won/¥ing your previous answers, evaluate the following statements:i.If a country wants to increase the value of its currency, it can do so (tem-porarily) without raising domestic interest rates.ii.The central bank can reduce both the domestic price level and the value ofits currency in the long run.iii.The most effective way to increase the value of a currency is through sur-prising investors.Answer: Though it is theoretically possible, as shown in (b), it is not a good pol-icy because it is bad for the policy makers reputation in the long run.i.True; shown in (b).ii.False; shown in (a) A reduction in price level implies an exchange rate ap-preciation by PPP .iii.False; shown in (b) and (c) compared with (a). The most dramatic appreci-ation in the won occurs when the reduction in M is coupled with investorsanticipating the appreciation in the won. In general, a policy must be cred-ible for it to have an effect in the long run.6.In the late 1990s, several East Asian countries used limited flexibility or currency pegsin managing their exchange rates relative to the U.S. dollar. This question considers how different countries responded to the East Asian Currency Crisis (1997–1998).For the following questions, treat the East Asian country as the home country and the United States as the foreign country. Also, for the diagrams, you may assume these countries maintained a currency peg (fixed rate) relative to the U.S. dollar. Also, for the following questions, you need consider only the short-run effects.a.In July 1997, investors expected that the Thai baht would depreciate. That is, theyexpected that Thailand’s central bank would be unable to maintain the currency peg with the U.S. dollar. Illustrate how this change in investors’ expectations af-fects the Thai money market and the FX market, with the exchange rate defined as baht (B) per U.S. dollar, denoted E B/$. Assume the Thai central bank wants to maintain capital mobility and preserve the level of its interest rate and abandons the currency peg in favor of a floating exchange rate regime.Answer:If Thailand is willing to let its currency float against the dollar, thenThailand’s central bank can maintain monetary policy autonomy and interna-tional capital mobility. See the following diagram:S-30Solutions ■Chapter 4(15) Exchange Rates II: The Asset Approach in the Short Runi baht i 1bahtM 1T / P 1T ERDR 12E 1E 2E baht/$b.I ndonesia faced the same constraints as Thailand—investors feared I ndonesiawould be forced to abandon its currency peg. Illustrate how this change in in-vestors’ expectations affects the Indonesian money market and the FX market,with the exchange rate defined as rupiahs (Rp) per U.S. dollar, denoted E Rp /$. As-sume the Indonesian central bank wants to maintain capital mobility and the cur-rency peg.Answer: If Indonesia wants to maintain the currency peg against the dollar andmaintain international capital mobility, it will have to give up monetary policyautonomy. In this case, Indonesia has to increase the domestic interest rate to keepinvestors from dumping their rupiah-denominated deposits for U.S. dollars andmove their investments out of Indonesia (this would then cause a depreciation inthe rupiah).i rup i 1rup i 2rup 1rup 2rupM 1I / P 1I M 2I / P 1I 12FR E 1E rupiah/$2c.Malaysia had a similar experience, except that it used capital controls to maintainits currency peg and preserve the level of its interest rate. Illustrate how this change in investors’ expectations affects the Malaysian money market and the FX market,with the exchange rate defined as ringgit (RM) per U.S. dollar, denoted E RM/$. Y ou need show only the short-run effects of this change in investors’ expectations.Answer:See the following diagram. In the absence of capital controls Malaysian interest rate would have to rise. However, by preventing investors from taking ad-vantage of arbitrage, Malaysia creates a disequilibrium. The investors require i 2RM to keep their deposits in Malaysia, but they only receive i 1RM . Because of the cap-ital controls imposed by Malaysia, investors cannot withdraw their ringgit-denominated deposits (selling ringgit in exchange for dollars in the FX market).n effect, the foreign market equilibrium diagram shown below does notwork/exist. This allows Malaysia to maintain monetary policy autonomy and a fixed exchange rate at the same time.Solutions ■Chapter 4(15) Exchange Rates II: The Asset Approach in the Short RunS-31i RM i 1RM i 2RM 1RM 2RM M 1M / P 1M 12E 1E RM/$pare and contrast the three approaches just outlined. As a policy maker,which would you favor? Explain.Answer: There is no “correct” answer to this question. The cases above highlight the trilemma because each country can choose a different option depending on their domestic or international priorities. They need to compare the benefits of having any two of (a) fixed exchange rates, (b) monetary autonomy, and (c) in-ternational capital mobility against the cost of not having the third one.7.Several countries have opted to join currency unions. Examples include the Euroarea, the CFA franc union in W est Africa, and the Caribbean currency union. This in-volves sacrificing the domestic currency in favor of using a single currency unit in multiple countries. Assuming that once a country joins a currency union it will not leave, do these countries face the policy trilemma discussed in the text? Explain.Answer: These countries do face the trilemma because they are committed to main-taining the first policy goal of a fixed exchange rate. Joining a currency union effec-tively means a country has a fixed exchange rate without the need for government intervention because the money supply is controlled by a regional central bank for member countries. This effectively reduces the choice to a dilemma between mone-tary policy autonomy versus international capital mobility. T ypically, countries that are parts of a currency union sacrifice monetary policy autonomy; policy decisions are made jointly rather than independently.S-32Solutions ■Chapter 4(15) Exchange Rates II: The Asset Approach in the Short Run8.During the Great Depression, the United States remained on the international goldstandard longer than other countries. This effectively meant that the United States wascommitted to maintaining a fixed exchange rate at the onset of the Great Depression.The U.S. dollar was pegged to the value of gold along with other major currencies,including the British pound, the French franc, and so on. Many researchers haveblamed the severity of the Great Depression on the Federal Reserve and its failure toreact to economic conditions in 1929 and 1930. Discuss how the policy trilemma ap-plies to this situation.Answer: The United States was committed to the fixed exchange rate with gold;consequently, policy makers had to sacrifice either monetary policy autonomy or cap-ital mobility, just as the trilemma suggests. Based on the information given in thequestion, we can assume that the policy did not respond to the U.S. business cycle(policy makers did not exercise monetary policy autonomy). Thus, if we assume in-ternational capital mobility, the United States could not react to the business cyclewith a monetary expansion until it abandoned the gold standard.9.On June 20, 2007, John Authers, investment editor of the Financial Times,wrote thefollowing in his column “The Short View”:The Bank of England published minutes showing that only the narrowest pos-sible margin, 5–4, voted down [an interest] rate hike last month. Nobody fore-saw this. . . . The news took sterling back above $1.99, and to a 15-year highagainst the yen.Can you explain the logic of this statement? Interest rates in the United Kingdomhad remained unchanged in the weeks since the vote and were still unchanged afterthe minutes were released. What news was contained in the minutes that causedtraders to react? Use the asset approach.Answer: The news item indicates that investors did not expect the decision to leaveinterest rates unchanged would be divisive. They thought that any increases in inter-est rates would happen further in the future. Higher interest rates would lead to anappreciation in the pound sterling. When the minutes showed that interest rate in-creases were more likely than previously thought, investors came to expect an appre-ciation sooner rather than later. This caused an appreciation in the current spot ex-change rate.10.W e can use the asset approach to both make predictions about how the market willreact to current events and understand how important these events are to investors.Consider the behavior of the Union/Confederate exchange rate during the CivilW ar. How would each of the following events affect the exchange rate, defined as?Confederate dollars per Union dollar, EC$/$a.The Confederacy increases the money supply by 2,900% between July and De-cember of 1861.Answer: The Confederate money supply increases, the exchange rate increases,and the Confederate dollar depreciates.b.The Union Army suffers a defeat in Battle of Chickamauga in September 1863.Answer: Appreciation in the Confederate dollar is expected because a militaryvictory means a stable economy and monetary policy, implying decreased uncer-tainty and risk, the exchange rate decreases, and the Confederate dollar appreci-ates.c.The Confederate Army suffers a major defeat with Sherman’s March in the au-tumn of 1864.Answer: Just the opposite of (b) above: depreciation in the Confederate dollar isexpected because of military defeat increases economic and monetary uncertaintyand risk; the exchange rate increases, and the Confederate dollar depreciates.。
【VIP专享】宏观经济学思考题及参考答案
宏观经济学思考题及参考答案(1)第四章基本概念:潜在GDP,总供给,总需求,AS曲线,AD曲线。
思考题1、宏观经济学的主要目标是什么?写出每个主要目标的简短定义。
请详细解释为什么每一个目标都十分重要。
答:宏观经济学目标主要有四个:充分就业、物价稳定、经济增长和国际收支平衡。
(1)充分就业的本义是指所有资源得到充分利用,目前主要用人力资源作为充分就业的标准;充分就业本不是指百分之百的就业,一般地说充分就业允许的失业范畴为4%。
只有经济实现了充分就业,一国经济才能生产出潜在的GDP,从而使一国拥有更多的收入用于提高一国的福利水平。
(2)物价稳定,即把通胀率维持在低而稳定的水平上。
物价稳定是指一般物价水平(即总物价水平)的稳定;物价稳定并不是指通货膨胀率为零的状态,而是维持一种能为社会所接受的低而稳定的通货膨胀率的经济状态,一般指通货膨胀率为百分之十以下。
物价稳定可以防止经济的剧烈波动,防止各种扭曲对经济造成负面影响。
(3)经济增长是指保持合意的经济增长率。
经济增长是指单纯的生产增长,经济增长率并不是越高越好,经济增长的同时必须带来经济发展;经济增长率一般是用实际国民生产总值的年平均增长率来衡量的。
只有经济不断的增长,才能满足人类无限的欲望。
(4)国际收支平衡是指国际收支既无赤字又无盈余的状态。
国际收支平衡是一国对外经济目标,必须注意和国内目标的配合使用;正确处理国内目标与国际目标的矛盾。
在开放经济下,一国与他国来往日益密切,保持国际收支的基本平衡,才能使一国避免受到他国经济波动带来的负面影响。
3,题略答:a.石油价格大幅度上涨,作为一种不利的供给冲击,将会使增加企业的生产成本,从而使总供给减少,总供给曲线AS将向左上方移动。
b.一项削减国防开支的裁军协议,而与此同时,政府没有采取减税或者增加政府支出的政策,则将减少一国的总需求水平,从而使总需求曲线AD向左下方移动。
c.潜在产出水平的增加,将有效提高一国所能生产出的商品和劳务水平,从而使总供给曲线AS向右下方移动。
国际经济学作业答案第四章
国际经济学作业答案-第四章Chapter 4Resources and Trade: The Heckscher-Ohlin ModelMultiple Choice Questions1. In the 2-factor, 2 good Heckscher-Ohlin model, an influx of workers from across the borderwould(a) move the point of production along the production possibility curve.(b) shift the production possibility curve outward, and increase the production of both goods.(c) shift the production possibility curve outward and decrease the production of thelabor-intensive product.(d) shift the production possibility curve outward and decrease the production of thecapital-intensive product.(e) None of the above.Answer: D2. In the 2-factor, 2 good Heckscher-Ohlin model, the two countries differ in(a) tastes.(b) military capabilities.(c) size.(d) relative availabilities of factors of production.(e) labor productivities.Answer: D3. In the 2-factor, 2 good Heckscher-Ohlin model, a change from autarky (no trade) to trade willbenefit the owners of(a) capital.(b) the relatively abundant factor of production.(c) the relatively scarce factor of production.(d) the relatively inelastic factor of production.(e) the factor of production with the largest elasticity of substitution.Answer: B4. In the 2-factor, 2 good Heckscher-Ohlin model, a change from autarky (no trade) to trade(a) will tend to make the wages in both countries more similar.(b) will equalize the wages in both countries.(c) will tend to make the wages in both countries less similar.(d) will tend to make wages equal to returns to capital.(e) will tend to make rents equal to interest rates.Answer: A5. The Leontieff Paradox(a) supported the validity of the Ricardian theory of comparative advantage.(b) supported the validity of the Heckscher-Ohlin model.(c) failed to support the validity of the Ricardian theory.(d) failed to support the validity of the Heckscher-Ohlin model.(e) proved that the U.S. economy is different from all others.Answer: D6. The Leontieff Paradox(a) refers to the finding that U.S. exports were more labor intensive than its imports.(b) refers to the finding that U.S. Exports were more capital intensive than its exports.(c) refers to the finding that the U.S. produces outside its Edgeworth Box.(d) still accurately applies to today’s pattern of U.S. international tr ade.(e) refers to the fact that Leontieff—an American economist—had a Russian name.Answer: A7. The 1987 study by Bowen, Leamer and Sveikauskas(a) supported the validity of the Leontieff Paradox.(b) supported the validity of the Heckscher-Ohlin model.(c) used a two-country and two-product framework.(d) demonstrated that in fact countries tend to use different technologies.(e) proved that the U.S.’s comparative advantage relied on skilled labor.Answer: A8. Empirical observations on actual North-South trade patterns tend to(a) support the validity of the Leontieff Paradox.(b) support the validity of the Heckscher-Ohlin model.(c) support the validity of the Rybczynski Theorem.(d) support the validity of the wage equalization theorem.(e) support the validity of the neo-imperialism exploitation theory.Answer: B9. The Case of the Missing Trade refers to(a) the 9th volume of the Hardy Boys’ Mystery series.(b) the fact that world exports does not equal world imports.(c) the fact that factor trade is less than predicted by the Heckscher-Ohlin theory.(d) the fact that the Heckscher Ohlin theory predicts much less volume of trade than actuallyexists.(e) None of the above.Answer: C10. If the Unted States had relatively more capital per worker than Mexico, and if the LeontieffParadox applied to this trade, then a successful expansion of trade under NAFTA between Mexico and the United States would tend to benefit which group in the United States?(a) Environmentalists(b) Capitalists(c) Workers(d) Land owners(e) Skilled labor with relatively high levels of human capitalAnswer: C11. According to the Heckscher-Ohlin model, the source of comparative advantage is a country’s(a) technology.(b) advertising.(c) human capital.(d) factor endowments.(e) Both (a) and (b).Answer: D12. The Hechscher-Ohlin model states that a country will have a comparative advantage in thegood or service whose production is relatively intensive in the ______ with which the country is relatively abundant.(a) tastes(b) technology(c) factor of production(d) opportunity cost(e) scale economyAnswer: C13. One way in which the Heckscher-Ohlin model differs from the Ricardo model of comparativeadvantage is by assuming that __________ is (are) identical in all countries.(a) factor of production endowments(b) scale economies(c) factor of production intensities(d) technology(e) opportunity costsAnswer: D14. According to the Hecksher-Ohlin model,(a) everyone automatically gains from trade(b) the scarce factor necessarily gains from trade(c) the gainers could compensate the losers and still retain gains.(d) a country gains if its exports have a high value added.(e) None of the above.Answer: C15. The Heckscher-Ohlin model assumes that _____ are identical in all trading countries(a) tastes(b) technologies(c) factor endowments(d) Both (a) and (b).(e) None of the above.Answer: B16. As opposed to the Ricardian model of comparative advantage, the assumption of diminishingreturns in the Heckscher-Ohlin model means that the probability is greater that with trade(a) countries will not be fully specialized in one product.(b) countries will benefit from free international trade.(c) countries will consume outside their production possibility frontier.(d) comparative advantage is primarily supply related.(e) None of the above.Answer: A17. Starting from an autarky (no-trade) situation with Heckscher-Ohlin model, if Country H isrelatively labor abundant, then once trade begins(a) wages and rents should rise in H(b) wages and rents should fall in H(c) wages should rise and rents should fall in H.(d) wages should fall and rents should rise in H.(e) None of the above.Answer: C18. Which of the following is false (for the Heckscher-Ohlin model)?(a) If tastes are not identical in both countries, wages may still equalize.(b) Differences in technologies could be the source of gains from trade.(c) Some groups may gain and some may lose due to trade.(d) Gains for the trade-related winners will tend to be larger than losses of losers.(e) None of the above.Answer: B19. If tastes differed between countries, this could affect(a) wage equalization due to trade with no specialization.(b) the direction of trade (who exports what to whom).(c) the fact that some groups in a country might lose welfare due to trade.(d) the fact that the country as a whole will gain from trade.(e) None of the above.Answer: B20. Suppose that there are two factors, capital and land, and that the United States is relativelyland endowed while the European Union is relatively capital-endowed. According to the Heckscher-Ohlin model,(a) European landowners should support U.S.-European free trade.(b) European capitalists should support U.S.-European free trade.(c) all capitalists in both countries should support free trade.(d) all landowners should support free trade.(e) None of the above.Answer: B21. According to the Heckscher-Ohlin model, if the United States is richly endowed inhuman-capital relative to Mexico, then as NAFTA increasingly leads to more bilateral free trade between thetwo countries,(a) the United States will find its industrial base sucked into Mexico.(b) Mexico will find its relatively highly skilled workers drawn to the United States.(c) The wages of highly skilled U.S. workers will be drawn down to Mexican levels.(d) The wages of highly skilled Mexican workers will rise to those in the United States.(e) The wages of highly skilled Mexican workers will fall to those in the United States.Answer: E22. Assume that only two countries, A and B, exist.Consider the following data:CountriesFactor Endowments A BLabor Force 45 20Capital Stock 15 10If good S is capital intensive, then following the Heckscher-Ohlin Theory,(a) country A will export good S.(b) country B will export good S.(c) both countries will export good S.(d) trade will not occur between these two countries.(e) Insufficient information is given.Answer: B23. Continuing from Question #22, if you are told that Country B is very much richer thanCountry A, then the correct answer is:(a) country A will export good S.(b) country B will export good S.(c) both countries will export good S.(d) trade will not occur between these two countries.(e) insufficient information is given.Answer: B24. Continuing from Question #22, you are told that Country B is very much larger than countryA. The correct answer is:(a) country A will export good S.(b) country B will export good S.(c) both countries will export good S.(d) trade will not occur between these two countries.(e) insufficient information is given.Answer: B25. Continuing from Question #22, you are told that Country B has no minimum wage or childlabor laws. Now the correct answer is:(a) country A will export good S.(b) country B will export good S.(c) both countries will export good S.(d) trade will not occur between these two countries.(e) Insufficient information is given.Answer: B26. Continuing from Question #22, you now are told that the labor unions representing theworkers in each of the two respective countries are considering lobbying against the opening of international trade between these two countries. Note that workers’ income is derived solely from wages.(a) This would be a misguided decision from the viewpoint of the workers in both countries,since trade is always better than autarky.(b) This would be a good decision from the viewpoint of workers in Country A sinceinternational trade helps the capitalists and hurts the workers.(c) This would be a good decision from the viewpoint of workers in Country B sinceinternational trade helps the owners of capital and hurts the workers.(d) This would be a good decision for both unions since trade hurts workers wherever theylive.(e) None of the above.Answer: C27. We are now told that the information given us in Question #22 was not exactly accurate, andthat in fact S is relatively capital intensive only when relative wages are high, but becomesrelatively labor intensive when relative wages are low. Given this information:(a) country A will export good S.(b) country B will export good S.(c) both countries will export good S.(d) trade will not occur between these two countries.(e) Insufficient information is given.Answer: E28. The following are all assumptions that must be accepted in order to apply theHeckscher-Ohlin Theory, except for one:(a) countries differ in their endowments of factors of production.(b) countries differ in their technologies.(c) there are two factors of production.(d) production is subject to constant returns to scale.(e) one product always requires more machines per worker in its production than does theother product.Answer: B29. In international-trade equilibrium in the Heckscher-Ohlin model,(a) the capital rich country will charge less for the capital intensive good than the price paidby the capital poor country for the capital-intensive good.(b) the capital rich country will charge the same price for the capital intensive good as thatpaid for it by the capital poor country.(c) the capital rich country will charge more for the capital intensive good than the price paidby the capital poor country for the capital-intensive good.(d) the workers in the capital rich country will earn more than those in the poor country.(e) the workers in the capital rich country will earn less than those in the poor country.Answer: B30. If two countries were very different in their relative factor availabilities, then we would notexpect which of the following to be empirically supported?(a) The Heckscher-Ohlin Theorem(b) The Factor Price Equalization Theorem.(c) The Law of One Price(d) The Law of Demand(e) None of the above.Answer: B31. When Country A produces both goods more efficiently than Country B, then(a) country A should produce both goods and not trade.(b) country A should specialize in its good of least absolute disadvantage.(c) both countries would benefit from autarky.(d) both countries may not benefit from trade.(e) None of the above.Answer: E32. The minimum inform ation required to determine Country A’s comparative advantage is(a) the number of hours of labor in the economy of A.(b) ratio of labor inputs for products S and T in A.(c) total available labor, labor required per unit of S, and labor required per unit of T in A.(d) total available labor and the ratio of labor inputs for S and T in A.(e) None of the above.Answer: E33. The slope of a country’s PPF reflects(a) the opportunity cost of product S in terms of product T.(b) the opportunity cost of T in terms of money prices.(c) the opportunity cost of S or T in terms of S.(d) Both (a) and (b).(e) Both (a) and (c).Answer: A34. The Heckscher-Ohlin model predicts all of the following except:(a) which country will export which product.(b) which factor of production within each country will gain from trade.(c) the volume of trade.(d) that wages will tend to become equal in both trading countries.(e) None of the above.Answer: C35. The Heckscher-Ohlin model differs from the Ricardian model of Comparative Advantage inthat the former(a) has only two countries.(b) has only two products.(c) has two factors of production.(d) has two production possibility frontiers (one for each country).(e) None of the above.Answer: C36. International trade has strong effects on income distributions. Therefore, international trade(a) is beneficial to everyone in both trading countries.(b) will tend to hurt one trading country.(c) will tend to hurt some groups in each trading country.(d) will tend to hurt everyone in both countries.(e) will be beneficial to all those engaged in international trade.Answer: C37. Factors tend to be specific to certain uses and products(a) in countries lacking comparative advantage.(b) in the short run.(c) in capital-intensive industries.(d) in labor-intensive industries.(e) in countries lacking fair labor laws.Answer: B38. If the price of the capital intensive product rises more than does the price of the land intensiveproduct, then(a) demand will shift away from the capital-intensive product, and its production willdecrease.(b) demand will shift away from the capital-intensive product, and its production willdecrease relative to that of the land intensive product.(c) the production of the capital-intensive product will indeed decrease, but not for thereasons mentioned in (a) or (b).(d) the countries exporting the capital-intensive good will lose its comparative advantage.(e) None of the above.Answer: E39. If Australia has relatively more land per worker, and Belgium has relatively more capital perworker, then if trade were to open up between these two countries,(a) the relative price of the capital-intensive product would rise in Australia.(b) the world price of the land-intensive product would be higher than it had been in Belgium.(c) the world price of the land intensive product would be higher than it had been inAustralia.(d) the relative price of the land intensive product would rise in Belgium.(e) None of the above.Answer: C40. If Australia has more land per worker, and Belgium has more capital per worker, then if tradewere to open up between these two countries,(a) the real income of capital owners in Australia would rise.(b) the real income of labor in Australia would clearly rise.(c) the real income of labor in Belgium would clearly rise.(d) the real income of landowners in Belgium would fall.(e) the real incomes of capital owners in both countries would rise.Answer: D41. If trade opens up between the two formerly autarkic countries, Australia and Belgium, then(a) the real income of Australia and of Belgium will increase.(b) the real income of Australia but not of Belgium will increase.(c) the real income of neither country will increase.(d) the real income of both countries may increase.(e) the real income of both countries will increase.Answer: D42. If the price of food (a land intensive product) rises, then the income of capital owners will fallbecause(a) capital owners consume only food.(b) the real wage in terms of manufactures rises.(c) they must pay higher wages to maintain subsistence levels.(d) food is an element of organic capital for capitalists.(e) None of the above.Answer: B43. If Japan is relatively capital rich and the United States is relatively land rich, and if food isrelatively land intense then trade between these two, formerly autarkic countries will(a) lead to perfect specialization with Japan alone producing manufactures.(b) create a world relative price of food that is lower than that of the U.S.(c) lower the price of food in both countries.(d) raise the price of food in both countries.(e) None of the above.Answer: E44. The reason trade clearly benefits a country is that(a) it raises the real income of the more productive elements in society.(b) it lowers the real income of the less productive elements in society.(c) it increases the levels of consumption of everyone.(d) it increases society’s consumption choices.(e) None of the above.Answer: D45. As compared to potential gainers, those who stand to lose from trade(a) are likely to migrate to another country.(b) tend to be more effectively organized politically.(c) tend to reject compensation as smacking of socialism.(d) are universally opposed by economists who consider them parasites.(e) None of the above.Answer: B46. Those who stand to gain from trade(a) do not really care about the issue of income redistribution.(b) could not compensate losers since there are so many poor people.(c) could compensate losers but would rather not in modern industrial economies.(d) compensate losers at least partially through such legislation as unemploymentcompensation, or retraining grants.(e) None of the above.Answer: D47. Groups that lose from trade tend to lobby the government to(a) shift the direction of comparative advantage.(b) abolish the Specific Factor model from practical application.(c) provide public support for the relatively efficient sectors.(d) provide protection for the relatively inefficient sectors.(e) None of the above.Answer: D48. It was found that when the United States imposed steel quotas, this caused harm not only tosteel consumers, but also to many producers for whom steel is an important input. This insight(a) suggests that general equilibrium models of tariffs will demonstrate that the partialequilibrium deadweight loss triangles tend to overstate the tariff harm.(b) suggests that the deadweight loss triangles from partial equilibrium models tend tounderstate the harm to society of protectionism.(c) suggests that it is quite sensible that producers tend to support quotas.(d) suggests that steel production is an infant industry in the U.S.(e) None of the above.Answer: B49. It was found that when the United States placed quotas on imported Japanese semiconductors,this harmed the international competitiveness of U.S. computer manufacturers. This is a good illustration of the principle that(a) trade benefits the factor that is specific to the export sector.(b) protectionism helps manufacturers but harms consumers.(c) protectionism harms the factor that is specific to the export sector.(d) effective protection is not the same as a nominal tariff or tariff equivalent.(e) None of the above.Answer: D50. Ricardo’s model of comparative advantage demonstrated n o harm to any group in theeconomyas a result of free trade. This was probably because(a) Ricardo did not understand the concept of diminishing returns.(b) the specific factor model had not yet been invented.(c) Heckscher and Ohlin had not yet been born.(d) a model, which demonstrated such harm, would have been counter-productive toRicardo’s political or polemical aims.(e) None of the above.Answer: D51. When the Napoleonic Wars were over, the Corn Laws were enacted in England. This may beunderstood in terms of the following:(a) The Hecksher-Ohlin model.(b) The intra-trade model.(c) The monopolistic competition model(d) The scale economies model(e) None of the above.Answer: A52. If Gambinia has many workers but very little land and even less productive capital, then,following the specific factor model, we know that Gambinia has a comparative advantage in(a) manufactures.(b) food.(c) both manufactures and food.(d) neither manufactures nor food.(e) Not enough information given.Answer: E53. If, relative to its trade partners, Gambinia has many workers but very little land and even lessproductive capital, then, following the specific factor model, in order to help the country’seconomic welfare, the Gambinian government should(a) protect the manufacturing sector.(b) protect the agricultural sector.(c) protect both sectors.(d) not resort to protectionism(e) None of the above.Answer: DEssay Questions1. “A good cannot be both land- and labor-intensive.” Discuss.Answer: In a two good, two factor model, such as the original Heckscher-Ohlin framework, the factor intensities are relative intensities. Hence, the relevant statistic is eitherworkers per acre (or acres per worker); or wage per rental unit (or rental per wage).In order to illustrate the logic of the statement above, let us assume that theproduction of a broom requires 4 workers and 1 acre. Also, let us assume that theproduction of one bushel of wheat requires 40 workers and 80 acres. In this case theacres per person required to produce a broom is one quarter, whereas to produce abushel of wheat requires 2 acres per person. The wheat is therefore (relatively) landintensive, and the broom is (relatively) labor intensive.2. “No country is abundant in everything.” Discuss.Answer: the concept of relative (country) factor abundance is (like factor intensities) a relative concept. When we identify a country as being capital intensive, we mean that it hasmore capital per worker than does the other country. If one country has more capitalworker than another, it is an arithmetic impossibility that it also has more workersper unit capital.3. There is frequently a conflict between short-term and long-term interests in trade. Discuss.Answer: In trade models, the short term is typically defined as that (conceptual) period of time in which both the technology and the amount of factors of production are givenand cannot be changed. When we state that free trade can be shown to be an optimalpolicy under certain circumstances, we mean that in the short run, this policy canbring a country to an optimum level of consumption. However, there is noinconsistency in the proposition that the optimum short run solution may not be thesolution, which maximizes the likelihood of economic expansion or growth (the longrun). For example, a policy which maximizes consumption may not take into accountinter-temporal preferences, and hence may “short-change” future generations (orthose who care for future generations).4. International trade leads to complete equalization of factor prices. Discuss.Answer: This statement is typically “true . . . but.” Under a strict and limited set ofassumptions, such as the original Heckscher-Ohlin model which excludes countryspecific technologies; non- homothetic tastes; factor intensity reversals; large countrydifferences in (relative) factor abundances, more factors than goods, and anequilibrium solution within the “cone of specialization”; then it may be demonstratedthat internal consistency demands that the above stated sentence is “true.” However,the minute one relaxes any of the above listed assumptions one may easily identifysolutions, which contradict the factor price equalization theorem.5. Countries that are willing to tolerate an unusually high quantity of pollution relative to theirsupplies of other factors would tend to export “pollution-intensive” goods. Discuss using the Hechscher-Ohlin (H.O.) model.Answer: This statement is badly crafted. It seems to imply that pollution per say is a proper factor of production. That is, just as if you add a worker, you get additional product,so the marginal product of pollution is positive. The problem here is that pollution isnot reallya factor of production, but rather an externality, which may be more typical ofimported goods than exported ones. In such a case, the statement above is false.6. Countries do not in fact export the goods the H.O. theory predicts. Discuss.Answer: This statement is not true. Although one may find many cases where it seems to be true (e.g. the Leontieff Paradox), all one needs to do in order to render the abovestatement not (generally) true is to find one counter example. In fact, one can findlarge subsets of agricultural and commodity products in which the H.O predictionsare generally fulfilled. Labor-intensive countries such as Bangladesh do in factexport relatively labor-intensive goods. Capital-intensive countries such as Germanydo in fact export capital-intensive products (at least to South countries). Countriessuch as Costa Rica (“sunshine abundant”) tend to export bananas(sunshine-intensive products). The U.S. (a wheat-land-abundant country) doesindeed export wheat (a wheat-land intensive product). In fact, since the early 1980s,the Leontieff Paradox was not found to describe the U.S. trade data (hence ratifyingthe H.O. theory).7. Why is the H.O. model called the factor-proportions theory?Answer: The H.O. model explores the nature and the limitations of assuming that the sole determinant of comparative advantage is inter-country differences in (relative)factor proportions.8. Why do we observe the Leontief paradox?Answer: There are many possible answers. They may be classified into three groups. One would argue that the model, or theory is wrong. The other would argue that thetheory is correct (internally consistent and descriptive of real world data), but thereal world data is incorrectly perceived, defined or measured. The third would arguethat the statement itself is wrong, and that in fact the Leontieff paradox itself is notactually observed, but rather is due to faulty logical rendering of the original model.。
2021年宏观经济分析第4章练习题+答案
CHAPTER 4. FINANCIAL MARKETSMULTIPLE CHOICE QUESTIONSE 1. Which of the following is a characteristic of bonds?a. pay zero nominal interest.b. can be used for transactions.c. are sold for a price that varies inversely with the interest rate.d. all of the above.e. none of the above.E 2. Which of the following is a flow variable?a. income.b. money.c. financial wealth.d. all of the above.e. none of the above.E 3. Which of the following is a component of money?a. bonds.b. saving.c. income.d. stocks.e. none of the above.E 4. Which of the following is a component of money?a. coins held by the nonbank public.b. bills held by banks.c. checkable deposits.d. all of the aboveM 5. Which of the following will cause an increase in the amount of money that one wishes to hold?a. an increase in the interest rate increase.b. a reduction in the interest rate increase.c. a reduction in income.d. none of the aboveM 6. The money demand curve will shift to the right when which of the following occurs?a. an increase in income.b. a reduction in the interest rate.c. an increase in the money supply.d. all of the above.e. none of the above.M 7. The money demand curve will shift to the left when which of the following occurs?a. a reduction in the interest rateb. an increase in the interest ratec. an open market sale of bonds by the central bankd. an increase in incomee. none of the aboveE 8. Which of the following is NOT included as a component of the M1 definition of money?a. bonds.b. checkable deposits.c. coins and bills held by the nonbank public.d. all of the above.e. none of the above.M 9. In 2006, the average U.S. household held approximately how much currency (dollar bills and coins)?a. $50.b. $100.c. $600.d. $1600.e. none of the above.M 10. Which of the following countries has adopted the U.S. dollar as its own currency?a. Ecuador.b. Mexico.c. Canada.d. France.e. Australia.M 11. At the current interest rate, suppose the supply of money is less than the demand for money. Given this information, we know that:a. the price of bonds will tend increase.b. the price of bonds will tend to fall.c. production equals demand.d. the goods market is also in equilibrium.e. the supply of bonds also equals the demand for bonds.M 12. The interest rate will increase as a result of which of the following events?a. an increase in income.b. an open market purchase of bonds by the central bank.c. a reduction in income.d. all of the above.e. none of the above.E 13. Which of the following is NOT an asset on a bank's balance sheet?a. Reserves.b. Loans.c. checkable deposits.d. All of the above.e. None of the above.E 14. Which of the following is a liability on a bank's balance sheet?a. Checkable deposits.b. Reserves.c. Loans.d. All of the above.e. None of the above.E 15. Which of the following is a liability for the central bank?a. currency.b. bonds.c. savings accounts.d. loans.e. checkable deposits.M 16. Suppose a one-year discount bond offers to pay $1000 in one year and currently sells for $950. Given this information, we know that the interest rate on the bond isa. 5.3%.b. 9.5%%.c. 10%.d. 90%.e. 110%.M 17. Suppose a one-year discount bond offers to pay $1000 in one year and currently has a 15% interest rate.Given this information, we know that the bond's price must be:a. $869.56.b. $1150.c. $850.d. $950.e. none of the above.E 18. Banks are different from other financial intermediaries becausea. banks receive funds and make loans.b. some of a bank's deposits are money.c. banks can conduct open market operations on their own.d. banks do not need to hold reserves against their deposits.e. banks are open longer hours.M 19. Which of the following generally occurs when a central bank pursues expansionary monetary policy?a. the central bank purchases bonds and the interest rate increases.b. the central bank purchases bonds and the interest rate decreases.c. the central bank sells bonds and the interest rate increases.d. the central bank sells bonds and the interest rate decreases.M 20. Which of the following generally occurs when a central bank pursues contractionary monetary policy?a. the central bank purchases bonds and the interest rate increases.b. the central bank purchases bonds and the interest rate decreases.c. the central bank sells bonds and the interest rate increases.d. the central bank sells bonds and the interest rate decreases.M 21. Which of the following will occur when the central bank pursues expansionary monetary policy?a. a leftward shift in the money demand curve and a leftward shift in the money supply curveb. a rightward shift in the money demand curve and a leftward shift in the money supply curve.c. a leftward shift in the money demand curve and a rightward shift in the money supply curve.d. a rightward shift in the money demand curve and a rightward shift in the money supply curve.e. none of the above.M 22. Which of the following is a component of high powered money?a. bonds held by banks, loans, and bank reserves.b. currency in circulation plus bank reserves.c. currency in circulation plus checkable deposits.d. bonds held by banks plus checkable deposits.e. the sum of currency in circulation, bank reserves, and checkable deposits.M 23. For this question, assume that individuals do NOT hold currency (i.e., c = 0). If the ratio of reserves to deposits is .10, the money multiplier is:a. .1b. .9c. 4d. 5e. 10D 24. Which of the following will cause the money multiplier to become smaller?a. an increase in high powered money.b. a decrease in the ratio of reserves to checkable deposits.c. an increase in the public's preference for checking deposits as opposed to holding currency.d. a reduction in high powered money.e. none of the above.D 25. The money supply will tend to fall when which of the following occurs?a. a central bank sale of bonds.b. a decrease in the ratio of reserves to deposits.c. a shift in public preferences away from currency to checkable deposits.d. all of the above.e. none of the above.M 26. Which of the following events will cause the interest rate to increase?a. an open market sale of bondsb. an increase in the reserve deposit ratio (i.e., θ)c. an increase in incomed. all of the aboveE 27. The federal funds rate is determined in which of the following markets?a. the market for U.S. treasury securitiesb. the money marketc. the bond marketd. the market for central bank moneye. none of the aboveM 28. For this question, assume that individuals do NOT hold currency (i.e., c = 0). The money multiplier is equal to:a. 1b. 1/(1 - c)c. θd. 1/(1- θ)e. none of the aboveM 29. For this question, assume that individuals do NOT hold currency (i.e., c = 0).. The money multiplier is equal to:a. 1/(1-c)b. 1/[c + θ(1-c)]c. [c + θ(1-c)]d. 1/θe. none of the aboveD 30. For this question, assume that individuals hold both currency and checkable deposits. The moneymultiplier is equal to:a. 1/cb. 1/[c + θ(1-c)]c. [c + θ(1-c)]d. 1/θe. 1/(1-c)M 31. We would expect which of the following to occur when the central bank pursues expansionary monetary policy?a. an increase in bond prices and an increase in the interest rate (i)b. a reduction in bond prices and an increase in ic. an increase in bond prices and a reduction in id. a reduction in bond prices and a reduction in ie. none of the aboveM 32. We would expect which of the following to occur when the central bank pursues contractionary monetary policy?a. an increase in bond prices and an increase in the interest rate (i)b. a reduction in bond prices and an increase in ic. an increase in bond prices and a reduction in id. a reduction in bond prices and a reduction in ie. none of the aboveM 33. Based on our understanding of the determinants of the interest rate and bond prices, we know that a reduction in income will cause:a. an increase in bond prices and an increase in the interest rate (i)b. a reduction in bond prices and an increase in ic. an increase in bond prices and a reduction in id. a reduction in bond prices and a reduction in ie. none of the aboveM 34. We would expect which of the following to occur when the central bank conducts an open market sale of bonds?a. a reduction in the monetary base (H)b. a reduction in the money multiplierc. an increase in Hd. an increase in the money multipliere. both (c) and (d)M 35. We would expect which of the following to occur when the central bank conducts an open market purchase of bonds?a. a reduction in the monetary base (H)b. a reduction in the money multiplierc. an increase in the money multiplierd. an increase in the money supplyE 36. The U.S. government currently insures each bank account up to what level?a. $10,000b. $50,000c. $100,000d. $150,000M 37. An increase in the reserve ratio, θ, will cause:a. an increase in the monetary base (H)b. a reduction in Hc. an increase in the money multiplierd. a reduction in the money multipliere. none of the aboveM 38. A reduction in the reserve ratio, θ, will cause:a. an increase in the monetary base (H)b. a reduction in H and a reduction in the money multiplierc. an increase in the money multiplierd. a reduction in the money multiplierM 39. An increase in the parameter c, the proportion of money individuals wish to hold as currency, will tend to cause which of the following?a. an increase in the monetary base (H)b. a reduction in Hc. an increase in the money multiplierd. a reduction in the money multiplierM 40. A reduction in the parameter c, the proportion of money individuals wish to hold as currency, will tend to cause which of the following?a. an increase in the monetary base (H)b. a reduction in Hc. an increase in the money multiplierd. a reduction in the money multiplierM 41. An increase in income will tend to cause which of the following?a. an increase in the monetary base (H)b. a reduction in Hc. an increase in the interest rated. a reduction in the money multipliere. none of the aboveM 42. If individuals do not hold currency, we know that:a. M = Db. H = Rc. the money multiplier is 1/θd. all of the aboveM 43. If individuals do not hold checkable deposits, we know that:a. M = CUb. H = CUc. the money multiplier is 1d. all of the aboveM 44. An increase in the interest rate will cause:a. a reduction in the supply of central bank moneyb. a reduction in the demand for currencyc. a reduction in the demand for reservesd. all of the abovee. both b and cM 45. An increase in income will cause:a. a reduction in the supply of central bank moneyb. a reduction in the demand for currencyc. a reduction in the demand for reservesd. none of the abovee. both b and cM 46. An increase in income will cause:a. a reduction in the supply of central bank moneyb. a reduction in the demand for currencyc. an increase in the demand for reservesd. none of the aboveM 47. An open market sale of securities will tend to cause:a. a reduction in the supply of central bank moneyb. a reduction in the demand for currencyc. a reduction in the demand for reservesd. none of the aboveESSAY QUESTIONS1. First, explain why the money demand curve is downward sloping. Second, explain what factor(s) will cause shifts in the money demand curve.2. Explain what types of policies a central bank can implement to reduce the interest rate.3. Graphically illustrate and explain what effect an increase in real income will have on the money market.4. Graphically illustrate and explain what effect a purchase of bonds by the Federal Reserve will have on the money market.5. Use the market for central bank money to answer this question. Graphically illustrate and explain what effect a Federal Reserve purchase of bonds will have on this market and on the equilibrium interest rate.6. Use the market for central bank money to answer this question. Graphically illustrate and explain what effect an increase in the reserve deposit ratio ( ) will have on this market and on the equilibrium interest rate.7. Explain what effect changes in each of the following variables has on the demand for central bank money: (1) the interest rate, i; and (b) real income, Y.8. Discuss the tools of the Federal Reserve and explain how each can be used to change the money supply and equilibrium interest rate.9. What is the money multiplier and what factors determine its size?10. Use the money market to answer this question. Suppose there is a reduction in income. First, briefly explain what effect this will have on the interest rate. Second, explain all types of policies the central bank could implement to prevent this reduction in income from affecting the interest rate.ANSWERS TO MULTIPLE CHOICE QUESTIONS1. c2. b3. e4. d5. b6. a7. e8. e9. d10. a11. b12. b13. d14. a15. a16. a17. a18. b19. b20. c21. e22. b23. e24. e25. b26. d27. e28. e29. e30. b31. c32. b33. c34. a35. d36. c37. d38. c39. d40. c41. c42. d43. d44. e45. d46. c47. aANSWERS TO ESSAY QUESTIONS1. The money demand curve is downward sloping (with the interest rate on the vertical axis). It is assumed that money pays no interest. At the same time, individuals earn interest when they hold bonds. So, as the interest rate increases, individuals are more willing to incur the costs associated with converting bonds to money when they wish to buy goods. So, an increase in the interest rate causes a reduction in money demand. Money demand depends on the level of transactions and on the interest rate. As the level of transactions increases, individuals will increase money demand. Assuming that nominal income is correlated with nominal transactions, an increase in nominal income will cause an increase in money demand and shifts in the curve.2. Central banks have two options to reduce the interest rate: a central bank purchase of bonds or a reduction in the required reserve ratio. Both policies result in an increase in the money supply and a reduction in the interest rate.3. An increase in income will cause an increase in transactions and an increase in money demand. The money demand curve will shift to the right causing an excess demand for money and excess demand for bonds. The interest rate will rise to restore money market equilibrium. There is no change in money supply as a result of this.4. A Fed purchase of bonds will cause an increase in H and an increase in the money supply. At the initial interest rate, there will be an excess supply of money. The interest rate will fall to restore money market equilibrium. All else fixed, there will be no change in money demand.5. A Fed purchase of bonds will cause an increase in the supply of central bank money. To restore equilibrium in this market, the interest rate will have to fall. As it does, the quantity demanded for central bank money will rise and, therefore, restore equilibrium.6. An increase in the parameter θ will cause an increase in banks' demand for reserves and, therefore, an increase in the demand for central bank money. This will cause an excess demand for central bank money at the initial interest rate. In this case, the interest rate will rise to restore equilibrium.7. Interest rate. A reduction in the interest rate will cause an increase in money demand (movement along the demand curve). This will cause an increase in the demand for currency that will cause an increase in the demand for central bank money. The increase in the demand for money will also cause an increase in the demand for deposits and, therefore, an increase in banks' demand for reserves. This will also cause an increase in the demand for central bank money. In this case, we only move along the demand curve.Real income. An increase in Y will cause an increase in money demand and, as described above, an indirect increase in the demand for currency and reserves. So, this increase in Y will cause an increase in the demand for central bank money and a shift in the curve.8. The Fed has three tools: discount rate, open market operations, and the reserve ratio. An open market sale or purchase will cause a change in H and M. This will in turn cause a change in the money supply. A change in the required reserve ratio will cause a change in the money multiplier and, therefore, the money supply. When the money supply changes, the interest rate will change. Changes in the discount rate do not directly cause changes in the money supply.9. The money multiplier represents the effect of a given change in high powered money on the money supply. The money multiplier will be affected by changes in two parameters: c and θ. An increase in either parameter will causea reduction in the money multiplier.10. The reduction in income will cause a reduction in money demand, a leftward shift in the money demand curve, and a reduction in the interest rate. To prevent the drop in the interest rate, the central bank could pursue an open market sale of securities (to reduce the money supply) or it could increase the required reserve ratio (which would also reduce the money supply).。