
第九章习题答案final
1、电子波有何特征?与可见光有何异同?
答:电子波的波长较短,轴对称非均匀磁场能使电子波聚焦。
其波长取决于电子运动的速度和质量,电子波的波长要比可见光小5个数量级。
两者都是波,具有波粒二象性,波的大小、产生方式、聚焦方式等不同。
2、分析电磁透镜对波的聚焦原理,说明电磁透镜的结构对聚焦能力的影响。
答:原理:通电线圈产生一种轴对称不均匀分布的磁场,磁力线围绕导线呈环状。
磁力线上任一点的磁感应强度B可以分解成平行于透镜主轴的分量Bz和垂直于透镜主轴的分量Br。
速度为V的平行电子束进入透镜磁场时在A点处受到Br分量的作用,由右手法则,电子所受的切向力Ft的方向如下图;Ft使电子获得一个切向速度Vt,Vt与Bz分量叉乘,形成了另一个向透镜主轴靠近的径向力Fr,使电子向主轴偏转。
当电子穿过线圈到达B点位置时,Br的方向改变了180度,Ft随之反向,但是只是减小而不改变方向,因此,穿过线圈的电子任然趋向于主轴方向靠近。
结果电子作圆锥螺旋曲线近轴运动。
当一束平行与主轴的入射电子束通过投射电镜时将会聚焦在轴线上一点,这就是电磁透镜电子波的聚焦对原理。
电磁透镜的结构对电磁场有很大的影响。
上图为一种实际常用的带有铁壳以及极靴的电磁透镜示意图。
1)电磁透镜中为了增强磁感应强度,通常将线圈置于一个由软磁材料(纯铁或低碳钢)制成的具有内环形间隙的壳子里,此时线圈的磁力线都集中在壳内,磁感应强度得以加强。
狭缝的间隙越小,磁场强度越强,对电子的折射能力越大。
2)增加极靴后的磁线圈内的磁场强度可以有效地集中在狭缝周围几毫米的范围内,显著提高了其聚焦能力。
3、电磁透镜的像差是怎样产生的,如何来消除或减小像差?
答:电磁透镜的像差可以分为两类:几何像差和色差。
几何像差是因为投射磁场几何形状上的缺陷造成的,色差是由于电子波的波长或能量发生一定幅度的改变而造成的。
几何像差主要指球差和像散。
球差是由于电磁透镜的中心区域和边缘区域对电子的折射能力不符合预定的规律造成的,像散是由透镜磁场的非旋转对称引起的。
消除或减小的方法:
球差:减小孔径半角或缩小焦距均可减小球差,尤其小孔径半角可使球差明显减小。
像散:引入一个强度和方向都可以调节的矫正磁场即消像散器予以补偿。
色差:采用稳定加速电压的方法有效地较小色差。
4、说明影响光学显微镜和电磁透镜分辨率的关键因素是什么?如何提高电磁透镜的分辨率?
答:光学显微镜的分辨本领取决于照明光源的波长。
电磁透镜的分辨率由衍射效应和球面像差来决定,球差是限制电磁透镜分辨本领的主要因素。
若只考虑衍射效应,在照明光源和介质一定的条件下,孔径角α越大,透镜的分辨本领越高。
若同时考虑衍射和球差对分辨率的影响,关键在确定电磁透镜的最佳孔径半角,使衍射效应斑和球差散焦斑的尺寸大小相等。
5、电磁透镜景深和焦长主要受哪些因素影响?说明电磁透镜的景深大、焦长长,是什么因素影响的结果?假设电磁透镜没有像差,也没有衍射Airy 斑,即分辨率极高,此时景深和焦长如何?
答:电磁透镜景深与分辨本领0r ∆、孔径半角α之间关系:
.2200ααr tg r Df ∆≈∆=表明孔径半角越小、景深越大。
透镜集长L D 与分辨本领0r ∆,像点所张孔径半角β的关系:ββM r M r D L 002tan 2∆≈∆=,M αβ=,202M r D L α∆=∴ ,M 为透镜放大倍数。
当电磁透镜放大倍数和分辨本领一定时,透镜焦长随孔径半角减小而增大。
电磁透镜的景深长、焦长长,是由于小孔径半角影响的结果。
如果电磁透镜没有像差,也没有衍射Airy 斑,即分辨率极高,此时没有景深和焦长。
一、填空题
1、电磁透镜的像差包括 球差 、 像散 和 色差 。
2、透射电子显微镜的分辨率主要受 衍射效应 和 球面像差 两因素影响。
3、透射电子显微镜中用磁场来使电子聚焦成像的装置是电磁透镜。
4、像差分为两类,即几何像差和色差。
二、名词解释
1、球差:即球面像差,是由于电磁透镜的中心区域和边缘区域对电子的折射能力不同造成的。
轴上物点发出的光束,经电子光学系统以后,与光轴成不同角度的光线交光轴于不同位置,因此,在像面上形成一个圆形弥散斑,这就是球差。
像散:由透镜磁场的非旋转对称引起的像差。
色差:由于电子的波长或能量非单一性所引起的像差,它与多色光相似,所以叫做色差。
2、景深:透镜物平面允许的轴向偏差。
焦长:透镜像平面允许的轴向偏差。
在成一幅清晰像的前提下,像平面不变,景物沿光轴前后移动的距离称“景深”;景物不动,像平面沿光轴前后移动的距离称“焦长”。
3、Ariy斑:物体上的物点通过透镜成像时,由于衍射效应,在像平面上得到的并不是一个点,而是一个中心最亮、周围带有明暗相间同心圆环的圆斑,即所谓Airy斑。
4、孔径半角:孔径半角是物镜孔径角的一半,而物镜孔径角是物镜光轴上的物体点与物镜前透镜的有效直径所形成的角度。
因此,孔径半角是物镜光轴上的物体点与物镜前透镜的有效直径所形成的角度的一半。
三、选择题
1、透射电子显微镜中可以消除的像差是( B )。
A.球差;B. 像散;C. 色差。
2、由于电磁透镜中心区域和边缘区域对电子折射能力不同而造成的像差称为(A )
A、球差
B、像散
C、色差
D、背散
3、由于透镜磁场非旋转对称而引起的像差称为(B )
A、球差
B、像散
C、色差
D、背散
4、由于入射电子波长的非单一性造成的像差称为(C )
A、球差
B、像散
C、色差
D、背散
5、制造出世界上第一台透射电子显微镜的是(B )
A、德布罗意
B、鲁斯卡
C、德拜
D、布拉格
四、是非题
1、TEM的分辨率既受衍射效应影响,也受透镜的像差影响。
(√)
2、孔径半角α是影响分辨率的重要因素,TEM中的α角越小越好。
(×)
3、TEM中主要是电磁透镜,由于电磁透镜不存在凹透镜,所以不能象光学显微镜那样通过凹凸镜的组合设计来减小或消除像差,故TEM中的像差都是不可消除的。
(×)
4、TEM的景深和焦长随分辨率Δr0的数值减小而减小;随孔径半角α的减小而增加;随放大倍数的提高而减小。
(×)
5、电磁透镜的景深和焦长随分辨率Δr0的数值减小而减小;随孔径半角α的减小而增加(√)
6、光学显微镜的分辨率取决与照明光源的波长,波长越短,分辨率越高(√)
7、波长越短,显微镜的分辨率越高,因此可以采用波长较短的γ射线作为照明光源。
(×)
8、用小孔径角成像时可使球差明显减小。
(√)
9、限制电磁透镜分辨率的最主要因素是色差。
(×)
10、电磁透镜的景深越大,对聚焦操作越有利。
(√)
五、问答题
1、什么是分辨率,影响透射电子显微镜分辨率的因素是哪些?
答:分辨率:两个物点通过透镜成像,在像平面上形成两个Airy 斑,如果两个物点相距较远时,两个Airy 斑也各自分开,当两物点逐渐靠近时,两个Airy斑也相互靠近,直至发生部分重叠。
根据Lord Reyleigh建议分辨两个Airy斑的判据:当两个Airy斑的中心间距等于Airy斑半径时,此时两个Airy斑叠加,在强度曲线上,两个最强峰之间的峰谷强度差为19%,人的肉眼仍能分辨出是两物点的像。
两个Airy斑再相互靠近,人的肉眼就不能分辨出是两物点的像。
通常两Airy斑中心间距等于Airy斑半径时,物平面相应的两物点间距成凸镜能分辨的最小间距即分辨率。
影响透射电镜分辨率的因素主要有:衍射效应和电镜的像差(球差、像散、色差)等。
2、影响电磁透镜景深和焦长的主要因素是什么?景深和焦长对透射电子显微镜的成像和设计有何影响?
答:(1)把透镜物平面允许的轴向偏差定义为透镜的景深,影响它的因素有电磁透镜分辨率、孔径半角,电磁透镜孔径半角越小,景深越大,如果允许较大的像分辨率(取决于样品),那么透镜的景深就更大了;把透镜像平面允许的轴向偏差定义为透镜的焦长,影响它的因素有分辨率、像点所张的孔径半角、透镜放大倍数,当电磁透镜放大倍数和分辨率一定时,透镜焦长随孔径半角的减小而增大。
大的景深和焦长不仅使透射电镜成像方便,而且电镜设计荧光屏和相机位置非常方便。
(完整word版)应用回归分析,第9章课后习题参考答案

第9章 含定性变量的回归模型思考与练习参考答案9.1 一个学生使用含有季节定性自变量的回归模型,对春夏秋冬四个季节引入4个0—1型自变量,用SPSS 软件计算的结果中总是自动删除了其中的一个自变量,他为此感到困惑不解。
出现这种情况的原因是什么?答:假如这个含有季节定性自变量的回归模型为:t t t t kt k t t D D D X X Y μαααβββ++++++=332211110其中含有k 个定量变量,记为x i 。
对春夏秋冬四个季节引入4个0—1型自变量,记为D i ,只取了6个观测值,其中春季与夏季取了两次,秋、冬各取到一次观测值,则样本设计矩阵为:⎪⎪⎪⎪⎪⎪⎪⎪⎭⎫⎝⎛=000110010110001010010010100011)(616515414313212111k k k k k k X X X X X X X X X X X XD X,显然,(X ,D)中的第1列可表示成后4列的线性组合,从而(X ,D)不满秩,参数无法唯一求出。
这就是所谓的“虚拟变量陷井",应避免。
当某自变量x j 对其余p —1个自变量的复判定系数2j R 超过一定界限时,SPSS 软件将拒绝这个自变量x j 进入回归模型.称Tol j =1—2j R 为自变量x j 的容忍度(Tolerance ),SPSS 软件的默认容忍度为0。
0001。
也就是说,当2j R >0.9999时,自变量x j 将被自动拒绝在回归方程之外,除非我们修改容忍度的默认值。
而在这个模型中出现了完全共线性,所以SPSS 软件计算的结果中总是自动删除了其中的一个定性自变量。
⎪⎪⎪⎪⎪⎭⎫⎝⎛=k βββ 10β⎪⎪⎪⎪⎪⎭⎫ ⎝⎛=4321ααααα9。
2对自变量中含有定性变量的问题,为什么不对同一属性分别建立回归模型,而采取设虚拟变量的方法建立回归模型?答:原因有两个,以例9.1说明。
一是因为模型假设对每类家庭具有相同的斜率和误差方差,把两类家庭放在一起可以对公共斜率做出最佳估计;二是对于其他统计推断,用一个带有虚拟变量的回归模型来进行也会更加准确,这是均方误差的自由度更多。
数学分析第09章答案
第九章 再论实数系§1 实数连续性的等价描述1.求数列}{n x 的上、下确界(若}{n x 无上(下)确界,则称)(-∞∞+是}{n x 的上(下)确界):(1)nx n 11-=; (2)])2(2[n n n x -+=;(3))3,2,1(11,122 =+==+k k x k x k k ; (4)nn x n n 1])1(1[+-+=;(5)nn n nx )1(21-+=;(6)32cos 11πn n n x n +-=. 解(1)0}inf{,1}sup{==n n x x ; (2)-∞=+∞=}inf{,}sup{n n x x ; (3)1}inf{,}sup{=+∞=n n x x ; (4)0}inf{,3}sup{==n n x x ; (5)1}inf{,5}sup{==n n x x ; (6)21}inf {,1}sup{-==n n x x . 2.设)(x f 在D 上定义,求证: (1) )}({inf )}({sup x f x f Dx Dx ∈∈-=-;(2) )}({sup )}({inf x f x f Dx Dx ∈∈-=-.证明 (1)设a x f =)}(inf{,则D x ∈∀,都有a x f ≥)(,因而a x f -≤-)(,又由于0>∀ε,都D x ∈∃ε,使得εε+<a x f )(,因而εε-->-a x f )(,因此)}({inf )}({sup x f x f Dx Dx ∈∈-=-.(2) 设b x f Dx =∈)}({sup ,则D x ∈∀有b x f ≤)(,从而b x f -≥-)(,又由于,0>∀ε都D x ∈∃ε,使得εε->b x f )(,从而εε+-<-b x f )(,因此)}({sup )}({inf x f x f Dx Dx ∈∈-=-.3.设E sup =β,且E ∉β,试证自E 中可选取数列}{n x 且n x 互不相同,使β=∞→n n x lim ;又若E ∈β,则情形如何?证明 由已知条件知E sup =β且E ∉β,因而(1) E x ∈∀,有β<x ;(2) 0>∀ε,都存在E x ∈ε,使得εβε->x . 由(1)、(2)知:对1=ε,存在E x ∈1,使得ββ<<-11x ;对},21min{1x -=βε,E x ∈∃2,使得ββ<<-221x 并且112)(x x x =-->ββ;对},31min{2x -=βε,E x ∈∃3,使得ββ<<-231x 并且223)(x x x =-->ββ;…如此继续下去,得数列}{n x 且n x 互不相同,并且β=∞→n n x lim .若E ∈β,则结论不真,如⎭⎬⎫⎩⎨⎧=n E 1,则1s u p =E ,但没有n x 互不相同的数列}{n x ,使1lim =∞→n n x .4. 试证收敛数列必有上确界和下确界,趋于∞+的数列必有下确界,趋于∞-的数列必有上确界.证明 (1) 由于收敛数列是非空有界数列,且既有上界又有下界,因而有确界定理知其必有上确界和下确界;(2) 设+∞=∞→n n x lim ,则N ∃,当N n >时0>n x ,因而}0,,,,min{21N x x x 是数列}{n x 的下界,由确界原理知数列}{n x 存在下确界;(3) 设-∞=∞→n n x lim ,则N ∃,当N n >时0<n x ,因而}0,,,,max{21N x x x 是数列}{n x 的上界,由确界定理知数列}{n x 存在上确界.5.试分别举出满足下列条件的数列:(1)有上确界无下确界的数列;(2)含有上确界但不含有下确界的数列; (3)既含有上确界又含有下确界的数列;(4)既不含有上确界又不含有下确界的数列,其中上、下确界都有限.解(1)有上确界无下确界的数列,如}{}{n x n -=有上确界1}sup{-=n x ,但无下确界;(2)含有上确界但不含有下确界的数列,如取⎭⎬⎫⎩⎨⎧=n x n 1}{,则该数列含有它的上确界1}sup{=n x ,但下确界0}inf{=n x ,该数列不含有0;(3)既含有上确界又含有下确界的数列,如⎭⎬⎫⎩⎨⎧-+=n x n n )1(1}{,既含有上确界1,又含有下确界0;(4)既不含有上确界又不含有下确界的数列,其中上、下确界都有限,如⎪⎪⎩⎪⎪⎨⎧∈=-∈+==++.,213;,121Z k k n nZ k k n n x n则数列}{n x 有上确界3和下确界0,该数列}{n x 上含其上、下确界3和0.§2 实数闭区间的紧致性1.利用有限覆盖定理9.2证明紧致性定理9.4.证明 设数列}{n x 有界,即存在R b a ∈,,使得对N n ∈∀,都有b x a n ≤≤.下证}{n x 有收敛子列.(1)若}{n x 存在子列}{k n x 是常数列,则}{k n x 是}{n x 的收敛子列.(2)若}{n x 不存在是常数列的子列,下证}{n x 有收敛子列,为此设}|{N n x X n ∈=,则X 是无限点集.反设}{n x 没有收敛的子数列,则],[b a x ∈∀都不是}{n x 的任一子数列的极限,因此对],[b a x ∈∀,都存在开区间),(x x x v u I =,使得x I x ∈且X I x 是有限集(否则对包含x的任一开区间),(x x v u 都有X 的无穷项,则x 是}{n x 的某一子列的极限),因此所有开区间x I 构成闭区间],[b a 的一个开覆盖Ω,由有限覆盖定理知存在有限数m ,使i x mi I b a 1],[=⊂ ,因而有)()()()()(],[3211X I X I X I X I X I X b a m i x x x x x mi =⊂=,注意到上式右端每一项都是有限集,故X b a ],[为有限集,矛盾!综合(1)(2)知}{n x 必有一收敛的子数列. 2.利用紧致性定理证明单调有界数列必有极限.证明 设数列}{n x 单调递增且有上界,则}{n x 是有界数列,由紧致性定理知数列}{n x 必有收敛子数列}{k n x ,设c x k n k =∞→lim ,则由}{n x 单调递增知c 必为数列}{n x 的上界,且根据数列极限的定义知,,0K ∃>∀ε当K k >时,有ε<-c x k n ,即εε+<<-c x c k n ,特别地 ε->+c x K n 1,取1+=k n N ,则当1+=>k n N n 时,由数列}{n x 单调递增且c 为它的上界知εε+<≤≤<-+c c x x c n n K 1,即ε<-c x n ,从而c x n n =∞→lim ,即单调递增有上界数列必有极限.同理可证}{n x 单调递减有下界时必有极限,因而单调有界原理成立.3.用区间套定理证明单调有界数列必有极限.证明 不妨假设数列}{n x 单调递增有上界(}{n x 单调递减有下界可同理证明),即存在R b ∈,使得b x x x a n ≤≤≤≤≤= 21,下证数列}{n x 有极限.若b a =,则}{n x 为常驻列,故}{n x 收敛,因而以下假设b a <. 取b b a a ==11,,二等分区间],[11b a ,分点为211b a +,若211b a +仍为}{n x 的上界,则令2,11212b a b a a +==;若211b a +不是}{n x 的上界,即存在m ,使211b a x m +>,则令12112,2b b b a a =+=. 二等分区间],[22b a ,分点为222b a +,若222b a +为}{n x 的上界,则令2,22323b a b a a +==;若222b a +不是}{n x 的上界,则令 .,223223b b b a a =+=依此类推得一闭区间套{}],[n n b a ,每一个区间的右端点都是}{n x 的上界,由闭区间套定理知存在唯一的R c ∈,使得c 属于所有闭区间,下证数列}{n x 的极限为c .由于02lim)(lim 1=-=--∞→∞→n n n n n ab a b ,故根据数列极限的定义,0>∀ε,存在N ,当N n >时,都有2ε<-n n a b ,而],[n n b a c ∈,故),(],[εε+-⊂c c b a n n . (*)另一方面,由闭区间套的构造知K ∃,使得n K n b x a ≤≤,故对K n >∀,由于K n x x >,故n n K n b x x a ≤≤≤. 而由(*)知εε+<<-c x c n ,即ε<-c x n ,从而c x n n =∞→lim ,因而单调有界数列必有极限.4.试分析区间套定理的条件:若将闭区间列改为开区间列,结果怎样?若将条件⊃⊃],[],[2211b a b a 去掉或将条件0→-n n a b 去掉,结果怎样?试举例说明.分析(1)若将闭区间列改为开区间列,结果不真.如开区间列⎭⎬⎫⎩⎨⎧⎪⎭⎫ ⎝⎛n 1,0满足001lim =⎪⎭⎫ ⎝⎛-∞→n n 且 ⊃⎥⎦⎤⎢⎣⎡⊃⊃⎥⎦⎤⎢⎣⎡⊃⎥⎦⎤⎢⎣⎡⊃⎥⎦⎤⎢⎣⎡n 1,031,021,011,0,但不存在r ,使r 属于所有区间.(2)若将定理其它条件不变,去掉条件 ⊃⊃],[],[2211b a b a ,则定理仍不成立,如⎭⎬⎫⎩⎨⎧⎥⎦⎤⎢⎣⎡+n n n 1,是闭区间列,且0→-n n a b ,但显然不存在r ,使r 属于所有区间. (3)若去掉定理条件0→-n n a b ,则定理仍不成立,如闭区间序列⎭⎬⎫⎩⎨⎧⎥⎦⎤⎢⎣⎡+-n n 13,11满足 ⊃⊃],[],[2211b a b a ,此时区间]3,1[内任意一点都属于闭区间序列的任何区间,与唯一性矛盾.5.若}{n x 无界,且非无穷大量,则必存在两个子列∞→k n x ,a x k m →(a 为有限数). 证明 由于}{n x 无界,故N k ∈∀,都存在k n x ,使得k x k n >,因而∞=∞→k n k x lim .又由于}{n x 不是无穷大量,根据无穷大量否定的正面陈述知0M ∃,对0>∀K ,存在K m k >,使得0||M x k m <. 从而对于0>∀K ,数列}{k m x 为有界数列,从而必有收敛子列}{k m x .故结论成立.6.有界数列}{n x 若不收敛,则必存在两个子列b x a x k k m n →→,)(b a ≠. 证明 由于}{n x 为有界数列,由紧致性定理知数列}{n x 必有收敛的子列}{k n x ,不妨设)(∞→→k a x k n ,又因为数列}{n x 不收敛于a ,故从}{n x 中去掉}{k n x 后所得的项还有无穷多项(否则数列}{n x 就收敛于a ).记其为数列}{k n x ,又因为}{k n x 为有界数列,故有收敛子列,设此子列的极限为b ,则b a ≠,而此子列也是}{n x 的子列,故设其为}{k m x ,因而)(lim b a b x k m k ≠=∞→.7.求证:数列}{n a 有界的充要条件是,}{n a 的任何子数列}{k n a 都有收敛的子数列. 证明 必要性:由紧致性定理知结论成立.充分性:反设数列}{n a 无界.若}{n a 是无穷大量,则}{n a 的任何子列都不存在收敛的子列,矛盾;若}{n a 不是无穷大量,则由第5题知}{n a 有一子列}{k n a 是无穷大量,从而}{k n a 没有收敛的子数列,也矛盾.因而数列}{n a 有界.8.设)(x f 在],[b a 上定义,且在每一点处函数的极限存在,求证:)(x f 在],[b a 上有界.证明 对],[b a t ∈∀,由于)(x f 在t 处的极限存在,故设A x f tx =→)(lim ,则对01>=ε,存在0>t δ,x ∀,当t t x δ<-<||0时,有1)(=<-εA x f ,从而1||)(+<A x f ,取{}1||),(max +=A t f M ,则),(t t t t x δδ--∈∀,都有M x f <)(,即)(x f 在区间),(t t t t δδ--上有界.对所有],[b a t ∈,在1=ε下所取的t δ为半径的开区间{}],[|),(b a t t t t t ∈+-δδ构成闭区间],[b a 上的一个开覆盖,由有限覆盖定理知,存在],[,,,21b a t t t n ∈ ,使得),(],[1i i t i t i ni t t b a δδ+-⊂= ,而)(x f 在每个区间),(i i t i t i t t δδ+-),,2,1(n i =上有界,又由于区间个数有限,故)(x f在],[b a 上有界.9.设)(x f 在],[b a 无界,求证:存在],[b a c ∈,对任意0>δ,函数)(x f 在],[),(b a c c δδ+-上无界.证明 反设结论不真,即],[b a c ∈∀,0>∃c δ,函数)(x f 在],[),(b a c c c c δδ+-上有界,则对所有的c ,{}],[|),(b a c c c c c ∈+-δδ构成区间],[b a 的一个开覆盖,由有限覆盖定理知其有有限子覆盖,即],[,,,21b a c c c n ∈∃ ,使),(],[1i i c i c i ni c c b a δδ+-⊂= ,由于函数在每一个],[),(b a c c i i c i c i δδ+-有界,而n 是有限数,故)(x f 在],[b a 有界,矛盾.因此结论成立.10.设)(x f 是),(b a 上的凸函数,且有上界,求证:)(lim ),(lim x f x f bx ax -+→→存在. 证明 由于)(x f 在),(b a 上有上界,故0>∃M ,对M x f b a x ≤∈∀)(),,(.先证明)(lim x f bx -→存在. 在区间),(b a 中任取一点0x ,并令 00)()()(x x x f x f x g --=,则由)(x f 是),(b a 上的凸函数知)(x g 在),(0b x 上递增,在),(0b x 中任取一点1x ,考察区间),(1b x ,),(1b x x ∈∀,由于1000)()()()(x x x f M x x x f x f x g --≤--=,即)(x g 在),(1b x 上有上界,从而)(x g 在),(1b x 上单调递增且有上界,由定理3.12知)(lim x g b x -→存在,不妨令A x g bx =-→)(lim ,则 )()()()()()(lim )(lim 000000x f x b A x f x x x f x f x x x f b x b x +-=⎥⎦⎤⎢⎣⎡+--⋅-=--→→, 即)(lim x f bx -→存在. 再证明)(lim x f ax +→存在. 由于)(x f 是),(b a 上的凸函数,从而)(x g 在),(0x a 上递增,在),(0x a 中任取一点2x ,考察区间),(2x a ,),(2x a x ∈∀,由于ax Mx f x x x f x f x x x f x f x g --≥--=--=000000)()()()()()(, 即)(x g 在),(2x a 上有下界,从而)(x g 在),(2x a 上单调递增且有下界,由定理3.12的推论知)(lim x g ax +→存在,设B x g ax =+→)(lim ,则 )()()()()()(lim )(lim 000000x f B x a x f x x x f x f x x x f a x a x +-=⎥⎦⎤⎢⎣⎡+--⋅-=++→→, 即)(lim x f ax +→也存在. 11.设)(x f 在],[b a 上只有第一类间断点,定义)0()0()(--+=x f x f x ω.求证:任意εωε≥>)(,0x 的点x 只有有限多个.证明 反证法,使用区间套定理. 根据结论,反设存在00>ε,在],[b a 上使0)(εω≥x 的点有无限多个.记],[],[11b a b a =,二等分区间],[11b a ,则在⎥⎦⎤⎢⎣⎡+⎥⎦⎤⎢⎣⎡+111111,2,2,b b a b a a 中至少有一个区间含有无限多个x 使0)(εω≥x ,记此区间为],[22b a ,再二等分区间],[22b a ,在⎥⎦⎤⎢⎣⎡+⎥⎦⎤⎢⎣⎡+222222,2,2,b b a b a a 中至少有一个区间含有无限多个x 使0)(εω≥x ,记此区间为 ],,[33b a ,如此继续下去,得闭区间套],[n n b a ,且每个区间],[n n b a 中含有无限多个x 使0)(εω≥x .由区间套定理可知存在唯一 ,2,1],,[=∈n b a r n n由于)(x f 在],[b a 上只有第一类间断点,而],[b a r ∈,故)0(+r f 和)0(-r f 存在,设B r f A r f =-=+)0(,)0(,则对上述00>ε,存在),(,011δδ+∈∀>r r x 时,有2)(0ε<-A x f ,即2)(2εε+<<-A x f A ,从而由极限不等式知,当),(1δ+∈r r x 时,0)(εω<x ;同理存在),(,022r r x δδ-∈∀>时,0)(εω<x .取{}21,min δδδ=,则在),(δδ+-r r 上满足0)(εω≥x 的点至多只能有r 一个点.而根据区间套性质知,N n N >∀∃,时,都有),(],[δδ+-⊂r r b a n n ,从而在],[n n b a 中最多只能有一个点,使得0)(εω≥x ,这与区间套的构造矛盾.故原结论成立.12.设)(x f 在],0[+∞上连续且有界,对),(+∞-∞∈∀a ,a x f =)(在),0[+∞上只有有限个根或无根,求证:)(lim x f x +∞→存在.证明 由)(x f 在],0[+∞上有界知)(x f 在],0[+∞上既有上界又有下界,不妨设上界为v ,下界为u ,若v u =,则v u x f x ==+∞→)(lim ,结论必然成立,故以下假定v u <. 令],[],[11v u v u =,二等分区间],[11v u ,分点为211v u +,由于2)(11v u x f +=在),0[+∞上只有有限个根或无根,而且)(x f 连续,因而11,0X x X >∀>∃时,有2)(11v u x f +>或2)(11v u x f +<.若2)(11v u x f +>,令⎥⎦⎤⎢⎣⎡+=11122,2],[v v u v u ,若2)(11v u x f +<,则令⎥⎦⎤⎢⎣⎡+=2,],[11122v u u v u ,因此1X x >∀时,],[)(22v u x f ∈,即22)(v x f u ≤≤.二等分区间],[22v u ,分点为222v u +,由于2)(22v u x f +=在),0[+∞上只有有限个根或无根且)(x f 连续,故212,X x X X >∀>∃时,有2)(22v u x f +>或2)(22v u x f +<.若2)(22v u x f +>,令⎥⎦⎤⎢⎣⎡+=22233,2],[v v u v u ,反之令⎥⎦⎤⎢⎣⎡+=2,],[22233v u u v u ,因此2X x >∀时,],[)(33v u x f ∈,即33)(v x f u ≤≤. 依此类推,得一区间套]},{[n n v u ,而且由区间套的构造知,n n n X x X X >∀>∃-,1时,n n v x f u ≤≤)(.由区间套定理知存在唯一的 ,2,1],,[=∈n v u r n n ,下证r x f x =+∞→)(lim .事实上,对0>∀ε,由闭区间套]},{[n n v u 的构造知,存在N ,N n >∀时,有),(],[εε+-⊂r r v u n n ,特别地取1+=N n ,则),(],[11εε+-⊂++r r v u N N ,按区间套的构造知11,++>∀∃N N X x X 时,),(],[)(11εε+-⊂∈++r r v u x f N N ,即εε+<<-r x f r )(,从而ε<-r x f )(,即r x f x =+∞→)(lim ,也就是说)(lim x f x +∞→存在.§3 实数的完备性1.设)(x f 在),(b a 连续,求证:)(x f 在),(b a 一致连续的充要条件是)(lim x f ax +→与)(lim x f b x -→都存在.证明 )⇒必要性由)(x f 在),(b a 一致连续知,0,0>∃>∀δε,),(,b a x x ∈'''∀且δ<''-'||x x 时,都有ε<''-')()(x f x f .特别地,当),(,δ+∈'''a a x x 时,δ<''-'x x ,故ε<''-')()(x f x f ,由Cauchy 收敛原理知)(lim x f a x +→存在.同理可知)(lim x f b x -→也存在.)⇐充分性证法1 0>∀ε,由)(lim x f a x +→存在知1δ∃,),(,1δ+∈'''∀a a x x 时,ε<''-')()(x f x f ,又由于)(lim x f b x -→也存在,故2δ∃,),(,2b b x x δ-∈'''∀时,ε<''-')()(x f x f .取⎭⎬⎫⎩⎨⎧-=4,2,2min 21a b δδδ,则由以上两条知)(x f 在),[],,(b b a a δδ-+上一致连续,而又因为)(x f 在],[δδ-+b a 上连续,因而一致连续,因此)(x f 在],(δ+a a 、],[δδ-+b a 、),[b b δ-上均一致连续,因此)(x f 在),(b a 一致连续.证法2 由已知)(lim x f ax +→与)(lim x f bx -→ 都存在,设B x f A x f bx ax ==-+→→)(lim ,)(lim ,令⎪⎩⎪⎨⎧=∈==.);,()(;)(b x B b a x x f a x Ax F则)(x F 在],[b a 连续,因而一致连续,从而)(x F 在),(b a 一致连续,而)(x F 在),(b a 上就是)(x f ,因而)(x f 在),(b a 上一致连续.2.求证数列nx n 1211+++= ,当∞→n 时的极限不存在.证明 利用Cauchy 收敛原理的否定形式证明. 取0,0210>∀>=N ε,任取N n >,则N n >2,从而 nn n x x n n 2121112+++++=-021212121212111ε==+++>+++++>n n n n n n , 由Cauchy 收敛原理的否定知数列nx n 1211+++= 当∞→n 时的极限不存在.3.利用Cauchy 收敛原理讨论下列数列的收敛性. (1))||,1||(2210M a q q a q a q a a x k n n n ≤<++++= ;(2)n n n x 2sin 22sin 21sin 12++++= ; (3)nx n n 1)1(312111+-+-+-= . 解(1)0>∀ε,由1||<q 知0lim 1=+∞→n n q,从而N ∃,N n >∀时,有εMq qn ||1||1-<+,对上述N m n N >∀,,时(不妨n m >),有m n n m n n m n x x x x x x x x +++≤+++=-++++ 2121++=++++≤++++++221121||||||||n n n n m n n q a q a x x x ()εε=-⋅-<-=++≤+++Mq q M q q M q q M n n n ||1||1||1||||||121.由Cauchy 收敛原理知数列}{n x 收敛.(2)这是(1)中21,sin ,10===q k a a k 的特殊情形,由于21||,1<≤q a k ,故数列}{n x 收敛.(3)证法1 利用Cauchy 收敛原理.0>∀ε,由01lim=∞→n n 知,N ∃,N n >∀时ε<n1,对上述N m n N >∀,,时(不妨n m >),有 mn n x x m n n m n 1)1(21)1(11)1(132+++-+++-++-=- mn n n m 1)1(21111---+++-+=. 由于01)1(21111>-+++-+--mn n n m ,故 mn n x x n m m n 1)1(21111---+++-+=- .若n m -为偶数,则mn n x x n m m n 1)1(21111---+++-+=- m m m n n n 11121312111-⎪⎭⎫ ⎝⎛-----⎪⎭⎫ ⎝⎛+-+-+= ε<+≤11n . 若n m -为奇数,则mn n x x n m m n 1)1(21111---+++-+=- ⎪⎭⎫ ⎝⎛----⎪⎭⎫ ⎝⎛+-+-+=m m n n n 111312111 ε<+≤11n . 因而由Cauchy 收敛原理知数列}{n x 收敛.证法2 先考虑数列}{n x 的偶子列}{2n x ,由于22131211221)1(3121132)1(2+--+-=+-+-+-=++n n x n n ⎪⎭⎫ ⎝⎛+-++⎪⎭⎫ ⎝⎛--++⎪⎭⎫ ⎝⎛-+⎪⎭⎫ ⎝⎛-=221121211214131211n n n nn x n n 2211214131211=⎪⎭⎫ ⎝⎛--++⎪⎭⎫ ⎝⎛-+⎪⎭⎫ ⎝⎛-> ,故偶子列}{2n x 是单调递增的数列,又由于1211213121121)1(31211122<⎪⎭⎫ ⎝⎛----⎪⎭⎫ ⎝⎛--=-+-+-=+n n n x n n , 因而偶子列}{2n x 是单调上升且有上界的数列,由单调有界原理知}{2n x 必有极限存在,设a x n n =∞→2lim . 又由于121212++=+n x x n n 且0121lim =+∞→n n ,从而 a n x x n n n n n =++=∞→∞→+∞→121lim lim lim 212. 于是我们证得数列}{n x 的奇、偶子列均收敛而且极限相同,故数列}{n x 收敛.4.证明:极限)(lim 0x f x x →存在的充要条件是:对任意给定0>ε,存在0>δ,当δ<-'<00x x ,δ<-''<00x x 时,恒有ε<''-')()(x f x f .证明 )⇒必要性设A x f x x =→)(lim 0,则δδε<-<∀>∃>∀00,,0,0x x x ,就有2)(ε<-A x f ,因此由δ<-'<00x x ,δ<-''<00x x 知ε<-''+-'<-''--'=''-'A x f A x f A x f A x f x f x f )()())(())(()()(,因而必要性成立.)⇐充分性设}{n x 是任意满足0lim x x n n =∞→且0x x n ≠的数列,由已知0,0>∃>∀δε,只要δ<-'<00x x ,δ<-''<00x x 时,有ε<''-')()(x f x f .对上述0>δ,由于0lim x x n n =∞→,且0x x n ≠,故N n N >∀∃,时,有δ<-<||00x x n ;N m >∀时,有δ<-<||00x x m ,于是ε<-)()(m n x f x f ,即)}({n x f 是基本列,由实数列的Cauchy 收敛准则知)(lim n n x f ∞→存在.由}{n x 的取法知任意趋向于0x 而不等于0x 的实数列}{n x 都有极限)(lim n n x f ∞→存在.下证它们的极限都相等.反设)(lim ),(lim 0000x x x x x x x x n nn n n n ≠'='≠=∞→∞→,但)(lim )(lim n n n n x f x f '≠∞→∞→,则定义一个新的数列},,,,{}{2211 x x x x y n ''=, 由}{n y 的构造知)(lim 00x y x y n n n ≠=∞→,但)(lim n n y f ∞→有两个子序列极限不相等,故极限)(lim n n y f ∞→不存在,矛盾.从而任意趋向于0x 而不等于0x 的实数列}{n x 构成的数列)(n x f 都有极限存在.而且它们的极限都相等.由Heine 归结原则知)(lim 0x f x x →存在.5.证明)(x f 在0x 点连续的充要条件是:任给0>ε,存在0>ε,当δ<-'0x x ,δ<-''0x x 时,恒有ε<''-')()(x f x f .证明 )⇒必要性由)(x f 在0x 点连续知)()(lim 00x f x f x x =→,故δδε<-∀>∃>∀0,,0,0x x x ,就有2)()(0ε<-x f x f ,因此由δ<-'0x x ,δ<-''0x x 知))()(())()(()()(00x f x f x f x f x f x f -''--'=''-'ε<-''+-'≤)()()()(00x f x f x f x f .因而必要性成立. )⇐充分性设}{n x 是任意满足0lim x x n n =∞→的数列,由已知0,0>∃>∀δε,只要δ<-'0x x ,δ<-''0x x 时,就有ε<''-')()(x f x f .对上述0>δ,由于0lim x x n n =∞→,故N n N >∀∃,时,有δ<-||0x x n ,N m >∀时,有δ<-||0x x m ,于是ε<-)()(m n x f x f ,即)}({n x f 是基本列,由实数列的Cauchy 收敛准则知)(lim n n x f ∞→存在.由}{n x 的取法知任意趋向于0x 的实数列}{n x ,)(lim n n x f ∞→存在.下证它们的极限都相等.反设)(lim ),(lim 0000x x x x x x x x n nn n n n ≠'='≠=∞→∞→,但)(lim )(lim n n n n x f x f '≠∞→∞→,则定义一个新的数列},,,,{}{2211 x x x x y n ''=, 由}{n y 的构造知0lim x y n n =∞→,但)(lim n n y f ∞→有两个子序列极限不相等,故极限)(lim n n y f ∞→不存在,矛盾.从而,任意趋向于0x 的实数列}{n x 构成的数列)(n x f 都有极限存在,而且极限都相等,由Heine 归结原则知)(lim 0x f x x →存在.特别地,取}{n x 为恒为0x 的常数列,则可得)()(lim 0x f x f n n =∞→,即)()(lim 00x f x f x x =→,从而)(x f 在0x 点连续.6.证明下列极限不存在: (1)32cos11πn n n x n +-=; (2)nn n nx )1(21-+=;(3))sin(2n n x n +=π;(4)n x n cos =; (5)n x n tan =.解(1)取}{n x 的两个子序列,当k n 3=时,131336cos 13133+-=+-=k k k k k x k π,从而可以得到1lim 3=∞→k k x .而当13+=k n 时,233213)13(2cos 23313+⋅-=++=+k k k k k x k π,从而21lim 13-=+∞→k k x .}{n x 的两个子序列极限不等,故}{n x 的极限不存在. (2)对}{n x 的奇子列,由于121212211+++⎪⎭⎫⎝⎛+=k k k x ,而且12lim 12=+∞→k k ,故1lim 12=+∞→k k x ;对}{n x 的偶子列,由于k k k x 22221+=,而222212222→⋅≤+≤k k k ,故2lim 2=∞→k k x .原数列的奇子列与偶子列极限不同,故}{n x 的极限不存在.(3)由于()21lim2=-+∞→n n nn ,故取41=ε,则存在00,N n N >∀时 41212=<--+εn n n , 从而 4121412<--+<-n n n , 即 43412+<+<+n n n n ,从而 ()πππππ43412+<+<+n n n n .当n 为偶数时,由于ααπsin )sin(=+n ,从而由上式知()1sin 222≤+=≤n n x n π;当n 为奇数时,由于ααπsin )sin(-=+n ,从而()22sin 12-≤+=≤-n n x n π. 因此取220=ε,对N ∀,任取},max{0N N n >,则},max{10N N n >+,而且n x 和1+n x 一个在⎥⎦⎤⎢⎣⎡1,22内,另一个在⎥⎦⎤⎢⎣⎡--22,1内,从而0122ε=>-+n n x x ,由Cauchy 收敛原理的否定形式知数列}{n x 极限不存在.(4)取1sin 20=ε,对N ∀,由阿基米德公理知,存在+∈N k ,使得142+>+N k ππ,在⎪⎭⎫⎝⎛++432,42ππππk k 区间上,由于区间长度12>π,从而存在N n >,使得 ⎪⎭⎫ ⎝⎛++∈+432,421ππππk k n ,对于n 和2+n ,有1sin )1sin(222sin 22sin2cos )2cos(+=-+++=-+n nn n n n n 01sin 21sin 222ε==⋅≥, 由Cauchy 收敛原理的否定形式知数列}{cos }{n x n =极限不存在.(5)取0330>=ε,对N ∀,由阿基米德公理知,存在+∈N k ,使得N k >π,由于⎪⎭⎫⎝⎛++2,6ππππk k 的区间长度13>π,从而在⎪⎭⎫ ⎝⎛++2,6ππππk k 中有一个或两个大于N 的正整数点.若在⎪⎭⎫⎝⎛++2,6ππππk k 中只有一个正整数点n ,则 ⎪⎭⎫⎝⎛+-+=⎪⎭⎫ ⎝⎛+++∈+ππππππππ)1(,2)1(22,21k k k k n ,从而0336tantan )1tan(tan tan )1tan(επ==>>+-=-+n n n n n ; 若在⎪⎭⎫⎝⎛++2,6ππππk k 中有两个大于N 的正整数点,则取较大的正整数为n ,同样,⎪⎭⎫⎝⎛+-+∈+πππ)1(,2)1(1k k n ,从而0336tantan )1tan(tan tan )1tan(επ==>>+-=-+n n n n n . 由Cauchy 收敛原理的否定形式知数列}{tan }{n x n =极限不存在.7.设)(x f 在),(+∞a 上可导,|)(|x f '单调下降,且)(lim x f x +∞→存在,求证:0)(lim ='+∞→x f x x .证明 由于)(lim x f x +∞→存在,由Cauchy 收敛原理,0,0>∃>∀X ε,当X x>2时,也有X x >,从而22)(ε<⎪⎭⎫ ⎝⎛-x f x f .又因为)(x f 在),(+∞a 可导,故)(x f 在⎪⎭⎫⎝⎛x x ,2上满足Lagrange 中值定理条件,因而⎪⎭⎫⎝⎛∈∃x x ,2ξ,使得2)(2)(x f x f x f ξ'=⎪⎭⎫⎝⎛-,从而)(2)(2ξf x x f x f '=⎥⎦⎤⎢⎣⎡⎪⎭⎫ ⎝⎛-,又根据)(x f '单调下降得εεξξ=⋅<⎪⎭⎫⎝⎛-='='≤'='222)(2)()()()(x f x f f x f x x f x x f x ,因此0)(lim ='+∞→x f x x .8.设)(x f 在),(+∞-∞可导,且1)(<≤'k x f ,任给0x ,令),2,1,0()(1 ==+n x f x n n ,求证:(1) n n x +∞→lim 存在;(2) 上述极限为)(x f x =的根,且是唯一的.证明(1)0>∀ε,取k x x k N ln )1(ln1--=ε,N m n >∀,,不妨m n <,下证ε<-||n m x x .由已知)(x f 在),(+∞-∞可导,故由Lagrange 中值定理得1111))(()()(---+-≤-'=-=-n n n n n n n n x x k x x f x f x f x x ξ,同理 ,211----≤-n n n n x x k x x ,依此类推得011x x k x x nn n -≤-+,因此n n m m n n m m m n m x x x x x x x x x x x -++-≤-+-+-=-+-+--11111011101011)(x x k k k x x k x x k n n m n m -+++=-++-≤+--010111)(x x kk x x kk nn n--=-++<+ .由于k x x k N n ln )1(ln1--=>ε,而1<k ,从而01)1(lnln x x k k n --<ε,故ε<--=-011x x kk x x nn m ,因此由Cauchy 收敛原理知n n x +∞→lim 存在.(2)由于)(x f 在),(+∞-∞可导,因而连续,在)(1n n x f x =+两边同时对∞→n 取极限,则)lim (lim n n n n x f x +∞→+∞→=,即n n x +∞→lim 是)(x f x =的根,下证唯一性.反设有)(,b a b a ≠,且)(a f a =,)(b f b =,则b a b a k b a f b f a f b a -<-≤-⋅'=-=-)()()(ξ,矛盾,故根是唯一的.9.设)(x f 在],[b a 满足条件:(1)10],,[,,)()(<<∈∀-≤-k b a y x y x k y f x f ; (2))(x f 的值域包含在],[b a 内.则对任意],[0b a x ∈,令),2,1,0()(1 ==+n x f x n n ,有(1)n n x +∞→lim 存在;(2)方程)(x f x =的解在],[b a 上是唯一的,这个解就是上述极限值. 证明(1)0>∀ε,取k x x k N ln ||)1(ln01--=ε,N m n >∀,,不妨m n <,下证ε<-n m x x .由已知)(1n n x f x =+,而],[0b a x ∈且)(x f 的值域包含在],[b a 内,因而对n ∀,都有],[b a x n ∈,从而01111)()(x x k x x k x f x f x x n n n n n n n -≤-≤-=---+,因此n n m m n n m m m n m x x x x x x x x x x x -++-≤-+-+-=-+-+--11111011101011)(x x k k k x x k x x k n n m n m -+++=-++-≤+--ε<--=-++<+010111)(x x kk x x kk nn n.因此由Cauchy 收敛原理知n n x +∞→lim 存在.(2)设方程)(x f x =在],[b a 上有两个不同的解d c ,,则d c d c k d f c f d c -<-<-=-)()(,矛盾,故根是唯一的.§4 再论闭区间上连续函数的性质1.设)(x f 在],[b a 上连续,并且最大值点0x 是唯一的,又设],[b a x n ∈,使)()(lim 0x f x f n n =+∞→,求证0lim x x n n =+∞→.证明 不妨设),(0b a x ∈,当a x =0或b x =0时同理可证.对任意},min{000x b a x --<<ε,由于)(x f 在],[b a 上连续,故)(x f 在],[0ε-x a 、],[00εε+-x x 、],[0b x ε+上连续,由闭区间连续函数的最值定理,)(x f 在],[0ε-x a 、],[00εε+-x x 、],[0b x ε+上均有最大值,显然)(x f 在],[00εε+-x x 上的最大值为)(0x f ,设)(x f 在],[0ε-x a 和],[0b x ε+上的最大值为M ,由最大值点的唯一性可知M x f >)(0.取02)(0>-Mx f ,由)()(lim 0x f x f n n =+∞→知N n N >∀∃,时,2)()()(00Mx f x f x f n -<-,即 M Mx f M x f x f x f n >+=-->2)(2)()()(000,而)(x f 在],[0ε-x a 和],[0b x ε+上的最大值为M ,故),(00εε+-∈x x x n ,即ε<-||0x x n ,从而0lim x x n n =+∞→.2.设)(x f 在],[b a 上连续,可微;又设 (1) )(max )(min x f p x f bx a bx a ≤≤≤≤<<;(2) 如果p x f =)(,则有0)(≠'x f , 求证:p x f =)(的根只有有限多个.证明 利用区间套定理.反设p x f =)(在],[b a 上有无穷多个根,设],[],[11b a b a =,二等分区间],[11b a ,则在两个子区间中必有一个区间含有p x f =)(的无穷多个根,设此区间为],[22b a ,再二等分区间],[22b a ,则在两个子区间中必有一个区间含有p x f =)(的无穷多个根,设此区间为 ],,[33b a .依此类推得一区间套]},{[n n b a ,由区间套的构造知p x f =)(在任意],[n n b a 有无穷多个根.由区间套定理知],[b a r ∈∃,使得对于任意],[,n n b a r N n ∈∈+.若p r f ≠)(,则令p x f x g -=)()(,)(x g 也在],[b a 连续,且0)()(≠-=p r f r g ,从而由保号性知),(,δδδ+-∈∀∃r r x 时,都有0)(≠x g ,即p x f ≠)(,而由区间套知N n N >∀∃,时),(],[δδ+-⊂r r b a n n ,即p x f =)(在],[n n b a 无根,这与区间套的构造矛盾.若p r f =)(,则0)(≠'r f ,即0)()(l i m ≠--→rx r f x f rx ,从而x ∀'∃,δ,当δ'<-<||0r x 时,有0)()(≠--rx r f x f ,即p x f ≠)(,从而在),(δδ'+'-r r 上)(x f 只有一个根r ,而由区间套知N n N >∀∃,时),(],[δδ+-⊂r r b a n n ,即p x f =)(在],[n n b a 只有一个根,这与区间套的构造矛盾.因此p x f =)(在],[b a 上只有有限多个根.3.设)(x f 在],[b a 上连续,0)(,0)(><b f a f ,求证:存在),(b a ∈ξ,使0)(=ξf 且)(0)(b x x f ≤<>ξ.证明 令],[|{b a x x E ∈=且}0)(=x f ,由于0)(,0)(><b f a f ,且)(x f 在],[b a 上连续,由介值性定理知φ≠E ,从而E 为非空有界数集,由确界原理知E 有上确界,设E sup =ξ,下证0)(=ξf .事实上,由于E sup =ξ,由本章第一节习题3知可以在E 中选取数列}{n x ,使ξ=∞→n n x lim ,又由)(x f 连续知0)(lim )lim ()(===∞→∞→n n n n x f x f f ξ,又对于],(b x ξ∈∀,由于E x ∉,从而0)(≠x f ,又根据0)(>b f 知0)(>x f ,因而结论成立.4.设)(x f 是],[b a 上的连续函数,其最大值和最小值分别为M 和)(M m m <,求证:必存在区间],[βα,满足条件:(1) m f M f ==)(,)(βα或M f m f ==)(,)(βα; (2) M x f m <<)(,当),(βα∈x .证明 由于)(x f 是],[b a 上的连续函数,且有最大值M 和最小值m ,故由最值定理知],[b a c ∈∃,使得M c f =)(;],[b a d ∈∃,使得m d f =)(,由于M m <,故d c ≠,令},min{d c =α,},max{d c =β,则在区间],[βα上满足:(1)m f M f ==)(,)(βα或M f m f ==)(,)(βα;(2)对),(βα∈∀x ,由于m f M f ==)(,)(βα或M f m f ==)(,)(βα,而m M ,分别为],[b a 上的最大值和最小值,故M x f m <<)(.5.设)(x f 在]2,0[a 上连续,且)2()0(a f f =,求证:存在],0[a x ∈,使)()(a x f x f +=.证明 考虑辅助函数)()()(a x f x f x g +-=,],0[a x ∈.若)()0(a f f =,根据已知条件)2()0(a f f =可知,取0=x 或a x =时,均有)()(a x f x f +=,命题已证.若)()0(a f f ≠,则)()0()0(a f f g -=,)0()()2()()(f a f a f a f a g -=-=,从而)0(g 与)(a g 符号相反,由零点定理知],0[a x ∈∃,使0)(=x g ,即)()(a x f x f +=.6.设)(x f 在],[b a 上连续,且取值为整数,求证≡)(x f 常数.证明 反设)(x f 不恒为常数,则],[,21b a x x ∈∃,使得)()(21x f x f ≠,又由于)(x f 取值为整数,故)(),(21x f x f 均为整数,在)(),(21x f x f 之间任取一非整数c ,则由介值性定理知],[b a ∈∃ξ,使得c f =)(ξ,这与)(x f 取值为整数矛盾.7.设)(x f 在),(b a 一致连续,±∞≠b a ,,证明:)(x f 在],[b a 上有界.证明 由于)(x f 在],[b a 上一致连续,故取01>=ε,则0>∃δ,当δ<-21x x 时,有1)()(21<-x f x f . 取定11,b a ,其中δ+<<a a a 1,b b b <<-1δ,则],(1a a x ∈∀, 有δ<-1a x ,故1)()(1<-a f x f ,因而1)()(1+<a f x f ;同理),[1b b x ∈∀,有δ<-1b x , 故1)()(1<-b f x f ,因而1)()(1+<b f x f ,因此)(x f 在区间],(1a a 和区间),[1b b 均有界. 另一方面,由于)(x f 在],[11b a 上一致连续,根据闭区间上连续函数的性质可知存在01>M ,使得111)(],,[M x f b a x <∈∀.取0}1)(,1)(,max{111>++=b f a f M M ,则),(b a x ∈∀,均有M x f <)(,因而)(x f 在),(b a 上有界.8. 若函数)(x f 在),(b a 上满足利普希茨(Lipschitz )条件,即存在常数K ,使得x x K x f x f ''-'≤''-')()(,),(,b a x x ∈'''.证明:)(x f 在),(b a 上一致连续.证明 ,0>∀ε 取,21εδK=则对δ<''-'∈'''∀x x b a x x ),,(,,由Lipschitz 条件知εε<⋅<''-'≤''-'KK x x K x f x f 21)()(,因而依定义知)(x f 在),(b a 上一致连续.9.试用一致连续的定义证明:若函数)(x f 在],[c a 和],[b c 上都一致连续,则)(x f 在],[b a 上也一致连续.证明 对0>∀ε,由函数)(x f 在],[c a 一致连续知01>∃δ,对],[,21c a x x ∈∀而且121δ<-x x ,就有2)()(21ε<-x f x f ;又根据函数)(x f 在],[b c 上一致连续知02>∃δ,],[,21b c x x ∈∀且221δ<-x x 时,就有2)()(21ε<-x f x f .取},min{21δδδ=,则],[,21b a x x ∈∀且δ<-21x x 时,若21,x x 同属于],[c a ,有εε<<-2)()(21x f x f ;若21,x x 同属于],[b c ,也有εε<<-2)()(21x f x f ;若21,x x 一个属于],[c a ,另一个属于],[b c ,则由δ<-21x x 知δδ<-<-c x c x 21,,从而εεε=+<-+-≤-22)()()()()()(2121x f c f c f x f x f x f .因而],[,21b a x x ∈∀且δ<-21x x 时,ε<-)()(21x f x f . 因此由一致连续的定义可知)(x f 在],[b a 上一致连续.10.设函数)(x f 在),(+∞-∞上连续,且极限)(lim x f x -∞→与)(lim x f x +∞→存在. 证明:)(x f 在),(+∞-∞上一致连续.证明 对0>∀ε,由于)(lim x f x -∞→存在,根据Cauchy 收敛原理知,存在01>X ,任意121,X x x -<时,就有ε<-)()(21x f x f ;又由于)(lim x f x +∞→存在,故存在02>X ,任意221,X x x >,就有ε<-)()(21x f x f .由于)(x f 在),(+∞-∞上连续,故)(x f 在区间]1,1[21+--X X 上连续,因而在]1,1[21+--X X 上一致连续,由一致连续的定义知,对上述0>ε,存在01>δ,任意]1),1([,2121++-∈X X x x ,只要112δ<-x x ,就有ε<-)()(21x f x f .取0}1,min{1>=δδ,则),(,21+∞-∞∈∀x x ,只要δ<-21x x ,则21,x x 同属于区间),(1X --∞、]1),1([21++-X X 或),(2+∞X ,由上述讨论知,不管在哪种情况下,都有ε<-)()(21x f x f ,因而)(x f 在),(+∞-∞上一致连续.11.若)(x f 在区间X (有穷或无穷)中具有有界的导数,即M x f ≤')(,X x ∈,则)(x f 在X 中一致连续.证明 对0>∀ε,取Mεδ=,则对任意X x x ∈21,,只要δ<-||21x x ,根据Lagrange中值定理,存在ξ在21,x x 之间,且εδξ=<-≤-'=-M x x M x x f x f x f 212121|))((|)()(,从而)(x f 在X 中一致连续.12.求证:x x x f ln )(=在),0(+∞上一致连续.证明 由于x x x f ln )(=,故xx x xxx f 2ln 2ln 211)(+=+=',xx x x f 4ln )(-='',令0)(=''x f 得1=x ,故1=x 是)(x f '的稳定点,当0)(),1,0(>''∈x f x ,从而)(x f '单调递增;而当0)(),,1(<''+∞∈x f x ,故)(x f '单调递减,因此1=x 是)(x f '的极大值点,也是最大值点,而1)1(='f ,从而对),0(+∞∈∀x ,1)(≤'x f .再令0)(='x f 得2-=e x ,在区间),[2+∞-e 上,由于0)(≥'x f ,因而在),[2+∞-e 上1)(0≤'≤x f ,即1)(≤'x f ,由上题结论知)(x f 在),[2+∞-e 上一致连续.此外,由于0ln lim )(lim 00==++→→x x x f x x ,若令 ⎩⎨⎧=>=.00,0ln )(x x xx x g则)(x g 在]2,0[连续,因而一致连续,从而)(x g 在]2,0(上一致连续,即)(x f 在]2,0(一致连续.对0>∀ε,由)(x f 在),[2+∞-e 上一致连续知,01>∃δ,对任意),[,221+∞∈-e x x 且121δ<-x x ,都有ε<-)()(21x f x f ;又由)(x f 在]2,0(上一致连续知,02>∃δ,对任意]2,0(,21∈x x 且221δ<-x x ,也有ε<-)()(21x f x f .取0}1,,min{21>=δδδ,则当),0(,21+∞∈x x 且δ<-21x x 时,要么],2,0(,21∈x x 要么),[,221+∞∈-e x x ,从而ε<-)()(21x f x f .因此x x x f ln )(=在),0(+∞上一致连续.13.设)(x f 在),(+∞a 上可导,且+∞='+∞→)(lim x f x ,求证:)(x f 在),(+∞a 上不一致连续.证明 取10=ε,对0>∀δ,由于+∞='+∞→)(lim x f x ,故0>∃X ,当X x >时,有δ2)(>'x f ,任取X x >1,X x x >+=212δ,虽然有δδ<=-221x x ,但根据lagrange中值定理知,存在)2,(11δξ+∈x x ,使得02121122)()()(εδδξ==⋅>-⋅'=-x x f x f x f . 根据一致连续的否定定义知)(x f 在),(+∞a 上不一致连续.14.求证:x x x f ln )(=在),0(+∞上不一致连续.证明 由于+∞=+='+∞→+∞→)1(ln lim )(lim x x f x x ,由上题结论知结论成立.§5 可积性1. 判断下列函数在区间]1,0[上的可积性: (1))(x f 在]1,0[上有界,不连续点为),2,1(1==n nx ; (2)⎪⎩⎪⎨⎧=∈⎪⎭⎫⎝⎛=;0,0],1,0(,sin sgn )(x x x x f π (3)⎪⎩⎪⎨⎧=∈⎥⎦⎤⎢⎣⎡-=;0,0],1,0(,11)(x x x x x f(4)[]⎪⎩⎪⎨⎧=∈=.0,0],1,0(,1)(1x x x f x解(1)由于)(x f 在]1,0[上有界,故存在0>M ,对]1,0[∈∀x ,都有M x f ≤)(,故在区间]1,0[的任何子区间上,)(x f 的振幅M 2≤ω.对任给0>ε,由于04lim=∞→n M n ,故N n N >∀∃,时,都有24ε<n M ,特别地取10+=N n 时,也有240ε<n M . 由于)(x f 在⎥⎦⎤⎢⎣⎡1,10n 上只有有限个间断点,因而是可积的,即01>∃δ,使得对区间⎥⎦⎤⎢⎣⎡1,10n 的任何1)max(δλ<∆='i x 的分法,都有∑<∆'''2i i i x εω.取⎭⎬⎫⎩⎨⎧=011,min n δδ,对]1,0[的任意δλ<∆=)max(i x 的分法,下证εω<∆∑=n i i i x 1.由于)1,0(10∈n ,故对上述任意分法,都存在分点00,1i i x x -,使得00011i i x n x <≤-,因而∑∑∑∑∑+=-=+==-=∆++∆≤∆+∆+∆=∆ni i iii i i ni i iii i n i i i iiiixM x M xx xx o 11111110000022ωδωωωωεεεε=+<++≤222121200n M n M, 这里最后一项210εω<∆∑+=ni i i i x 是由于[]⎥⎦⎤⎢⎣⎡⊂+1,11,010n x i ,而)(x f 在⎥⎦⎤⎢⎣⎡1,10n 可积,故函数在区间[]1,10+i x 可积,因而210εω<∆∑+=n i i iix .因此0lim 1=∆∑=→ni iix ωλ,即)(x f 在]1,0[上可积.(2)由于)(x f 在]1,0[上有界,且不连续点为),2,1(1==n nx 和0=x ,根据(1)的证法知)(x f 在]1,0[上可积.(3)由于)(x f 在]1,0[上有1)(≤x f ,故)(x f 有界,而且)(x f 的不连续点为0=x 和),2,1(1==n nx ,由(2)的证法知,)(x f 在]1,0[可积. (4)由于)(x f 在]1,0[上有1)(0≤≤x f ,故)(x f 有界,而且)(x f 的不连续点只有。
c语言第九章题库及详解答案
c语言第九章题库及详解答案C语言第九章题库及详解答案一、选择题1. 在C语言中,以下哪个关键字用于定义数组?A. arrayB. listC. setD. define2. 以下哪个选项是正确的C语言数组声明?A. int myArray[];B. int myArray[10] = {};C. int myArray = 10;D. int myArray(10);3. 数组元素的默认初始化值是什么?A. 0B. 1C. -1D. 随机值4. 在C语言中,数组的索引是从哪个数字开始的?A. 0B. 1C. -1D. 105. 以下哪个函数可以用于计算数组中元素的个数?A. count()B. size()C. length()D. sizeof()二、填空题6. 在C语言中,声明一个具有10个整数元素的数组的语句是:________。
答案:int myArray[10];7. 如果数组的索引从0开始,那么数组myArray[10]的最后一个元素的索引是:________。
答案:98. 要初始化一个数组的所有元素为0,可以使用:________。
答案:int myArray[10] = {0};9. 在C语言中,可以使用________运算符来访问数组的元素。
答案:[]10. 当数组作为参数传递给函数时,实际上传递的是数组的________。
答案:首地址三、简答题11. 解释C语言中数组的内存分配方式。
答案:在C语言中,数组是连续存储在内存中的。
数组的内存分配是静态的,即在编译时分配。
数组的元素按照声明的顺序在内存中连续排列。
12. 说明数组和指针在C语言中的关系。
答案:在C语言中,数组名可以作为指针使用。
数组名代表数组的首地址。
当数组作为参数传递给函数时,数组名退化为指向数组第一个元素的指针。
四、编程题13. 编写一个C语言程序,实现对一个整数数组的排序。
答案:```c#include <stdio.h>void sortArray(int arr[], int size) {int i, j, temp;for (i = 0; i < size - 1; i++) {for (j = i + 1; j < size; j++) {if (arr[i] > arr[j]) {temp = arr[i];arr[i] = arr[j];arr[j] = temp;}}}}int main() {int myArray[] = {5, 3, 8, 2, 1};int size = sizeof(myArray) / sizeof(myArray[0]);sortArray(myArray, size);printf("Sorted array: ");for (int i = 0; i < size; i++) {printf("%d ", myArray[i]);}return 0;}```14. 编写一个C语言程序,实现查找数组中的最大值和最小值。
第9章 习题参考答案
第九章静态时间序列模型课后习题参考答案1.遍历性、平稳性对时间序列回归有何意义?答:静态时间序列模型研究的是不同随机变量的时间序列之间体现出的静态(同期)结构关系,也称为结构型时间序列模型。
由第七章“时间序列回归的基本问题”可知,对于时间序列回归,如果假定TS.1-假定TS.6均成立,OLSE具有无偏性、有效性和正态性,不必考虑时间序列是否具有遍历性与平稳性问题。
然而,如果这些假定不完全满足,例如解释变量x仅为同期外生,为了保证OLSE具有良好的大样本性质(一致性),我们要求时间序列产生自遍历、平稳过程,即假定TS.4’。
常用统计推断方法的适用性对该假定是否成立非常敏感,当高度持久时间序列或非平稳序列用于回归时,我们无法借助于大数定律和中心极限定理进行统计推断,所以遍历性、平稳性对时间序列回归至关重要。
大多数情况下,时间序列建模之前,都须对时间序列的遍历、平稳性质进行研判,否则很可能造成回归方法的误用,产生伪回归问题,进而得出误导性的结论。
所以,应该重点关注非平稳遍历时间序列条件下建模特殊性问题。
本章讨论的静态时间序列建模过程中,就可能存在解释变量只是同期外生,这时时间序列的特殊性将x y都是产生自平稳、遍历过程,在大样本下OLSE仍然是一致的、给回归分析带来一些问题。
但如果,jt t渐进有效和渐进正态的,因此也可以按照经典回归分析的方法进行参数估计和统计推断。
对于非平稳、遍历时间序列,进行OLS回归之前需要通过去势(消除确定性趋势)和差分(消除随机趋势)等方法进行平稳化(遍历化)处理。
2.DF、ADF和PP检验分布适用于什么情况下的单位根检验?如何确定检验模型?答:由于真实DGP是未知的,我们可以通过一个时间序列(相当于一个样本)的特征,对DGP是否存在单位根进行推测,这个方法称为单位根检验(Unit Root)。
本章介绍三种常用的方法。
(1)Dickey-Fuller 检验(DF检验)Dickey和Fuller通过数值模拟,计算了对应不同DGP和序列长度T的DF分布百分位数,并编制了DF临界值表。
《劳动经济学》(作者Borjas)第九章习题答案
CHAPTER 99-1. Suppose a worker with an annual discount rate of 10 percent currently resides in Pennsylvania and is deciding whether to remain there or to move to Illinois. There are three work periods left in the life cycle. If the worker remains in Pennsylvania, he will earn $20,000 per year in each of the three periods. If the worker moves to Illinois, he will earn $22,000 in each of the three periods. What is the highest cost of migration that a worker is willing to incur and still make the move?The worker must compare the present value of staying in Pennsylvania to the present value of moving to Illinois. A worker will move if the present value of earnings in Illinois minus the costs of moving there exceed the present value of earnings in Pennsylvania:74.710,54$)1.1(000,201.1000,20000,202=++=PA PV and82.181,60$)1.1(000,221.1000,22000,222=++=IL PVThe worker will move, therefore, ifPV IL – C > PV PA ,where C denotes migration costs. Thus, the worker moves ifC < 60,181.82 - 54,710.74 = $5,471.089-2. Nick and Jane are married. They currently reside in Minnesota. Nick’s present value oflifetime earnings in his current employment is $300,000, and Jane’s present value is $200,000. They are contemplating moving to Texas, where each of them would earn a lifetime income of $260,000. The couple’s cost of moving is $10,000. In addition, Nick very much prefers the climate in Texas to that in Minnesota, and he figures that the change in climate is worth an additional $2,000 to him. Jane, on the other hand, prefers Minnesota’s frigid winters, so she figures she would be $2,000 worse off because of Texas’s blistering summers. Should they move to Texas?Yes. The “climatic” aspects of the move exactly balance each other, so we should not take them into account. On the monetary side, the sum of Nick’s and Jane’s lifetime present value of earnings inMinnesota is $500,000. The corresponding amount in Texas will be $520,000. The difference between the two ($20,000) exceeds the cost of moving ($10,000), so the move will make the couple jointly better off.9-3. Mickey and Minnie live in Orlando. Mickey’s net present value of lifetime earnings in Orlando is $125,000. Minnie’s net present value of lifetime earnings in Orlando is $500,000. The cost of moving to Atlanta is $25,000 per person. In Atlanta, Mickey’s net present value of lifetime earnings would be $155,000, and Minnie’s net present value of lifetime earnings would be $510,000. If Mickey and Minnie choose where to live based on their joint well-being, will they move to Atlanta? Is Mickey a tied-mover or a tied-stayer or neither? Is Minnie a tied-mover or a tied-stayer or neither?As a couple, the net present value of lifetime earnings of staying in Orlando is $500,000 + $125,000 = $625,000 and of moving to Atlanta is $510,000 + $155,000 – $50,000 = $615,000. Thus, as a couple, they would choose to stay in Orlando. Thus, there can only be a tied-stayer. (There cannot be a tied-mover, because the couple is not moving.)For Mickey, staying in Orlando is associated with a net present value of $125,000, while moving to Atlanta would yield a net present value of $155,000 – $25,000 = $130,000. So Mickey would choose to move to Atlanta. Therefore, Mickey is a tied-stayer.For Minnie, staying in Orlando is associated with a net present value of $500,000, while moving to Atlanta would yield a net present value of $510,000 –$25,000 = $485,000. So Minnie would choose to remain in Orlando. Thus, Minnie is not a tied-stayer.9-4. Suppose a worker’s skill is captured by his efficiency units of labor. The distribution of efficiency units in the population is such that worker 1 has 1 efficiency unit, worker 2 has 2 efficiency units, and so on. There are 100 workers in the population. In deciding whether to migrate to the United States, these workers compare their weekly earnings at home (w0) with their potential earnings in the United States (w1). The wage-skills relationship in each of the two countries is given by:w0 = 700 + 0.5s,andw1 = 670 + s,where s is the number of efficiency units the worker possesses.(a) Assume there are no migration costs. What is the average number of efficiency units among immigrants? Is the immigrant flow positively or negatively selected?The earnings-skills relationship in each country is illustrated in the figure below. The US line is steeper because the payoff to a unit of skills is higher in the United States. All workers who have at least 60 efficiency units will migrate to the United States. Therefore, there is positive selection and the average number of efficiency units in the immigrant flow is approximately 80 (the exact answer depends on whether the person with 60 efficiency units, who is indifferent between moving or not, moves to the United States).(b) Suppose it costs $10 to migrate to the United States. What is the average number of efficiency units among immigrants? Is the immigrant flow positively or negatively selected?If everyone incurs a cost of $10 to migrate to the United States, the U.S. wage-skill line drops by $10, and only those persons with more than 80 efficiency units will find it worthwhile to migrate. The immigrant flow is still positively selected and has, on average, 90 efficiency units.(c) What would happen to the selection that takes place if migration costs are not constant in the population, but are much higher for more skilled workers?If migration costs are much higher for skilled workers, it is possible that no skilled workers will find it worthwhile to migrate. We already know that even in the absence of migration costs no worker with fewer than 60 efficiency units finds it worthwhile to migrate. If highly skilled workers find it very costly to migrate it might be the case that there is no migration to the United States.Income700660809-5. Suppose the United States enacts legislation granting all workers, including newly arrived immigrants, a minimum income floor of y− dollars.(a) Generalize the Roy model to show how this type of welfare program influences incentive tomigrate to the United States. Ignore any issues regarding how the welfare program is to be funded.(b) Does this welfare program change the selection of the immigrant flow? In particular, are immigrants more likely to be negatively selected than in the absence of a welfare program?(c) Which types of workers, the highly skilled or the less skilled, are most likely to be attracted by the welfare program?U.S. Labor Market U.S. Labor MarketThe introduction of a wage floor in the United States (at y −) shifts the U.S. earnings-skill relationship to the bold line drawn in the figures. If the returns to skills are higher in the United States (left panel above), there are then two sets of workers who find it profitable to move: those who have very high skill levels (above s P ) as well as those workers who have very low skill levels (below s L ). In contrast, if the returns to skills are lower in the United States than in the country of origin (the right panel above), the introduction of the welfare program does not change the incentives to migrate for any worker (although the incentives of some workers would change if the wage floor was high enough). The welfare program, therefore, acts as a welfare magnet for workers originating in countries that generate “brain drains”, but not in countries where unskilled workers have incentives to migrate even in the absence of wage floors.α αL P Dollars αN y −α9-6. The immigration surplus, though seemingly small in the United States, redistributes wealth from workers to firms. Present a back-of-the-envelope calculation of the losses accruing to native workers and of the gains accruing to firms. Do these calculations help explain why some segments of society are emotional in their support of changes in immigration policy that would either increase or decrease the immigrant flow?The total loss in earnings experienced by workers in the United States is given by the rectangle w 0 B F w 1 in Figure 9-11. The area of this rectangle is given by:Loss to Native Workers = (w 1 - w 0) × N .We can calculate the loss to native workers as a fraction of GDP by dividing both sides by Q (national income). If we do this and rearrange terms we obtain:MN N Q M N w w w w Q +×+×−=)( Workers Native to Loss 0001.Thus, the native loss (as a fraction of GDP) equals the percentage change in the native wage caused by immigration times labor’s share of national income times the fraction of the labor force that is native born. If we continue the numerical example in the text, this calculation yields: (-.03) × (.7) × (.9) = -1.89percent of GDP. As national income is on the order of $11 trillion, the loss suffered by native workers is on the order of $208 billion. Capitalists receive this income plus the immigration surplus of $11 billion (see the text), for a total gain of about $219 billion (about 2 percent of GDP).Even though the net benefits from immigration are small, particular groups in the United States either gain or lose substantially from immigration. This explains why the debate over immigration policy is often polarized.9-7. In the absence of any legal barriers on immigration from Neolandia to the United States, the economic conditions in the two countries generate an immigrant flow that is negatively selected. In response, the United States enacts an immigration policy that restricts entry to Neolandians who are in the top 10 percent of Neolandia’s skill distribution. What type of Neolandian would now migrate to the United States?No one would migrate from Neolandia. The policy does not change the cost-benefit analysis for the most skilled Neolandians. They did not want to migrate when they could enter the country freely, and they still will not want to migrate when they are the only ones who can obtain visas. The lesson is that changes in immigration policy affect the skill composition of the immigrant flow only if changes target immigrants who wished to migrate to the United States in the first place.9-8. Labor demand for low-skilled workers in the United States is w = 24 – 0.1E where E is the number of workers (in millions) and w is the hourly wage. There are 120 million domestic U.S. low-skilled workers who supply labor inelastically. If the U.S. opened its borders to immigration, 20 million low-skill immigrants would enter the U.S. and supply labor inelastically. What is the market-clearing wage if immigration is not allowed? What is the market-clearing wage with open borders? How much is the immigration surplus when the U.S. opens its borders? How much surplus is transferred from domestic workers to domestic firms?Without immigration, the market-clearing wage is $12, at which all 120 million low-skill U.S. workers are employed. With immigration, the market-clearing wage is $10, at which all 120 million low-skill U.S. workers and all 20 million immigrants are employed. The additional surplus received by the U.S. because of the immigration equals ($12 – $10) (140m – 120m) / 2 = $20 million. The total transfer from U.S. workers to U.S. firms because of the immigration equals ($12 – $10) (120m) = $240 million.9-9. A country has two regions, the North and the South, which are identical in all respects except the hourly wage and the number of workers. The demand for labor in each region is:w N = $20 – .5E N and w S = $20 – .5E S,where E N and E S are millions of workers. Currently there are 6 million workers in the North and 18 million workers in the South.(a) What is the wage in each region?The wage in the North is $20 – .5 (6) = $17. The wage in the South is $20 – .5 (18) = $11.(b) If there were no shocks to the economy, migration over time will result in an equalization of wages and employment. What would be the long-run wage and employment level in each region?As labor demand is the same in both regions and workers are identical in their preferences, half of the workers will locate in each region in the long-run. Thus, 12 million workers will work in each region, and the hourly wage will be $14.(c) Return to the original set-up where there are 6 million workers in the North and 18 million workers in the South. As a policy maker, you decide not only to allow 2 million immigrants of working age to enter your country, but you have the authority to resettle the immigrants wherever you want. How should you distribute immigrants across the regions to maximize the country’s immigration surplus? Besides maximizing the immigration surplus in the short-run, in what other ways does your distribution of immigrants help the economy?Let I N and I S be the number of immigrants (in millions) placed in the North and in the South respectively, so that I N + I S = 2. After immigration, the new wages are:w N = $17 – .5I N and w S = $11 – .5I Sand the immigrant surpluses are:S N = 0.25(I N)2 and S S = .25(I S)2.Using that I N + I S = 2, therefore, the total immigrant surplus isS = 0.25(I N)2 + 0.25(2–I N)2 = 1 – I N + .5(I N)2.One can use calculus to solve for the optimal value for I N, but be aware that S is U-shaped, so setting the first order conditions to 0 solves for a minimum. Rather, use Excel to plot S. The data are:I N S I N S I N S I N S0.001.000.05 0.95 0.55 0.60 1.05 0.50 1.55 0.650.10 0.91 0.60 0.58 1.10 0.51 1.60 0.680.15 0.86 0.65 0.56 1.15 0.51 1.65 0.710.20 0.82 0.70 0.55 1.20 0.52 1.70 0.750.25 0.78 0.75 0.53 1.25 0.53 1.75 0.780.30 0.75 0.80 0.52 1.30 0.55 1.80 0.820.35 0.71 0.85 0.51 1.35 0.56 1.85 0.860.40 0.68 0.90 0.51 1.40 0.58 1.90 0.910.45 0.65 0.95 0.50 1.45 0.60 1.95 0.950.50 0.63 1.00 0.50 1.50 0.63 2.00 1.00 Thus, the immigrant surplus is maximized by placing all 2 million immigrants in either of the regions. It would be best, however, to place them all in the high wage region, as this will lead to a faster equalization of wages and saves natives the trouble and costs of moving.9-10. Phil has two periods of work remaining prior to retirement. He is currently employed in a firm that pays him the value of his marginal product, $50,000 per period. There are many other firms that Phil could potentially work for. There is a 50 percent chance of Phil being a good match for any particular firm, and a 50 percent chance of him being a bad match. If he is in a good match, the value of his marginal product is $56,000 per period. If he is in a bad match, the value of his marginal product is $40,000 per period. If Phil quits his job, he can immediately find employment with any of the alternative firms. It takes one period to discover whether Phil is a good or a bad match with a particular firm. In that first period, while Phil’s value to the firm is uncertain, he is offered a wage of $48,000. After the value of the match is determined, Phil is offered a wage equal to the value of his marginal product in that firm. When offered that wage, Phil is free to (a) accept;(b) reject and try some other firm; or (c) return to his original firm and his original wage. Phil maximizes the present value of his expected lifetime earnings, and his discount rate is 10 percent. What should Phil do?Phil makes decisions at the beginning of each period, and there are a variety of choices at each of these times. To reduce the number of strategies that require the numerical calculation of the expected outcome, first discard unreasonable choices. In particular, if Phil does not quit his job in period 1, he should not do so in period 2. After all, his second-period wage in a new job will be lower than in the old job, and there is no third period. Similarly, if he tries a new job in period 1 and is found to be a bad match, he should return to the old job. After all, the old job pays a higher wage than what Phil’s current employer is willing to pay and what another new firm would offer him. Finally, if he tries a new job and is found to be a good match, he should certainly accept their offer. In the end, Phil only has two potentially viable strategies.Strategy one: Keep the old job in both periods. The earnings path associated with this choice is flat and deterministic – Phil earns $50,000 in each period. The present discounted value of the outcome of this strategy is PV1 = 50,000 + 50,000/1.1 = $95,455.Strategy two: Try a new job. If it is a good match, keep it. If it is a bad match, return to the old job. If Phil adopts this strategy, he will earn $48,000 in period 1. In period 2, he will earn either $56,000 or $50,000, each with probability ½. The expected present discounted value of the outcome of that strategy is PV2 = 48,000 + ((½× 56,000) + (½ × 50,000))/1.1 = $96,182.As the second strategy generates a higher present value, this is the strategy Phil adopts.9-11. Under the recently enacted 2001 tax legislation in the United States, all income tax filers can now deduct from their total income half of their expenses incurred when moving more than 50 miles to accept a new job. Prior to the change, only tax filers who itemized their deductions were allowed to deduct their moving expenses. (Typically, homeowners itemize their deductions and renters do not itemize.) How would this change in the tax bill likely affect the mobility of homeowners and renters?The policy change has no affect on homeowners, whereas the policy change reduces the cost of moving for renters. Therefore, the policy is predicted to increase the mobility of renters.。
数据结构第三版第九章课后习题参考答案
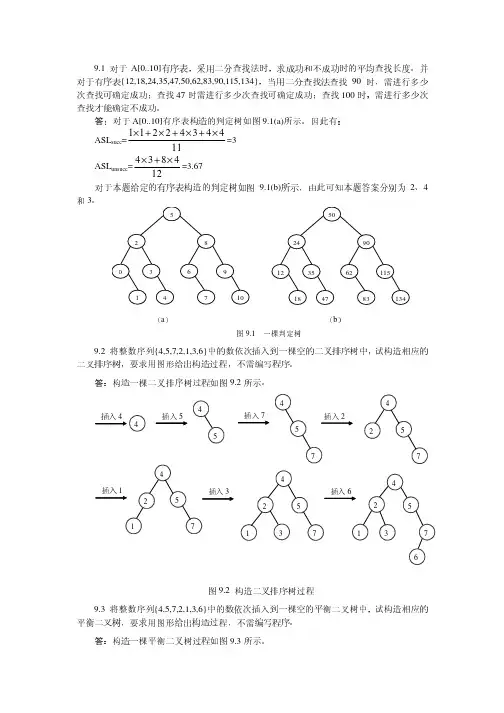
}
}
设计如下主函数:
void main()
{ BSTNode *bt;
KeyType k=3;
int a[]={5,2,1,6,7,4,8,3,9},n=9;
bt=CreatBST(a,n);
//创建《教程》中图 9.4(a)所示的二叉排序树
printf("BST:");DispBST(bt);printf("\n");
#define M 26 int H(char *s)
//求字符串 s 的哈希函数值
{
return(*s%M);
}
构造哈希表 void Hash(char *s[]) //
{ int i,j;
char HT[M][10]; for (i=0;i<M;i++)
//哈希表置初值
HT[i][0]='\0'; for (i=0;i<N;i++) { j=H(s[i]);
//求每个关键字的位置 求 // s[i]的哈希函数值
while (1)
不冲突时 直接放到该处 { if (HT[j][0]=='\0') //
,
{ strcpy(HT[j],s[i]);
break;
}
else
//冲突时,采用线性线性探测法求下一个地址
j=(j+1)%M;
}
} for (i=0;i<M;i++)
printf("%2d",path[j]);
printf("\n");
}
else { path[i+1]=bt->key;
运筹学教程答案第九章
A B C D E
page 13 22 May 2012
5 8 3 6 10
A,C A C B,C
F G H I J
4 8 2 4 5
B,C C F,G E,H F,G
School of Management
运筹学教程
第九章习题解答
page 14 22 May 2012
School of Management
运筹学教程
第九章习题解答
表9-12 工时( ) 工作 工时(d) 紧前工作 工时( ) 工作 工时(d) 紧前工作
A B C D E F G H
page 15 22 May 2012
18 6 5 21 27 15 24 13
A A B B D,E
I J K L M N P Q
6 15 6 3 12 5 3 6
运筹学教程
第九章习题解答
9.1 有A,B,C,D,E,F 6项工作,关系分别 项工作, , , , , , 项工作 如图9-38(a),(b),试画出网络图。 如图 , ,试画出网络图。
page 1 22 May 2012
School of Management
运筹学教程
第九章习题解答
page 2 22 May 2012
School of Management
运筹学教程
第九章习题解答
9.4 绘制表 绘制表9-11,表9-12所示的网络图,并用表 所示的网络图, , 所示的网络图 上计算法计算工作的各项时间参数、确定关键路线。 上计算法计算工作的各项时间参数、确定关键路线。
表9-11 工时( ) 工作 工时(d) 紧前工作 工时( ) 工作 工时(d) 紧前工作
C++第九章习题解答
第九章流类库和输入/输出习题一.本概念与基础知识测试题9.1填空题9.1.1 在C++中“流”是表示(1)。
从流中取得数据称为(2),用符号(3)表示;向流中添加数据称为(4),用符号(5)表示。
答案:(1)数据从一个对象到另一个对象的传送(2)提取操作(3)>>(4)插入操作(5)<<9.1.2 抽象类模板(1)是所有基本流类的基类,它有一个保护访问限制的指针指向类(2),其作用是管理一个流的(3)。
C++流类库定义的cin,cout,cerr和clog是(4)。
cin通过重载(5)执行输入,而cout,cerr和clog通过(6)执行输出。
答案:(1)basic_ios(2)basic_streambuf(3)缓冲区(4)全局流对象(5)>>(stream_extraction operator)(6)<<(stream_insertion operator)9.1.3 C++在类ios中定义了输入输出格式控制符,它是一个(1)。
该类型中的每一个量对应两个字节数据的一位,每一个位代表一种控制,如要取多种控制时可用(2)运算符来合成,放在一个(3)访问限制的(4)数中。
所以这些格式控制符必须通过类ios的(5)来访问。
答案:(1)公有的无名的枚举类型(2)或“|”(3)保护(4)一个长整型数(5)公共接口(函数)9.1.4 取代麻烦的流格式控制成员函数,可采用(1),其中有参数的,必须要求包含(2)头文件。
答案:(1)流操作子(2)iomanip9.1.5 通常标准设备输入指(1)。
标准设备输出指(2)。
答案:(1)键盘(2)显示屏9.1.6 EOF为(1)标志,在iostream.h中定义EOF为(2),在int get()函数中读入表明输入流结束标志(3),函数返回(4)。
答案:(1)文件结束标志(2)-1(3)^Z(Ctrl-Z)(4)EOF9.1.7 C++根据文件内容的(1)可分为两类(2)和(3),前者存取的最小信息单位为(4),后者为(5)。
国际会计第七版英文版课后答案(第九章)
Chapter 9International Financial Statement AnalysisDiscussion Questions1. a. Business strategy analysisDifficulties in cross-border business strategy analysis: Identifying key profit drivers and business risk in two or more countries can be daunting. Business and legal environments and corporate objectives vary around the world. Many risks (such as regulatory risk, foreign exchange risk, and credit risk) need to be evaluated and brought together coherently. In some countries, sources of information are limited and may not be accurate.b. Accounting analysisDifficulties in accounting analysis: Two issues are important here. The first is cross-country variation in accounting measurement quality, disclosure quality, and audit quality. National characteristics that cause this variation include required and generally accepted practices, monitoring and enforcement, and extent in managerial discretion in financial reporting. The second issue concerns the difficulty in obtaining information needed to conduct accounting analysis. The level of credibility and rigor of financial reporting in Anglo-American countries generally is much higher than that found elsewhere. In fact, financial reporting quality can be surprisingly low in both developed and emerging-market countries.c. Financial analysis (ratio analysis and cash flow analysis)Difficulties in financial analysis: Extensive evidence reveals substantial cross-country differences in profitability, leverage, and other financial statement ratios and amounts that result from both accounting and non-accounting factors. Differences in financial statement items caused by national differences in accounting principles can be significant, and unpredictable in amount. Even after financial statement amounts are made reasonably comparable, interpretation of those amounts must consider cross-country differences in economic, competitive, and other conditions.d. Prospective analysis (forecasting and valuation)Difficulties in prospective analysis: Exchange rate fluctuations, accounting differences, different business practices and customs, capital market differences, and many other factors have major effects on international forecasting and valuation. Application of price multiples in a cross-border setting requires that the determinants of each multiple, and reasons why multiples vary across firms, be thoroughly understood. National differences in accounting principles are one source of cross-country variations in these ratios.Finally, all four stages of business analysis may be affected by:i. information access,ii. timeliness of informationiii. foreign currency issuesiv. differences in financial statement formatsv. language and terminology barriers.2. Here we will consider the information needs of investors, creditors, regulators, and competitors.Investors have high information needs at all stages of business analysis. They need to be able to accurately assess the merits of the company’s business strategy, the quality of its accounting, the company’s financial strength, and its future prospects. Since each step in the business analysis process builds on its predecessors, each step is critical in its turn. It can’t be said that any one step is more or less important than the others.Creditors need to go through much the same analysis, but are advantaged in that through direct contact with the companies they often have more extensive and detailed information than do investors. The goal of analysis is also often somewhat different. Many investors, hoping that their shares will increase in value, are interested in prospective analysis. The creditor’s interest is more often limited to being sure (with a margin of safety) that the loan will be repaid. For the creditor, the accounting analysis, financial analysis, and forecasting, all are important; valuation is less so. Regulators have much different interests. Since regulators have no direct interest in the future earnings of the companies they regulate, a prospective analysis (in most cases) is of limited value to them. However, if regulators need to be aware of the financial strength of the companies they regulate, they will need to conduct accounting analysis and (in many cases) financial analysis, particularly when assessing how much of an economic burden can be imposed on companies resulting from a particular regulation.Competitors are intensely interested in finding out as much about a company as possible. Business strategy analysis of one’s competitors is an important part of formulating one’s own business strategy, especially in terms of assessing strengths and weaknesses. Accounting and financial analysis also can uncover strengths and weaknesses. Prospective analysis may be important if a merger or acquisition is contemplated.3. Information accessibility is a major condition for an efficient capital market, that is, information must be rapidly analyzed and made available to investors capable of acting on it. In the United States and other broadly-based financial markets, a whole industry specializing in information analysis and dissemination has developed. Similar investment analysis services in many non-U.S. capital markets are at an earlier stage of development.4. Investment analysis almost always involves paired comparisons, even if the benchmark alternative is to do nothing. In evaluating the risk and return characteristics of a non-domestic company differences in accounting measures of risk and return are often due as much to differences in measurement rules between countries as they are to real economic differences. Corporate transparency compounds the problem by depriving analysts of information necessary to adjust for national measurement differences. Many analysts consider the disclosure issue to be even more important than measurement differences.5. One way of coping with GAAP differences is to restate foreign accounting measures to an internationally recognized set of principles or the reporting framework of the investor’s home country. An alternative tack is to develop a detailed understanding of accounting practices in the investee’s country.Students will definitely disagree on this one. Eventually some will offer a compromise: use the former coping mechanism if the investee company is being compared with a firm in the investor’s home country and adopt a “multiple principles capability” when comparing the investee company to another company in the same country. Another tack would be to examine who is making the market for the investee’s shares. If local investors are making th e market, one should not ignore local norms. However, if investors in the investor’s country are making the market; e.g., U.S. institutional investors, then restatement to the investor’s home country GAAP makes sense.6. Prospective analysis invo lves forecasting a firm’s future cash flows and then valuing those cash flows. As future cash flow estimates are based on accounting measurements, differences in measurement rules between countries complicate this effort. The range of accounting choicesavailable abroad add to this complexity. However, measurement differences are only one of the variables that complicates prospective analysis, Differences in environmental variables such as rates of inflation, sovereign risk, business practices, and institutions complicate both forecasting and valuation. Different institutions include financial norms, tax regimes and market enforcement mechanisms. In terms of valuation, while P/E multiples may be popular in one country, discounted dividends may be more popular in another. Even if two countries employ the same valuation framework, differences in investment horizons and methods of calculating discount rates/cost of capital will vary.7. Translation of foreign financial statements for the convenience of domestic readers is fundamentally distinct from the translation of branch or subsidiary accounts for purposes of consolidation. In the latter case, translation involves a remeasurement process. In most countries, foreign accounts first are restated to the accounting principles of the parent country prior to restatement to parent currency. Convenience translations merely involve a restatement process in the sense that foreign accounts are multiplied by a constant to change the currency of denomination fro m domestic currency to the currency of the reader’s domicile.8. Rules of thumb can vary substantially from one country to another due to both accounting and non-accounting factors. Japan provides a striking example. Many Japanese companies are members of large trading groups (keiretsu) with large commercial banks at their core. Keiretsu often postpone interest and principal payments, so that long-term debt in Japan works more like equity in the United States. Short-term debt is attractive to Japanese companies because short-term obligations typically have lower interest rates than long-term obligations, and normally are renewed or “rolled over” rather than repaid. Thus, debt has a much different nature and purposein Japan than in the United States.The acid test ratio specifically involves cash, marketable securities and receivables as the numerator in the equation, and current liabilities as the denominator. But what counts as current liabilities versus long-term debt (or how long-term debt is viewed) is very different in Japan than in the U.S. In Japan, high short-term debt is less likely to indicate a lack of liquidity, for the reasons stated above. Banks often are willing to renew these loans because it allows them to adjust their interest rates to changing market conditions. Thus, short-term debt works like long-term debt elsewhere, and Japanese companies can operate successfully with a quick ratio at a level that would be entirely unacceptable in the United States. Note, however, that banking practices in Japan are changing rapidly, and the tolerance in Japan for high levels of debt financing may well decrease in the future.9. Important recommendations include the following:•Be aware that national differences in accounting measurement rules c an add “noise” to reported performance comparisons. The reader should be prepared to unwind accounting differences where necessary.•Use a structured approach, such as the one presented in this chapter, to ensure that all relevant factors are considered.•Cash flow-related measures are less affected by accounting principle differences than are earnings-based measures, thus making them potentially valuable in international analysis.•Audit quality varies dramatically across countries. Become familiar with the level of audit quality in a particular country before reaching conclusions using financialstatements prepared by companies in that country.•Corporate transparency also varies dramatically across countries. Be sure to assess accurately the quality of financial disclosures before reaching conclusions based on them.•Above all, appreciate that measurement and disclosure practices are environmentally based. Appreciation for institutional differences will greatly aid in proper interpretation of accounting based performance and risk measures.10. The following list describes in general fashion what probable effect the Dutch translation practice would have on selected financial ratios in comparison with the temporal method. The analysis assumes that the original financial statements of the two companies are identical in all respects save for the currency translation method used. Inventories are assumed to be carried at cost._________________________________ _______________________________________________ Devaluation ___ R evaluationCurrent ratio (liquidity) decrease increaseInv. At mkt goes downInv at mkt goes upDebt ratio (solvency) increase decreaseLoss goes in ATA so eq. smallerGain in ata eq lrg.Fixed asset turnover (efficiency) increase decreaseNet sales/assets assets smaller so inc.A ssets larger so dec.Return on assets (profitability) increase decreaseloss not in incomeGain not in incomeAs can be seen, the current rate method can have a significant effect on key financial indicators. Accordingly, security analysts must be careful to distinguish between the currency in which a foreign account is denominated and the currency in which it is measured.11. The attest function is what gives credibility to the financial statements. If this function is important in the domestic case, it is even more important internationally where statement readers are separated from the companies they are interested in not only by physical distance but also by cultural distance.12. Internal control is an activity performed by a firm’s int ernal auditors that helps to assure that management’s policies and procedures are being carried out effectively, that financial transactions are being properly reported both internally and externally and that the assets of the firm are safeguarded. Intern al control is relied upon by a firm’s external auditors in determining to what extent their work should replicate the work of the internal auditor. The role of the internal auditor has become even more important in assuring the reliability of management’s financial representations owing to the large number of financial scandals that has rocked the U.S. and other financial markets during the start of this decade. Recent legislation in the U.S., which is increasingly being emulated elsewhere, has made management responsible for assuring that their system of internal controls are not only in place but are working well. This has beennecessary to reduce investor uncertainty regarding the quality and reliability of a firm’s published financial accounts.In the absence of a strong system of internal controls, investors will adopt a more passive approach to investing as opposed to relying on firm-specific information. This involves taking a mutual fund approach to investing which attempts to diversify away information risk, although at the cost of lesser performance.Exercises1. The trend of dividends from a U.S. dollar perspective can be ascertained by translating the peso dividend stream using the $/P exchange rate prevailing at the beginning of the time series or the end. Use of the ending exchange rate provides the following trend data:20X6 ________ 20X7 ________ 20X8 ______Net income (P) 8,500 10,800 15,900Dividends (P mill’s)2,550 3,240 4.770Dividends ($000) 850 1,080 1,590Percentage change --- 27.1% 47.2%2.How the statement of cash flows appearing in Exhibit 9.5 was derived:Beg. Bal. DR. CR. End. Bal.Cash 2,400 3.990New fixed assets 8,500 (3) 2,695 (2) 555 10,640ST $ payable 500 500LT debt 4,800 (3) 1,584 6,384Capital stock 3,818 3,818Retained earnings 1,782 (1) 250 2,030Translation adjustment 1,898Sources Usesof ofFunds FundsSources:Net income (1) 250Depreciation (2) 555Increase in LT debt (3) 1,584Translation adjustment (4) 1,898Uses of funds:Increase in fixed assets (3) 2,6954,287 2,695Net increase in cash 1,5924,287 4,2873. Consolidated Funds Statement(figures appearing in parentheses denote changes due primarily to translation effects) Sources:Net income 250Depreciation 555Increase in LT debt 1,584 (1,584)Translation adjustment 1,898 (1,898)less intercompany payable 138Uses of funds:Increase in fixed assets 2,695 (2,695)Net increase in cash 1,590 (924) The $924 translation effect is that part of the $1,898 gain on the translation of net worth which is related to the translation of cash. It is derived as follows.a. Opening cash of 24,000 krona translated at .10 =$2,400Opening cash retranslated at 12/31 at .133 = 3,192Gain 792b. 6,000 krona increase in cash during the yearinitially translated at .111 =$6666,000 krona retranslated at 12/31 at .133 = 798Gain 132Total translation gain applicable to cash 9244. Yes, Infosys added value for its shareholders as its EVA was a positive RPE 1,540. Operating income more than covered the company’s cost of debt and equity.5. Debit: Cost of goods sold ¥250,000,000Taxes payable 87,500,000Credit Inventories ¥250,000,000Tax expense 87,500,0006. a.20X6 20X7 20X8Sales revenue (£) 23,500 28,650 33,160Sales revenue ($) 49,350 63,030 53,056b. Percentage change 20X7/20X6 20X8/20X7Pounds 21.9% 15.7%Dollars 27.8% -15.8%The two time series do not move in parallel fashion because of changes in exchange rates used to perform the convenience translations.c. This problem can be minimized by translating the time series using the 20X6 exchange rate or by using the 20X8 exchange rate. Trend analysis can also be performed in the local currency.7. a. ROE (per Swedish GAAP) = 4,709/88,338 = 5.3%ROE (per U.S. GAAP) = 3,127/84,761 = 3.7%b. Some students will favor using the ROE based on Swedish GAAP, especially if Volvo’sperformance is being compared with that of another company in Sweden. Others willfavor basing their performance assessment on ROE per U.S. GAAP, especially if Volvois being compared to a U.S. counterpart. The latter at least minimizes the apples tooranges issue. It is not clear which viewpoint is correct, and this question should provoke good discussion of the value of restated accounting numbers.c. Even if students all agreed that an ROE based on U.S. GAAP were preferable, the user ofthis information should take into account all institutional considerations, such asdifferences in tax laws, financial norms and business practices that affect all ratios in the Swedish business environment. In the absence of such analysis, restated ratios are likely to be misinterpreted.8. Assessing reasons for P/E ratio trends and cross-country comparisons is difficult. Thetext discusses two studies that have analyzed differences in P/E ratios between Japan and the United States in the late 1980s. The studies differ greatly in their explanations of the(then) much higher Japanese P/E ratios, and neither study claims to explain more than apart of the difference. Part but not all of the reasons were attributable to accountingmeasurement differences. We suspect that differences in institutional factors probablyexert the dominant reason for observed differences internationally.9. Students answers will naturally vary. However, they should recognize that audit practiceare influenced as much by differences in social, economic and political environments as are measurement standards. They should also recognize that standard setting is as mucha political process as it is a process of logic or sound principles.10. Judging from information provided in Exhibit 9-22, liability cases vary far more bycountry than by auditor – with 35 cases in the U,.S., over twice as many as in the nexthighest country (the U.K., with 17). No audit firms had cases in every country, and thetotal number for each auditor is relatively similar, ranging from 11 (Arthur Andersen) to18 (KPMG). The country where liability cases were least frequent was the Netherlands,with only one case.Why? Laws and regulations in the Anglo-American countries, including the UnitedStates, stress investor protection. This places more liability on the auditor and makes iteasier for companies or shareholders to bring or prove a suit. In response to the threat of litigation, auditors are probably more careful in the United States, and more willing tosubject themselves to strict regulations.Implications? It is reasonable to argue that financial reporting quality is positivelycorrelated with frequency of audit litigation. For example, the patterns of auditorlitigation shown in the table above are consistent with the relatively high financialreporting quality found in the U.S., the U.K., Australia and Canada.11. Student opinions are likely to vary on this one as well. Some will argue for opinionscoined by private professional bodies. Others, in light of Enron, et. al., will opt for more legal opinions. In the end, students should conclude that enforcement mechanisms arealso very important. Recent U.S. indictments of company officers for accountingviolations as well as mandated prison terms is unprecedented. Together with increasing recourse to the courts by aggrieved investors, the imbalance between an auditor’sresponsibility and authority is being redressed.12. Reasonable criteria for judging the merits of a database for company research include(but are not limited to):-coverage (number of companies, countries, years of data).-amount of information for each company (number of financial, market-based measures per company).-reliability, ease of use, language translations, search features.-cost (a re only some of the data “freely available?”).-access and links to other Web sites provided?Case 9-1Sandvik1.a. There are several advantages that accrue to Swedish firms employing the system of special reserves. First, political dividends accrue to firms that align their goals with those of the government. Second, there are tax advantages as expenses recognized in establishing a reserve are tax deductible. Third, the use of reserving allows companies to manage their earnings. Disadvantages include the risk of reducing a company’s reporting credibility with the international investing community. This, in turn, may limit the company’s external financing flexibility.2. The government benefits from the reserving system in that it has ally in maintaining full employment. That is to say, its macroeconomic tool kit is expanded in that it yet another vehicle for managing the economy in addition to monetary and fiscal policy.3. The use of reserves makes it difficult for statement readers who are unfamiliar with Swedish reporting practices to assess the risk and return attributes of the firm. For example, it will not be clear to what extent observed differences in financial ratios between a Swedishcompany and a non-Swedish company are due to accounting differences as opposed to real economic differences in the attributes being measured.4. The use of reserves had a dampening effect on Sandvik’s reported earnings.5. The entries used to increase the reserves can be determined by examining the change in Untaxed Reserves in the balance sheet as well as examining the relevant notes to the financial statements. The entries were:Depreciation expense 172Excess depreciation reserve 172Other expenses 13Other untaxed reserves 136. With reserves Without reservesROS 3,731/15,242 3,731 + 185(1-.03)/15,242= 24.5% = 25.7%ROA 3,731 + 1 + 633 3,731 + 1 + 633 + 185(38,142 + 22,286)/ 2 [(38,142 – 185) + (22,286 + 85)] /2= 14.4% = 15.1%Case 9-2Continental A.G.Students will first gravitate to the notes to the financial statements dealing with Special Reserves and Provisions. Their instincts are correct. The problem facing an external analyst is that it is difficult to determine which of the reserve and provision items are legitimate and which are not. It turns out that two important keys to this case are to be found in footnotes 21 and 22. Focusing on the consolidated figures, we see that Continental is using entries under Other operating income and Other operating expenses to smooth reported earnings. The following analysis backs out 1) Credit to income from the reversal of provisions, 2) Credit to income from the reduction of the general bad debt reserve, and 3) Credit to income from the reversal of special reserves appearing in note 21 and Allocation to special reserves under note 22.Adjustments:19X9Operating income DM68,029Provisions DM33,559General B/D Reserve 2,014Special reserve 32,456Special reserves 1,278Operating income 1,27820X0Operating income DM57,237Provisions DM17,312General B/D Reserves 1,101Special Reserves 38,824Special Reserves 168Operating income 168To determine the net overstatement on an after-tax basis, the students should attempt to approximate Continental’s effective tax rate. Information to do this are contained in footnote 24 and Continental’s income statement.Effective Taxes: 19X9 20X0Income tax 141,476 59,884Income after tax 227,838 93,435Income before tax 369,314 153,319Effective rate: 141,476/369,314 59,884/153,319= 39% = 39%Reduction in taxes:66,751 X .39 57,069 X .39= 26,033 = 22,257Net overstatement:66,751 57,069-26,033 -22,25740,718 34,812This overstatement, as a percentage of reported consolidated earnings, was 18% for 19X9and 37% for 20X0. Dietrich and Marissa have cau se to pay Continental’s CFO a visit.。
java复习题
第一章1.下面(A)是JDK的java编译工具。
A.javac B. javadoc C. java D. javaw2.main方法中传递的参数类型是(D)。
A. IntegerB. V ariantC. ShortD. String3.在屏幕上显示消息正确的语句是(A)。
A. System.out.println(“I am a student!”);B. system.out.println(“I am a student!”);C. System.Out.println(“I am a student!”);D. System.out.printline(“I am a student!”);4.Java程序被编译后,将产生(B)。
A.exe代码 B.字节码 C.机器代码 D.都不正确5.Java源程序的扩展名为(B)。
A. .classB. .javaC. .objD. .c6.在一个java文件中定义了3个类,其中属性为public的类最多有(A)个。
A. 3B. 2C. 1D. 07、已知Hello.java文件的内容如下:Public class Hello{Public static void main(String args[]){System.out.println(“Hi,everybody”);}}下列说法正确的是()。
A、在命令提示符,运行命令javac Hello.java,然后运行命令javac Hello,结果显示Hi,everybodyB、在命令提示符,运行命令javac Hello,然后运行命令javac Hello.class,结果显示Hi,everybodyC、在命令提示符,运行命令javac Hello.java,然后运行命令javac Hello.class,结果显示Hi,everybodyD、在命令提示符,运行命令javac Hello,然后运行命令javac Hello.class,结果显示Hi,everybody第二章选择题下面关于if条件语句描述错误的是(A)if语句中只能有一个else子句if语句中可以有多个else if子句if语句中的if体内可以有循环语句if语句可以相互嵌套下面for循环语句的循环次数为(A)for(int i=0 、j=0; i=j=5;i++、j++);A. 0B.1C.5D.无限次3. 下面哪一个不是Java语言的关键字?(D)A.private B.package C.String D.variable4. 下面哪一个不是Java语言中合法的标识符?(C)A.thisPhoto B._Point C.%myColor D.Point45. 下列表达式中,(B)表达式的值为false。