
香港注册会计师考师审计笔记6
Lecture Topic – IT environments – Computer systemsLecture ReferencesAuditing, HKIAAT 2006 edition Ch. 24-27Modern Auditing & Assurance Service, 2nd Edition ChHKICPA Member’s Handbook: PN1001/1002______________________________________________________________________________ 1IntroductionThis topic describes the effects of an on-line computer system and stand alone PC on the accounting system and related internal controls and on audit procedures.2On-Line Computer SystemsOn-line computer systems are computer systems that enable users to access data and programs directly through terminal devices. Such systems may comprise mainframe computers, minicomputers or a network of connected PCs. When the entity uses an on-line computer system, the technology is likely to be complex and linked with the entity's strategic business plans. The audit team may require special IT skills to make enquiries and to understand the implications of the responses obtained.1 The auditors may need to consider using the work of an expert (see SAS 520 "Using the work of an expert").On-line systems allow users to directly initiate various functions such as:(a)entering transactions (for example, sales transactions in a retail store, cashwithdrawals in a bank and shipment of goods in a plant);(b)making enquiries (for example, current customer account status or balanceinformation);(c)requesting reports (for example, a list of inventory items with negative "on hand"quantities);(d)updating master-files (for example, setting up new customer accounts andchanging general ledger codes); and(e)electronic commerce activities (for example, placing orders and paying for goodsover the Internet).On-line computer systems use many different types of terminal devices. The functions they perform vary widely, and depend on their logic, transmission, storage and basic processing capabilities. Types of terminal devices are:(a)general purpose terminals, such as:basic keyboard and screen - used for entering data without any validation within the terminal and for displaying data from the computer system on thescreen. For example, in entering a sales order, the main computer validatesthe product code and the terminal screen displays the result of the validation;intelligent terminal - used for the functions of the basic keyboard and screen with the additional functions of validating data within the terminal,maintaining transaction logs and performing other local processing. In theabove sales order example, the intelligent terminal verifies the correctnumber of characters in the product code and the main computer verifies theexistence of the product code in the master-file;PCs - used for all of the functions of an intelligent terminal with additional local processing and storage capabilities. Continuing the above example, thePC may perform all the verifications of the product code;(b)special purpose terminals, such as:point-of-sale devices - used to record sales transactions as they occur and to transmit them to the main computer. On-line cash registers and opticalscanners used in the retail trade are typical point-of-sale devices;automated teller machines - used to initiate, validate, record, transmit and complete various banking transactions. Depending on the design of thesystem, certain of these functions are performed by the automated tellermachine and others are performed on-line by the main computer;hand-held wireless devices for entering data from remote locations;voice response systems - used to allow user interaction with the computer over a telecommunications network based on verbal instructions issued bythe computer. The customer communicates using a tone-generating device,which is often the keypad on the customer's telephone. Common applicationsinclude telephone banking and bill payment systems.Terminal devices may be found either locally or at remote sites. Local terminal devices are connected directly to the computer through cables, whereas remote terminal devices require the use of telecommunications to link them to the computer. In some cases, however, even local terminals may be connected using telecommunications links or wireless communication links. Terminal devices may be accessed by many users, for different purposes, in different locations, all at the same time. Users such as customers or suppliers may be within the entity or outside. In such cases, application software and data are kept on-line to meet users' needs. These systems also require other software, such as access control software and software that monitors on-line terminal devices.Increased sharing of system resources through LANs and WANs has led to the growth of distributed online processing. Client/Server systems have resulted in applications being split, so that processing can be performed across several machines. In a client/server environment, the processing of data takes place on the server and the desktop computer (client).Employees, business partners, customers and other third parties may obtain access to an organization's on-line applications by using the Internet or other remote access services.External parties may access the organization's applications through electronic data interchange (EDI) or other electronic commerce applications.In addition to the users of these systems, programmers may use the on-line capabilities to develop new programs and maintain existing programs. Computer supplier personnel may also have on-line access to provide maintenance and support services.2.1Types of On-Line Computer SystemsOn-line computer systems may be classified according to how information is entered into the system, how it is processed and when the results are available to the user. On-line computer systems functions are classified as follows:(a)on-line/real-time processing;(b)on-line/batch processing;(c)on-line/memo update (and subsequent processing);(d)on-line/inquiry; and(e)on-line downloading/uploading processing.On-Line/Real-Time ProcessingIn an on-line/real-time processing system, individual transactions are entered at terminal devices, validated and used to update related computer files immediately.An example is the application of cash receipts directly to customers' accounts. Theresults of such processing are then available immediately for inquiries or reports.On-Line/Batch ProcessingIn a system with on-line input and batch processing, individual transactions are entered at a terminal device, subjected to certain validation checks and added to atransaction file that contains other transactions entered during the period. Later,during a subsequent processing cycle, the transaction file may be validated furtherand then used to update the relevant master-file. For example, journal entries maybe entered and validated on-line and kept on a transaction file, with the generalledger master-file being updated on a monthly basis. Inquiries of, or reportsgenerated from, the master-file will not include transactions entered after the lastmaster-file update.On-Line/Memo Update (and Subsequent Processing)On-line input with memo update processing, also known as shadow update, combines on-line/real time processing and on-line/batch processing. Individualtransactions immediately update a memo file containing information that has beenextracted from the most recent version of the master-file. Inquiries are made fromthis memo file. These same transactions are added to a transaction file forsubsequent validation and updating of the master-file on a batch basis. For example,the withdrawal of cash through an automated teller machine is checked against thecustomer's balance on the memo file, and is then immediately posted to thecustomer's account on that file to reduce the balance by the amount of thewithdrawal. From the user's perspective, this system will seem no different fromon-line/real time processing since the results of data entered are availableimmediately. However, the transactions have not been subjected to completevalidation before the master-file update.On-Line/InquiryOn-line inquiry restricts users at terminal devices to making inquiries of master-files. In such systems, the master-files are updated by other systems, usuallyon a batch basis. For example, the user may inquire of the credit status of aparticular customer before accepting an order from that customer.On-Line Downloading/Uploading ProcessingOn-line downloading refers to the transfer of data from a master-file to an intelligent terminal device for further processing by the user. For example, data atthe head office representing transactions of a branch may be downloaded to aterminal device at the branch for further processing and preparation of branchfinancial reports. The results of this processing and other locally processed datamay then be uploaded to the head office computer.2.2Characteristics of On-Line Computer SystemsThe characteristics of on-line computer systems may apply to many of the types of on-line systems discussed in the previous section. The most significant characteristics relate to on-line data entry and validation, on-line access to the system by users, possible lack of visible transaction trail and potential access to the system by non-users, including programmers and other third parties (for example, through e-mail and the Internet). The particular characteristics of a specific on-line system will depend on the design of that system.When data are entered on-line, they are usually subject to immediate validation checks.Data failing this validation are not accepted and a message may be displayed on the terminal screen, providing the user with the ability to correct the data and re-enter the valid data immediately. For example, if the user enters an invalid inventory part number, an error message is displayed, allowing the user to re-enter a valid part number.Users may have on-line access to the system that enables them to perform various functions (for example, to enter transactions and to read, change or delete programs and data files through the terminal devices). Unlimited access to all of these functions in a particular application is undesirable because it provides the user with the potential ability to make unauthorized changes to the data and programs. Unlimited access precludes segregation of duties and allows users access to all stages of processing and recording a transaction. The extent of this access depends on things such as the design of the particular application and the implementation of software designed to control access to the system.An on-line computer system may be designed not to provide supporting documents for all transactions entered into the system. Such a system must be able to provide details of the transactions on request or by transaction logs or other means. Examples of these types of systems include orders received by a telephone operator who enters them on-line without written purchase orders, and cash withdrawals from automated teller machines.Programmers may have on-line access to the system that enables them to develop new programs and modify existing programs. Unrestricted access provides the programmer with the potential to make unauthorized changes to programs and obtain unauthorized access to other parts of the system and would represent a serious control weakness. The extent of this access depends on the requirements of the system. For example, in some systems, programmers ordinarily have access only to programs maintained in a separate program development and maintenance library. Programmers may, however, be authorized to change the operational programs in emergencies that require changes to programs kept online. In such cases, formal control procedures would be followed after the emergency to ensure appropriate authorization and documentation of the changes.2.3Internal Control in an On-Line Computer SystemApplications in an on-line environment may have greater exposure to unauthorized access and update. An entity's security infrastructure plays an important part in ensuring the integrity of the information produced. The auditors, therefore, consider the security infrastructure before examining the general and application controls. The entity may need to establish suitable general controls to mitigate the risks of viruses, unauthorized access and the potential destruction of audit trails. Hence access controls are particularly important to on-line processing.These controls may include the use of passwords and specialized access control software, such as on-line monitors, that maintains control over the menus, authorization tables, passwords, files and programs that users are permitted to access. They may also include physical controls such as the use of key locks on terminal devices, locked computer rooms and inactivity timeouts.Other important aspects of control in an on-line computer system include:(a)controls over passwords: procedures for the assignment and maintenance ofpasswords to restrict access to authorized users;(b)system development and maintenance controls: additional procedures to ensure thatcontrols essential to on-line applications, such as passwords, access controls, on-linedata validation and recovery procedures, are included in the system during itsdevelopment and maintenance; the controls are also designed to ensure that changesto systems operate as expected and are made in the correct manner;(c)programming controls;(d)transaction logs; and(e)firewalls.Certain application controls are particularly important to on-line processing. These include the following:(a)Pre-processing authorization. Authorization to initiate a transaction, for example, byusing a bank card together with a personal identification number before being able tomake a cash withdrawal through an automated teller machine.(b)Terminal device edit, reasonableness and other validation tests. Programmed routinesthat check the input data and processing results for completeness, accuracy andreasonableness. These routines include sequence, limit, range and reasonablenesschecks and may be performed on an intelligent terminal device or on the centralcomputer.(c)Input error reporting and handling. Procedures to ensure that all input errors areproperly reported, identified and rejected from further processing, corrected andresubmitted for processing in a timely manner. These procedures will generallycomprise a mix of both manual and automated routines.(d)Cut-off procedures. Procedures that ensure transactions are processed in the properaccounting period. These are particularly necessary in systems that have a continuousflow of transactions. For example, in on-line systems where terminal devices invarious locations record sales orders and shipments, there is a need to coordinate theactual shipment of goods, inventory release and invoice processing.(e)File controls. Procedures that ensure the correct data files are used for on-lineprocessing.(f)Master file controls. Changes to master-files are controlled by procedures similar tothose used for controlling other input transaction data. More stringent enforcement ofthese control procedures may be necessary because master file data may have apervasive effect on processing results.(g)Balancing. The process of establishing control totals over data being submitted forprocessing through the on-line terminal devices and comparing the control totalsduring and after processing to ensure that complete and accurate data are transferredto each processing phase. These balancing controls are important to monitoringcompleteness and accuracy controls in a real-time processing environment. Theyshould be included in the automated program routines whenever possible.(h)Control may be established by an independent function that generally:i.receives all data for processing;ii.ensures that all data are authorized and recorded;iii.follows up all errors detected during processing;iv.verifies the proper distribution of output; andv.restricts physical access to application programs and data.Separate controls are ordinarily required over master file and transaction data.2.4Effect of On-Line Computer Systems on the Accounting System and Related InternalControlsThe effect of an on-line computer system on the accounting system and the associated risks will generally depend on:(a)the extent to which the on-line system is being used to process accountingapplications;(b)the type and significance of financial transactions being processed; and(c)the nature of files and programs the applications use.The entity's security infrastructure plays an important part in controlling the effect of the risks created by the entity's use of an on-line environment.Factors such as the following may reduce the risk of errors occurring because of the entity's use of online systems:a)Performing data entry at or near the point where transactions originate reduces therisk that the transactions will not be recorded.b)Immediate correction and re-entering of invalid transactions reduces the risk thatsuch transactions will not be corrected and resubmitted quickly.c)Data entry performed by individuals who understand the nature of the transactionsinvolved may be less prone to error than when performed by individuals unfamiliarwith the nature of the transactions.d)Processing transactions immediately reduces the risk that they will be processed inthe wrong accounting period.e)Authentication and authorization carried out at or near the point where transactionsoriginate reduces the risk of impersonation or other unauthorized access to ormanipulation of data.The risk of errors in on-line computer systems may be increased for the following reasons:(a)Locating terminal devices throughout the entity increases the opportunity forunauthorized use of a terminal device and the entry of unauthorized transactions.(b)On-line terminal devices may provide easier opportunity for unauthorized usessuch as:i.Modification of previously entered transactions or balances;ii.Modification of computer programs; oriii.Access to data and programs from remote locations.(c)If on-line processing is interrupted for any reason, for example, due to faultytelecommunications, there may be a greater chance that transactions or files maybe lost and that the recovery may not be accurate and complete.(d)On-line access to data and programs from remote sites throughtelecommunications may provide greater opportunity for access to data andprograms by unauthorized persons. Organizations that have links to the Internetrequire greater controls, such as firewalls, to manage the risk of unauthorizedaccess to data and programs.(e)The use of electronic commerce and EDI for the exchange of documents betweentwo organizations results in the loss of traditional paper audit trails, includinginvoices and purchase orders.The characteristics of on-line computer systems illustrate some of the considerations influencing the effectiveness of controls in on-line computer systems. Such characteristics may have the following consequences:(a)there may not be printed source documents for every input transaction;(b)results of processing may be highly summarized; for example, only totals fromindividual on-line data entry devices can be traced to subsequent processing;(c)the on-line computer system may not be designed to provide printed reports; forexample, edit reports may be replaced by edit messages displayed on a terminaldevice screen;(d)on-line computer systems running real-time processes pose particular difficultiesfor auditors as it can be difficult to achieve a clear cut-off of data. It can also bedifficult in some IT environments to stop real-time processing long enough toobtain copies of data files or to run important reports for audit purposes at periodend; and(e)in the event that real time systems have to be restored, it is difficult to ensure thatall of the data is properly reinstated and, importantly, that all systems integrationinterfaces and data feeds are reset to the date and time of the back-up data.2.5Effect of On-Line Computer Systems on Audit ProceduresIf those controls are deemed satisfactory, the auditors will place greater reliance on internal controls in the system when determining the nature timing and extent of audit procedures. The characteristics of on-line computer systems may make it more effective for the auditors to perform a pre-implementation review of new on-line accounting applications rather than to review the applications after installation. To be fully effective, the review may need to extend to other applications that provide data for those accounting applications; the auditors may also test that the new system operates and is implemented as designed. The pre-implementation review may provide the auditors with an opportunity to request additional functions, such as detailed transaction listings, or controls within the application design. It may also provide the auditors with sufficient time to develop and test audit procedures in advance of the system's use. In contrast, when the entity adopts a policy of continuous systems' upgrading, the change management procedures adopted may be critical to the on-going effectiveness of the controls in place. The auditors may therefore examine the change management procedures rather than perform pre-implementation reviews.The following matters are of particular importance to the auditors in an on-line computer system:authorization, completeness and accuracy of on-line transactions through the implementation of appropriate controls at the time when the transaction is acceptedfor processing;integrity of records and processing, due to many users and programmers having on-line access to the system; andnecessary changes in the performance of audit procedures, including the use of CAATs, due to matters such as:(a)the need for audit teams with technical skills in on-line computer systems;(b)the effect of the on-line computer system on the timing of audit procedures;(c)the lack of visible transaction trails;(d)procedures carried out during the audit planning stage;(e)audit procedures performed concurrently with on-line processing; and(f)procedures performed after processing has taken place.Procedures carried out during the planning stage may include the following: the participation on the audit team of individuals with technical proficiency in on-line computer systems and related controls;identification of any new remote access facilities; andpreliminary determination, during the risk assessment process, of the impact of the system on the audit procedures.Audit procedures performed concurrently with on-line processing may include tests of the controls over the on-line applications. For example, this may be by means of entering test transactions through the online terminal devices or by the use of audit software. These tests may be used either to confirm the auditors'understanding of the system or to test controls such as passwords and other access controls. Where the entity permits access through the Internet, audit procedures can include tests of firewalls and other authorization and access controls, as well as tests of transaction processing. To avoid the inadvertent corruption of client records, the auditors review concurrent procedures with appropriate client personnel and obtains approval before conducting the tests.Procedures performed after processing has taken place may include the following:tests of controls over transactions logged by the on-line system for authorization, completeness and accuracy;substantive procedures covering transactions and processing results rather than tests of control, where the former may be more cost-effective or where the system is notwell-designed or controlled; andreprocessing transactions as either a test of control or a substantive procedure.3Stand-Alone PCsPCs can be used to process accounting transactions and produce reports that are essential to the preparation of financial statements. The PC may constitute the entire computer-based accounting system or merely a part of it.Generally, information technology (IT) environments in which stand-alone PCs are used are somewhat different from other IT environments. Certain controls and security measures that are used for large computer systems may not be practicable for PCs. In contrast, certain types of internal controls become more important because of the characteristics of stand-alone PCs and the environments in which they are used.Stand-alone PCs can be operated by a single user or many users at different times accessing the same or different programs on the same computer. The user of a stand-alone PC that processes accounting applications performs many functions (for example, entering data and operating application programs). While typically not knowledgeable about programming, users may often use third-party or off-the-shelf software packages such as electronic spreadsheets or database applications.The organizational structure within which a stand-alone PC is used is important in assessing risks and the extent of the controls required to mitigate those risks. For example monitoring controls employed by management may be the only effective controls for a purchased software package used by a small business on a stand-alone PC apart from whatever controls are incorporated in the package itself. In contrast, the effectiveness of controls relating to a stand-alone PC used within a larger organization may depend on an organizational structure that clearly segregates responsibilities and restricts the use of the stand-alone PC to specific functions.The control considerations and the characteristics of the hardware and software are different when a PC is linked to other computers. Such situations often lead to increased risks. This PN does not address the auditors'consideration of network security and controls. This PN is however relevant for PCs that are linked to another computer, but can also be used as stand-alone workstations. Many PCs may be used interchangeably as part of a network or in stand-alone mode. When dealing with such PCs, the auditors consider the additional risks encountered by access through a network as well as the guidance in this3.1Internal Control in Stand-Alone PC EnvironmentsPCs are oriented to individual end-users. The degree of accuracy and reliability of financial information they produce will depend, in part, on the internal controls that the user adopts either voluntarily or because management has prescribed them. The control procedures implemented relate to the complexity of the business environment in which the PC operates. Ordinarily, the stand-alone PC environment is less structured than a centrally controlled IT environment. In the former, users with only basic data processing skills can implement application programs relatively quickly, triggering issues such as the adequacy of systems'documentation or access control procedures. Such users may not regard controls over the application implementation process (for example, adequate。
香港注册会计师考师审计笔记试卷_Sep1999

SECTION A:SHORT ANSWER QUESTIONS (Total: 30 marks)Short Question 1James Wong, a CPA with several years experience, has been selected by his firm to be the in-charge auditor of a continuing client. James will supervise three junior auditors, and be responsible for all phases of the audit. The client has a 31 December year end. James intends to do audit planning in September and conduct interim control tests in October.(a) What are the most important uses of the results of the October control tests?(b) What are the issues involved in performing procedures prior to the end of theyear?(3 marks) Short Question 2In auditing the XYZ company cash accounts, you are instructed to obtain bank statements with twelve monthly bank reconciliations, and an independently obtained bank confirmation. Explain the possible uses of both of these types of evidence and indicate whether each constitutes a control test or a substantive procedure.(3 marks) Short Question 3The use of automated processes in accounting systems have both the potential for increasing as well as decreasing the possibility of errors and irregularities. Discuss briefly reasons why computerised accounting may increase the possibility of errors and irregularities, and reasons why computerised accounting may decrease the possibility of errors.(3 marks) Short Question 4The PQR Company hired a new accounting controller to replace the former controller who retired in August. The new controller has experience in the industry, but is not yet familiar with the PQR Company procedures. As the long-time auditor for PQR, you evaluate internal control during October and November.(a) How will having a new controller change your perception of control risk?(b) What actions will you as the auditor need to take as a result of this change in akey client employee?(3 marks) Short Question 5In your audit of the XYZ Company Ltd., you substantively tested the accounts receivable balance by sending out positive confirmations for approximately 30% of the total accounts receivable balance. Upon their return from customers of XYZ, some of the confirmations revealed certain discrepancies.(a) Compare and contrast what the auditor should do if the amount of thediscrepancy is material versus immaterial.(b) What should you do in the following year as a result of the current year'sfindings, and why?(3 marks) Short Question 6Henry is a CPA who has been auditing his client, a publicly traded company, for the past five years. This year the client has experience a change in top management. Henry is not happy with the new desired timing of the audit report and the new fee arrangement, and he wants to resign as the auditor.(a) Explain what Henry must do to resign.(b) Are there any circumstances which he should report when he resigns?(c) Does Henry have an obligation to contact or communicate with the new auditor?(3 marks) Short Question 7The LMN Company has approximately 800 employees, including an accounting department with twenty people, of whom five work solely as internal auditors.Describe the major considerations the external auditor should evaluate before using the work done by the internal auditors.(3 marks) Short Question 8The RST Company Ltd. has been an audit client of your accounting firm for many years, and the firm enjoys a very good relationship with RST. Recently the management of RST has approached your accounting firm for a special one-off consulting engagement. This engagement would be to draw up a new accounting procedures manual and to train the lower-level staff of the RST accounting department. Both RST and the accounting firm intend to continue their relationship as client and auditor outside this prospective consulting engagement.Indicate the concerns that the accounting firm might have about accepting this special engagement.(3 marks) Short Question 9Susan is the manager in-charge of the audit for the Pactrans Company Ltd., which has its headquarters in Hong Kong but also has factories in various parts of Korea. It is customary for Susan's accounting firm to engage local accounting firms to perform certain audit procedures for the factories in Korea. Susan is in charge of planning and evaluating the work of the other auditors.List the issues Susan should consider in her audit planning and her evaluation of the use of audit work carried out by other auditors.(3 marks)Short Question 10Your audit client has operated a very effective manual accounting system since commencement of business many years ago. Recently the company has decided to automate its system in three phases. First it will automate the accounts payable and cash disbursements; shortly afterwards it will proceed with the automation of accounts receivable and cash receipts, and finally it will automate the payroll system. Your accounting firm has been notified that the implementation of automation will take place this year, and the client believes that by the end of the accounting period all three implementations will be completed and in operation.Indicate the advantages and disadvantages of a staged implementation of automation for both the client and for the audit firm.(3 marks)* * END OF SECTION A * *(QUESTIONS)* * *SECTION B:ESSAY STYLE QUESTIONS (Total: 20 marks)Essay QuestionJohn Chan, an audit manager of a medium sized audit firm, has had a meeting with Ms Greta Bo, who is the major shareholder and managing director of The Greta Group. Ms Bo does not want to reappoint the group's existing auditors and has asked John Chan whether his firm would like to submit a proposal for the Group's 1999 audit.The Greta Group is a private group which runs twenty retail jewellery shops. Five of these shops are in the Mainland of the People’s Republic of China and are audited by a local PRC audit firm. Ms Bo does not want to change the auditors of these five shops.The Greta Group had liquidity problems in 1998 and their auditors modified their audit report by stating that the validity of the going concern assumption was dependent on the Group's bankers not withdrawing their credit facilities. The bankers are reviewing and extending their short term loans to the Group on a quarterly basis. Ms Bo wants to provide audited financial statements to the bankers as soon as possible and therefore requires that the 1999 audit be completed three weeks after the year end. Ms Bo is willing to pay an audit fee of $200,000, which John Chan reckons to be on the low side.John Chan knows that Ms Bo is a good friend of the mother of Bruce Lee, the senior audit partner of his firm. John Chan therefore asks Bruce Lee to determine whether the firm should accept the audit engagement.Required:On behalf of John Chan, draft a memorandum to Bruce Lee, the senior audit partner. In the memorandum:(1) You should identify the factors specific to The Greta Group, which Bruce Lee shouldtake into account when considering whether to accept the audit engagement. Y oushould also set out any additional information related to the factors you have identified that Bruce Lee may need to consider in order to make his decision. Your discussion should include, but not be limited to, the ethical issues of changing auditors.(13 marks) (2) With regard to the low audit fees and tight deadline, you should set out the informationto be obtained and arrangements to be agreed with The Greta Group before accepting the engagement.(4 marks) Style and presentation : A maximum of 3 marks will be awarded to candidates for style and presentation of their answers.(3 marks)* * END OF SECTION B * *(QUESTIONS)* * *SECTION C:CASE STUDY (Total: 30 marks)TeleMobile Limited (“TML”) is a subsidiary of a well known international mobile phone manufacturer and it acts as the group’s distribution centre for the greater China region. Taking advantage of industry growth in the region, sales of the company increased significantly over the year. However, it is only marginally profitable due to the group transfer pricing policy under which only a small margin is earned by TML. In addition to the core business, TML also holds listed investments in Hong Kong and China as long term investment. The operation of TML is financed largely by its holding company. The balance sheet of TML as at 30 November 1999 is summarized as follows:-30 November 1999 31 December 1998HK$’000 HK$’000 Fixed Assets 355 420Listed Investment 4,680 4,680Current AssetsInventories 23,795 19,753Accounts receivable 10,950 11,2252,369Cash 1,54533,34736,290Current LiabilitiesDue to group companies 30,670 25,3953,002Other payables 3,25328,39733,923Net Current Asset 2,3674,95010,050Capital Employed 7,402Satisfied by:-Share Capital 5,000 5,0005,050Retained Profits 2,40210,0507,402You are the audit manager in-charge of TML for the year ending 31 December 1999. In addition to your role as statutory auditor for TML, you are also required to report to the auditors of the holding company of TML for group reporting purposes. The group reporting deadline is extremely tight and you are required to issue your opinion to the auditors of the holding company by 15 January 2000.In order to meet the tight reporting deadline your strategy is to perform audit procedures on the accounts for the period ended 30 November 1999 and perform limited additional work for the month of December 1999. From prior year audit experience, you know TML’s internal control system is sufficiently reliable to support this approach. Your team members have completed audit field work for the 30 November 1999 accounts and you have reviewed the work performed. There are a number of outstanding matters but you are satisfied that the file is ready for review by the partner-in-charge. You discuss the issues arising from the audit with the partner who is satisfied that these have been satisfactorily resolved and that the additional work for the remaining one month should be minimal.While waiting for clearance of the outstanding matters and performing additional work on theaccounts for the month of December 1999, including the work on the stocktake which is scheduled to take place on 31 December 1999 and 1 January 2000, certain matters came to your attention which may have an impact on the conclusions previously drawn.Required:Discuss in each of the following situations the audit response and additional work (if any). Where appropriate, indicate also whether and how the wording of the audit report may have to be changed. You should consider each of these situation independently.Case Study Question 1When reviewing the result of the stocktake, you are satisfied that all the test count items agreed with the inventory list prepared by management. However, you noticed that the staff conducting the stocktake did not examine or obtain a copy of the control sheet of count tags from management.(8 marks) Case Study Question 2A major competitor of TML has recently launched a new product on the market which forced TML to lower its selling price substantially to maintain its competitiveness. Approximately 90% of the inventories as at 31 December 1999 would be affected by this price war.(8 marks) Case Study Question 3When performing the preliminary analytical review of the December results, you noted a significant increase in gross margins from 5% to 8%. The reasons given to you for the sudden increase in margins is that the December results included certain adjustments to correct accounting errors in the previous months, including instances where cost of sales was double-counted.(8 marks) Case Study Question 4As at the year end date, the market value of the listed investments of TML were significantly lower than its carrying value. TML’s accounting policy on long term investment is to state the investments at cost less any permanent diminution in value, and management is satisfied that there is no permanent diminution in any of these listed investments. Management has confirmed in the letter of representation that they intend to hold the investment for long term purposes and the temporary fluctuations in market price of these investments does not have any effect on their long term prospect. After reviewing all the available evidence, you concur with management’s view and have issued an unqualified opinion for group reporting purposes.While you are performing a post balance sheet review prior to the sign-off of the statutory accounts in February 2000, you notice that TML has disposed of all the listed investments and incurred a significant loss. You discuss the matter with management immediately and are advised that the disposal was to meet the immediate cash need of the holding company and that it had not been planned in the annual cash flow forecast.(6 marks)* * END OF EXAM PAPER * *(QUESTONS)。
2021注册会计师笔记(六)

2021注册会计师笔记(六)第六章无形资产及其它资产一、无形资产的特征1、不具备实物形态:这就是主要标志2、不为货币性长期资产3、持有的目的是自用,而不是销售4、获利能力不确定5、有偿取得二、分类1、可辨认的:例如专利权、商标权、土地使用权、著作权、特许权、非专利技术2、不容辨识的:例如商誉(只有自制时才进账)三、账务处置1、购入:以实际支付的价款作为入账成本。
借:无形资产贷:银行存款******与电脑绑定购得的软件,金额相对较小时,一并扣除固定资产;很大时,单独列作无形资产。
如果购得的目的就是为了销售,就应当扣除存货了。
2、资金投入:以投资各方证实的价值进账******首次发行股票方式接受的,以投资方账面价值作为实际成本入账。
3、接受债务人非现金资产抵债:(看16章)4、非货币性交易换入:(看17章)5、受赠:(捐赠问题:2021新变化)①、捐献方提供更多了有关凭据的:凭据上标明的金额+有关税费筹钱:无形资产100+x贷:左弯资产价值100揽税金等x②、未提供更多有关凭据的a、存在活跃市场的:按市场价估计的金额+相关税费b、不存在活跃市场的:按预计未来现金流量的现值入账6、自行研发并按法律程序提出申请的,注册费、律师费进账。
研发费用轻易扣除当期损益。
7、购得的土地使用权,先作无形资产核算,该土地实际研发时再扣除新建工程******房地产企业:转至房地产开发成本8、时程开支:扣除当期费用四、摊销:自取得当月起开始(与固定资产不同),平均摊销1、合同规定受惠年限,法律没规定有效率年限的,折旧期≤合同规定的受惠年限2、合约没规定,但法律存有规定的,折旧期≤法律规定的有效率年限3、合约和法律同时存有规定的,折旧期≤受惠年限和有效率年限4、都没规定的,折旧期≤10年******尊循慎重性原则。
筹钱:管理费用一无形资产折旧贷款:无形资产应交税金一应交营业税五、处置1、出售:将税金价款与账面价值的差额,扣除当期营业外收支。
《202x年注册会计师全国统一考试一本通:审计》读书笔记模板

考点精讲 历年真题 历年真题答案及解析 全真模拟试题 全真模拟试题答案及解析
考点精讲 历年真题 历年真题答案及解析 全真模拟试题 全真模拟试题答案及解析
考点精讲 历年真题 历年真题答案及解析 全真模拟试题 全真模拟试题答案及解析
考点精讲 历年真题 历年真题答案及解析 全真模拟试题 全真模拟试题答案及解析
考点精讲 历年真题 历年真题答案及解析 全真模拟试题 全真模拟试题答案及解析
考点精讲 历年真题 历年真题答案及解析 全真模拟试题 全真模拟试题答案及解析
考点精讲 历年真题 历年真题答案及解析 全真模拟试题 全真模拟试题答案及解析
考点精讲 全真模拟试题 全真模拟试题答案及解析
考点精讲 历年真题 历年真题答案及解析 全真模拟试题 全真模拟试题答案及解析
考点精讲 历年真题 历年真题答案及解析 全真模拟试题 全真模拟试题答案及解析
考点精讲 历年真题 历年真题答案及解析 全真模拟试题 全真模拟试题答案及解析
考点精讲 历年真题 历年真题答案及解析 全真模拟试题 全真模拟试题答案及解析
考点精讲 历年真题 历年真题答案及解析 全真模拟试题 全真模拟试题答案及解析
考点精讲 历年真题 历年真题答案及解析 全真模拟试题 全真模拟试题答案及解析
考点精讲 历年真题 历年真题答案及解析 全真模拟试题 全真模拟试题答案及解析
考点精讲 历年真题 历年真题答案及解析 全真模拟试题 全真模拟试题答案及解析
考点精讲 历年真题 历年真题答案及解析 全真模拟试题 全真模拟试题答案及解析
谢谢观看
读书笔记
这是《202x年注册会计师全国统一考试一本通:审计》的读书笔记模板,可以替换为自己的心得。
精彩摘录
这是《202x年注册会计师全国统一考试一本通:审计》的读书笔记模板,可以替换为自己的精彩内容摘录。
指出要点!香港公司会计审计知识

第一点:在甚麽情况下,香港公司可获豁免利得税?
如果一家企业的收入不是来自香港,而该公司不在香港设立办事处和招聘香港员工,则该公司所赚取的利润可获豁免利得税,但你须向香港税务局申请离岸所得税豁免。
知识点2:该公司只在中国境内的外国银行开立账户,不在香港开设账户。
那么,该公司所做的业务是否不受香港纳税申报表的约束?
否。
根据香港法例,所有香港公司均须向香港税务局申报其财务状况,不论其业务是否在香港经营。
如企业的收入并非来自香港,可向税务局申请免税。
知识第三点:香港公司需要哪些文件进行审计?
1.有关期间/年的银行月结单及存折;
2.销售/收入分配。
机票(并提供客户名称及位址);
3.购货/分订单交货。
票证(提供供应商名称及地址);
4.支出文件;
5.结算日的存货报表(需要董事盖章及签署);
6.主要资产在合同中出售和出售(物业、汽车、机器、子公司等等);
7.租赁;
8.职员的详细资料(姓名、身份证号码及地址);
9.贷款合同和缴款报表;
10.去年的核数师报告、最近的年报、公司登记证、商业登记证及公司大纲及公司章程。
(推荐下载)2020年注册会计师(CPA)考试笔记精华版-审计

2020年注册会计师考试学习笔记审计目录专题一审计概述 (3)专题二审计计划 (9)专题三审计证据 (16)专题四审计抽样 (22)专题五信息技术对审计的影响 (31)专题六审计工作底稿 (35)专题七风险评估 (38)专题八风险应对 (42)专题九销售与收款循环的审计 (48)专题十采购与付款循环的审计 (53)专题十一生产与存货循环的审计 (55)专题十二货币资金的审计 (58)专题十三对舞弊和法律法规的考虑 (60)专题十四审计沟通 (66)专题十五注册会计师利用他人工作 (71)专题十六对集团财务报表审计的特殊考虑 (76)专题十七其他特殊项目的审计 (79)专题十八完成审计工作 (87)专题十九审计报告 (90)专题二十企业内部控制审计 (99)专题二十一会计师事务所业务质量控制 (110)专题二十二职业道德基本原则和概念框架 (113)专题二十三审计业务对独立性的要求 (115)专题一审计概述●【考情分析】非常重要的内容,主要考核客观题和综合题,分值较高。
●【重磅考点提示】1.审计的产生;2.审计的定义;3.保证程度;4.注册会计师审计和政府审计;5.职业责任和期望差距;6.审计报告和信息差距;7.审计要素;8.审计目标(重点关注认定与具体目标);9.审计基本要求(重点关注职业怀疑和职业判断);10.审计风险。
【重磅考点】审计的产生注册会计师制度存在和发展应归结于企业所有权和经营权的分离,特别是股份有限公司的出现。
【重磅考点】审计的定义财务报表审计是指注册会计师对财务报表是否不存在重大错报提供合理保证,以积极方式提出意见,增强除管理层之外的预期使用者对财务报表信赖的程度。
1.审计的用户是财务报表预期使用者。
2.审计的目的是改善财务报表的质量或内涵,增强预期使用者对财务报表信赖的程度,即以合理保证的方式提高财务报表的质量,而不涉及为如何利用信息提供建议。
3.合理保证是一种高水平保证,审计不能提供绝对保证。
注会审计笔记(大神超详细版)
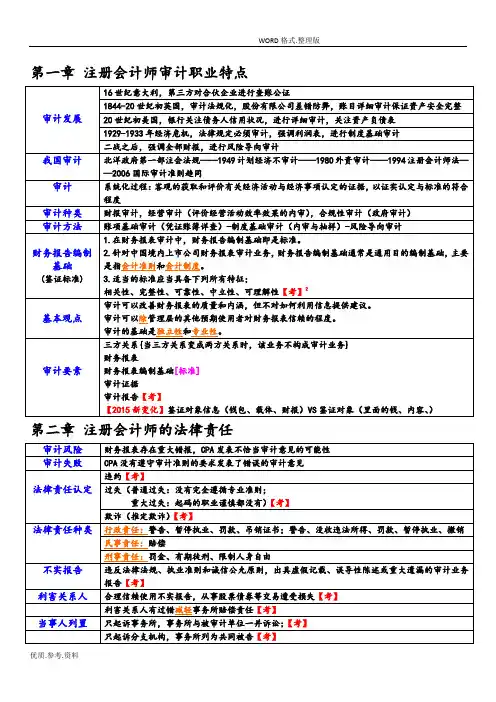
第一章注册会计师审计职业特点审计发展16世纪意大利,第三方对合伙企业进行查账公证1844-20世纪初英国,审计法规化,股份有限公司差错防弊,账目详细审计保证资产安全完整20世纪初美国,银行关注债务人信用状况,进行详细审计,关注资产负债表1929-1933年经济危机,法律规定必须审计,强调利润表,进行制度基础审计二战之后,强调全部财报,进行风险导向审计我国审计北洋政府第一部注会法规——1949计划经济不审计——1980外资审计——1994注册会计师法——2006国际审计准则趋同审计系统化过程:客观的获取和评价有关经济活动与经济事项认定的证据,以证实认定与标准的符合程度审计种类财报审计,经营审计(评价经营活动效率效果的内审),合规性审计(政府审计)审计方法账项基础审计(凭证账簿详查)-制度基础审计(内审与抽样)-风险导向审计财务报告编制基础(鉴证标准)1.在财务报表审计中,财务报告编制基础即是标准。
2.针对中国境内上市公司财务报表审计业务,财务报告编制基础通常是通用目的编制基础,主要是指会计准则和会计制度。
3.适当的标准应当具备下列所有特征;相关性、完整性、可靠性、中立性、可理解性【考】2基本观点审计可以改善财务报表的质量和内涵,但不对如何利用信息提供建议。
审计可以除管理层的其他预期使用者对财务报表信赖的程度。
审计的基础是独立性和专业性。
审计要素三方关系{当三方关系变成两方关系时,该业务不构成审计业务}财务报表财务报表编制基础[标准]审计证据审计报告【考】【2015新变化】鉴证对象信息(钱包、载体、财报)VS鉴证对象(里面的钱、内容、)第二章注册会计师的法律责任审计风险财务报表存在重大错报,CPA发表不恰当审计意见的可能性审计失败CPA没有遵守审计准则的要求发表了错误的审计意见法律责任认定违约【考】过失(普通过失:没有完全遵循专业准则;重大过失:起码的职业谨慎都没有)【考】欺诈(推定欺诈)【考】法律责任种类行政责任:警告、暂停执业、罚款、吊销证书;警告、没收违法所得、罚款、暂停执业、撤销民事责任:赔偿刑事责任:罚金、有期徒刑、限制人身自由不实报告违反法律法规、执业准则和诚信公允原则,出具虚假记载、误导性陈述或重大遗漏的审计业务报告【考】利害关系人合理信赖使用不实报告,从事股票债券等交易遭受损失【考】利害关系人有过错减轻事务所赔偿责任【考】当事人列置只起诉事务所,事务所与被审计单位一并诉讼;【考】只起诉分支机构,事务所列为共同被告【考】被审计单位出资人抽逃出资,列为第三人参加诉讼【考】过错推定原则与举证责任倒置事务所出具不实报告给利害关系人带来损失的,应当承担侵权赔偿责任,能证明自己没有过错的除外【考】连带责任故意(恶意串通,明知……不予指明或做不实报告或不予拒绝)【考】补充责任过失(被审计单位、出资人财产之后的补充赔偿)普通过失低于一般专业水平执业、审计计划明显疏漏、缺必要审计程序、发现舞弊未追加必要程序、重要性原则不合理、审计证据不充分、未征求专家意见、错误判断评价审计证据免责遵守准则规则保持必要职业谨慎,未能发现被审计单位会计资料错误【考】2仅供年检使用不能免责必须依赖金融机构单位提供的虚假或不实的证明文件,必要职业谨慎未发现虚假不实【考】2已对舞弊提出警告并在报告中指明【考】被审验单位注册登记后抽逃出资【考】为出资人出具不实报告,后已补足出资【考】减责利害关系人明知不实报告仍使用【考】赔偿顺位只有补充责任时有顺位:事务所在后顺位【考】赔偿责任范围连带责任:无上限补充责任:不实报告金额为上限【考】分支机构与事务所作为共同被告,双方连带责任未经审判事务所不能被擅自追加为被执行人第三章职业道德基本原则和概念框架基本原则诚信、独立性、客观公正、专业胜任能力和应有的关注、保密、良好的职业行为。
香港注册会计师考师审计笔记试卷考生答
QP Examination Panelists’ Comments(September 1999 Session)Module CI. General CommentsThis was the first examination under the Qualification Programme, which tested thecandidates under a new type of examination. The examination introduced three new elements for the candidates to deal with (a) application and integration of knowledgerather than straight citing of facts or definitions; (b) the open-book format; and (c) apaper split into three sections with all questions compulsory. There are somegeneralisations which can be made from this paper:●The application of knowledge was not clearly demonstrated in many instances.Frequently, candidates appeared not to read or understand the questions. Mostcandidates threw in whatever they knew about the subject matter without regard tothe questions asked.●It appeared that time management was an issue, as many candidates made littleeffort on the case study, although it was a significant percentage of available marks.It should be emphasised to the candidates to approach the questions in a fashionthat considers the potential marks versus the time spent on answering the question.Several candidates spent too much time, and went into too great detail on the shortquestion portion of the examination, to the detriment of their performance on thecase study.●In a similar fashion, it appears that the candidates placed over-reliance on theresources allowed in this open-book format exam. Some candidates wereundoubtedly overly optimistic about their abilities to search for answers from thestudy materials they had brought with them.●There was a widespread tendency to copy verbatim from resource materials in theanswers. This relates to the above point about candidates copying from referencematerials relating to a question without first attempting to isolate what issues thequestion was actually addressing.II. Specific Commentsa. Section A – Short QuestionsOne common failing was to spend too much time and write too lengthy an answerto the short questions. Many, or most, of the short questions could be accuratelyanswered by a well-prepared candidate without resorting to looking upinformation from books or other materials.It is important for the candidate to answer only the question asked, rather thanprovide extraneous information which relates to the topic, but was not required.b. Section B – EssayThe essay question again suffered from candidates not paying attention to thedetails of the question asked. For example, one basic component of the essayquestion was that the response be framed in the style of a memorandum to anaudit partner. Many candidates correctly saw this requirement and adapted theirresponse to it, thereby earning marks. But some candidates did not.In the essay, candidates also appeared to lose focus on the questions asked, andwere prone to copying information directly from their materials into their responseswithout any commentary on how this information related to theirresponse. Indeed, the copied information often did not relate to the question at all.c. Section C - CaseThe case study was in most cases the section where candidates earned least marks.Reasonable speculation would be that this is a result of the students not havingenough time to complete this section of the examination.The case study questions were reasonably set and it was appreciated that thecandidates having no working experience would find them extremely difficult.Again, candidates frequently wrote about what they knew rather than what thecase study asked.III.Conclusion and RecommendationsThe conclusion about this examination is that it was certainly a difficult type ofendeavour for the candidates. This is probably due to the fact that it is an entirelynew type of examination, and no history exists on past efforts which can bescrutinized by the students.A strong recommendation to future candidates would be to read the questioncompletely and ensure that they understand what is required before answering.Recommendation for future examinations would be to be much more attentive toresponding to the questions which are asked, rather than attempting to provide ablanket of knowledge about an entire area. One possible strategy would be to read the entire examination paper carefully during the reading time given beforeattempting to answer any portion of it.Another area that could result in improvement would be to better manage exam time.To this end, it is recommended that candidates consider whether the use of time tosearch information in their materials is warranted.It would be helpful for the candidates to consider the mark value for each questionversus the amount of time that they spend on writing their response.Candidates are advised to choose the order in which they answer questions carefully.Don’t leave case to the last moment.An overall recommendation would be for the students to sit a mock examinationpaper based on a previous paper or the pilot paper provided in the course materials.This effort would be valuable to assess the appropriateness of how they divide theirtime among the three sections.。
注会审计笔记(大神超详细的版)
第一章注册会计师审计职业特点审计发展16世纪意大利,第三方对合伙企业进行查账公证1844-20世纪初英国,审计法规化,股份有限公司差错防弊,账目详细审计保证资产安全完整20世纪初美国,银行关注债务人信用状况,进行详细审计,关注资产负债表1929-1933年经济危机,法律规定必须审计,强调利润表,进行制度基础审计二战之后,强调全部财报,进行风险导向审计我国审计北洋政府第一部注会法规——1949计划经济不审计——1980外资审计——1994注册会计师法——2006国际审计准则趋同审计系统化过程:客观的获取和评价有关经济活动与经济事项认定的证据,以证实认定与标准的符合程度审计种类财报审计,经营审计(评价经营活动效率效果的内审),合规性审计(政府审计)审计方法账项基础审计(凭证账簿详查)-制度基础审计(内审与抽样)-风险导向审计财务报告编制基础(鉴证标准)1.在财务报表审计中,财务报告编制基础即是标准。
2.针对中国境内上市公司财务报表审计业务,财务报告编制基础通常是通用目的编制基础,主要是指会计准则和会计制度。
3.适当的标准应当具备下列所有特征;相关性、完整性、可靠性、中立性、可理解性【考】2基本观点审计可以改善财务报表的质量和内涵,但不对如何利用信息提供建议。
审计可以除管理层的其他预期使用者对财务报表信赖的程度。
审计的基础是独立性和专业性。
审计要素三方关系{当三方关系变成两方关系时,该业务不构成审计业务}财务报表财务报表编制基础[标准]审计证据审计报告【考】【2015新变化】鉴证对象信息(钱包、载体、财报)VS鉴证对象(里面的钱、内容、)第二章注册会计师的法律责任审计风险财务报表存在重大错报,CPA发表不恰当审计意见的可能性审计失败CPA没有遵守审计准则的要求发表了错误的审计意见法律责任认定违约【考】过失(普通过失:没有完全遵循专业准则;重大过失:起码的职业谨慎都没有)【考】欺诈(推定欺诈)【考】法律责任种类行政责任:警告、暂停执业、罚款、吊销证书;警告、没收违法所得、罚款、暂停执业、撤销民事责任:赔偿刑事责任:罚金、有期徒刑、限制人身自由不实报告违反法律法规、执业准则和诚信公允原则,出具虚假记载、误导性陈述或重大遗漏的审计业务报告【考】利害关系人合理信赖使用不实报告,从事股票债券等交易遭受损失【考】利害关系人有过错减轻事务所赔偿责任【考】当事人列置只起诉事务所,事务所与被审计单位一并诉讼;【考】只起诉分支机构,事务所列为共同被告【考】被审计单位出资人抽逃出资,列为第三人参加诉讼【考】过错推定原则与举证责任倒置事务所出具不实报告给利害关系人带来损失的,应当承担侵权赔偿责任,能证明自己没有过错的除外【考】连带责任故意(恶意串通,明知……不予指明或做不实报告或不予拒绝)【考】补充责任过失(被审计单位、出资人财产之后的补充赔偿)普通过失低于一般专业水平执业、审计计划明显疏漏、缺必要审计程序、发现舞弊未追加必要程序、重要性原则不合理、审计证据不充分、未征求专家意见、错误判断评价审计证据免责遵守准则规则保持必要职业谨慎,未能发现被审计单位会计资料错误【考】2仅供年检使用不能免责必须依赖金融机构单位提供的虚假或不实的证明文件,必要职业谨慎未发现虚假不实【考】2已对舞弊提出警告并在报告中指明【考】被审验单位注册登记后抽逃出资【考】为出资人出具不实报告,后已补足出资【考】减责利害关系人明知不实报告仍使用【考】赔偿顺位只有补充责任时有顺位:事务所在后顺位【考】赔偿责任范围连带责任:无上限补充责任:不实报告金额为上限【考】分支机构与事务所作为共同被告,双方连带责任未经审判事务所不能被擅自追加为被执行人第三章职业道德基本原则和概念框架基本原则诚信、独立性、客观公正、专业胜任能力和应有的关注、保密、良好的职业行为。
注会审计笔记(大神超详细版)
(具体业务层面)
复核非鉴证业务、复核鉴证业务、向有关机构咨询、与治理层讨论职业道德问题、收费范围、其他所重新执行、轮换合伙人和高级员工。
首次承接业务
考虑股东高管治理层的诚信问题,
在接受关系前确定是否对职业道德基本原则产生不利影响。
防范:
了解客户的股东、高管、治理层、负责经营人员;
要求客户对治理结构和内控的承诺。
第一章 注册会计师审计职业特点
审计发展
16世纪意大利,第三方对合伙企业进行查账公证
1844-20世纪初英国,审计法规化,股份有限公司差错防弊,账目详细审计保证资产安全完整
20世纪初美国,银行关注债务人信用状况,进行详细审计,关注资产负债表
1929-1933年经济危机,法律规定必须审计,强调利润表,进行制度基础审计
相关性、完整性、可靠性、中立性、可理解性【考】2
基本观点
审计可以改善财务报表的质量和内涵,但不对如何利用信息提供建议。
审计可以除管理层的其他预期使用者对财务报表信赖的程度。
审计的基础是独立性和专业性。
审计要素
三方关系{当三方关系变成两方关系时,该业务不构成审计业务}
财务报表
财务报表编制基础[标准]
审计证据
仅供年检使用不能免责
必须依赖金融机构单位提供的虚假或不实的证明文件,必要职业谨慎未发现虚假不实【考】2
已对舞弊提出警告并在报告中指明【考】
被审验单位注册登记后抽逃出资【考】
为出资人出具不实报告,后已补足出资【考】
减责
利害关系人明知不实报告仍使用【考】
赔偿顺位
只有补充责任时有顺位:事务所在后顺位【考】
(所、组、主亲)与(客户、董高)在同一股东有限实体有利益{如合伙关系}
注册会计师考试(综合阶段)知识点总结——审计.
认定程序营业收入(“发生”认定,9个程序)(1)对营业收入实施实质性分析程序,对有异常情况的项目做进一步调查:①按收入分类或产品名称对销售数量、毛利率等进行比较分析;②按月度对本期和上期毛利率进行比较分析。
(2)结合在了解被审计单位及其环境时获取的信息,检查主营业收入的确认条件、方法是否符合企业会计准则的规定并保持前后期一致;关注周期性、偶然性的收入是否符合既定的收入确认原则、方法。
(3)抽取本期一定数量的记账凭证,审查入账日期、品名、数量、单价、金额等是否与销售发票、出库单、销售合同等一致。
(4)结合对应收账款的审计,选择主要客户函证本期销售额。
(5)存在销货退回的,检查手续是否符合规定,结合原始销售凭证检查其会计处理是否正确。
结合存货项目审计关注其真实性。
(6)对于出口销售,应当将销售记录与出口报关单、货运提单、销售发票等出口销售单据进行核对,必要时向海关函证。
(7)检查有无特殊的销售行为。
(8)调查向关联方的销售情况。
(9)调查集团内部的销售情况。
营业收入(“截止”认定,4个程序)(1)结合在了解被审计单位及其环境时获取的信息,检查主营业收入的确认条件、方法是否符合企业会计准则的规定并保持前后期一致;关注周期性、偶然性的收入是否符合既定的收入确认原则、方法。
(2)抽取本期一定数量的记账凭证,审查入账日期、品名、数量、单价、金额等是否与销售发票、出库单、销售合同等一致。
(3)销售的截止测试①选取资产负债表日前后若干天且大于一定金额的发货单据,与应收账款和收入明细账进行核对;同时,从应收账款和收入明细账选取在资产负债表日前后若干天且大于一定金额的凭证,与发货单据核对,以确定销售是否存在跨期现象。
②复核资产负债表日前后销售和发货水平,确定业务活动水平是否异常,并考虑是否有必要追加截止测试程序。
③取得资产负债表日后所有的销售退回记录,检查是否存在提前确认收入的情况。
④结合对资产负债表日应收账款的函证程序,检查有无未取得对方认可的大额销售。