
公司内部控制管理手册参考文献
XXXX有限公司内部控制管理手册2014年8月目录第一章总则第一条概述第二条内部控制手册适用范围第三条内部控制目标第四条内部控制原则第二章内部控制组织架构及职责权限第五条内部控制组织架构第六条内部控制组织机构及职责第三章内部控制整体框架和流程控制第七条内部控制整体框架的五要素第八条流程控制要点第九条流程控制关键控制点第四章内部控制评估工作程序第十条内部控制要素第十一条评估范围的设定第十二条内部控制设计有效性评估第十三条内部控制运行有效性评估第十四条内部控制缺陷评价及整改跟进第十五条内部控制描述方法第十六条内部控制测试方法第十七条内部控制流程文档签署确认第十八条出具内部控制评估报告第十九条内部控制流程文档的更新第五章内部控制管理考核与激励第二十条内部控制管理考核责任主体第二十一条内部控制管理考核原则第二十二条内部控制管理考核方法第六章附则第二十三条内部控制手册维护第二十四条解释与生效第一章总则第一条概述为了加强和规范XXXX有限公司(以下简称“集团公司”)的内部控制,进一步提高集团公司经营管理水平和风险防范能力,促进集团公司实现总体发展战略目标,根据中华人民共和国财政部等五部委颁布的《企业内部控制基本规范》(以下简称《基本规范》)与相关配套指引的要求,并结合集团公司的实际情况,制定本管理手册。
第二条内部控制管理手册适用范围(一)本管理手册是集团建设并实施内部控制体系的纲领性文件,集团公司及其独资、控股、托管企业、事业部和直属单位(以下简称投资企业)要认真组织实施,严格遵照执行。
集团公司参股企业可参照执行。
(二)集团公司各职能部门和各投资企业要充分认识内部控制体系建设工作的长期性和艰巨性,把建立和有效运行内部控制体系作为本部门/企业的重要工作,建立长效机制,指定专职管理岗位或专职管理部门,履行内部控制职能,切实做到实施有力。
(三)集团公司各职能部门和各投资企业要按照本管理手册编制规范(见附件1)的要求,制定、完善和细化本部门/企业的内部控制实施细则。
第三条内部控制目标根据《基本规范》要求,内部控制的目标是合理保证企业经营管理合法合规、资产安全、财务报告及相关信息真实完整,提高经营效率和效果,促进企业实现发展战略。
要完成如下目标:(一)合理确保财务报告及相关信息真实完整,确保集团公司上下从思想上、认识上对财务报告相关内部控制保持高度统一,并进一步实现行为上的统一。
(二)建立一套内容涵盖集团公司经营管理各个领域的内部控制机制,确保集团公司各项工作统一、规范、有序运行,最大限度地减少或规避风险,保证集团公司协调、持续、快速发展,促进集团公司实现发展战略。
(三)促进集团公司完善和规范管理行为,保证资产的安全、完整及会计资料的真实、准确,以进一步提高集团公司的经营管理水平和经营效率。
(四)建立一套科学、系统的内部控制体系建设方法和规范,为集团公司内部控制体系建设、运行和评价提供指引,并作为建立、执行、评价及验证内部控制的依据。
以建立统一、规范、有效运行的内部控制体系,进一步完善和优化集团公司的内部控制,增强集团公司的风险防范能力。
第四条内部控制原则集团公司开展内部控制体系建设工作应遵循以下工作原则:(一)全面性原则:内部控制应当贯穿决策、执行和监督全过程,覆盖集团公司及其投资企业的各种业务和事项。
(二)重要性原则:内部控制应当在全面控制的基础上,关注重要业务事项和高风险领域。
(三)制衡性原则:内部控制应当在治理结构、机构设臵及权责分配、业务流程等方面形成相互制约、相互监督,同时兼顾运营效率。
(四)适应性原则:内部控制应当与集团公司经营规模、业务范围、竞争状况和风险水平等相适应,并随着情况的变化及时加以调整。
(五)成本效益原则:内部控制应当权衡实施成本与预期效益,以适当的成本实现有效控制。
第二章内部控制组织架构及职责权限第五条内部控制组织架构(一)集团公司内部控制是由董事会、监事会、管理层和全体员工实施的、旨在实现控制目标的过程。
因此,内部控制体系建设工作不仅是集团公司管理层的责任,而且是集团公司上下全体员工都需要参与的一项工作。
(二)集团公司内部控制体系工作,在董事会领导下形成决策、管理、执行、监督四个层次的管理架构。
第六条内部控制组织机构及职责(一)董事会董事会是内部控制的决策机构,负责内部控制的建立健全和有效实施,具体职责包括:1.审批内控体系建设组织机构设臵方案。
2.审批内控体系建设的有关发展规划、工作方案等。
3.审批内部控制管理手册等内控体系建设成果文件。
4.审批内部控制评价报告。
5.决定其他重大事项。
董事会下设审计委员会,具体职责包括:1.指导公司内部控制机制建设。
2.监督内部控制的有效实施和内部控制自我评价情况。
3.协调内部控制审计。
4.董事会授予的其他权限等。
(二)监事会监事会是内部控制的监督机构,负责对同级董事会建立与实施内部控制进行监督。
(三)管理层管理层是内部控制体系建设和实施的直接领导和执行机构,包括领导机构和工作机构两个层面,具体组成及职责如下:1.内控建设工作领导小组(1)组成组长:集团公司总经理副组长:分管集团公司计划财务部、规划发展部、资产运营部和纪检监察部的集团公司领导成员:集团公司各职能部门负责人(2)具体职责①组织领导内控体系建设工作。
②审核内控体系建设的有关发展规划、工作方案等。
③审核内部控制管理手册、内控流程文件汇编、权限指引等内控体系建设成果文件。
④审核内部控制评价报告。
⑤协调处理内控体系建设中的其他重大事项。
2.内控建设工作小组(1)组成组长:纪检监察部负责人副组长:计划财务部、资产运营部、规划发展部、人力资源部、党群工作部负责人成员:集团公司各职能部门相关人员内控建设工作小组的办事机构设在纪检监察部(风控室)。
(2)具体职责①拟订内控体系建设的有关发展规划、工作方案等。
②组织开展内控体系建设的相关培训。
③编制内控体系建设相关文件的模板。
④审查内控体系建设的有关成果文件。
⑤督促、指导各部门、各投资企业相关工作。
⑥通报内控体系建设工作进展情况。
⑦办理内控体系建设的其他事项。
(四)评价部门集团公司纪检监察部(审计室)是内部控制体系的评价部门,负责组织评价工作,其具体职责包括:1.组织制定内部控制评价制度。
2.拟订内部控制评价工作方案。
3.组织各职能部门与各投资企业内部控制自我评价和测试工作。
4.对于评价过程中发现的重大问题,及时与相关管理层沟通,认定内部控制缺陷,拟定整改方案,并对整改情况出具审核意见。
5.汇总内部控制自我评价底稿和报告、内部控制工作小组测试评价工作底稿和评价报告。
6.编制内部控制评价报告,及时向董事会(审计委员会)或管理层报告。
7.督促落实内部控制缺陷整改。
8.负责内部控制评价相关记录或者资料的归档工作。
9.办理内部控制评价相关的其他事项。
(五)各职能部门和各投资企业各职能部门和各投资企业是内部控制的执行主体。
各职能部门和各投资企业应设立内控建设工作领导小组和内控建设职能岗位/部门/,负责本部门(相关业务领域)和本企业的内控体系建设与实施工作,其具体职责包括:1.收集、整理、统计、分析其职能或业务领域内的各类与风险和内部控制相关的风险信息,进行风险评估,研究风险应对策略,编制风险数据库。
2.梳理业务流程,设臵风险控制点,明确关键控制措施,按照模板编制流程文件(内控实施细则)。
3.对业务流程的实际操作进行日常控制监测,以公司内控目标为准则,识别偏离目标的原因或现行体系与其环境适应性方面的差距,找出改进的机会,制定行动方案付诸实施。
4.对照内控相关规范、指引,制订、修订本部门/企业职责范围内的规章制度。
5.对认定的内部控制缺陷,拟定整改方案。
6.配合公司内部控制与风险评估每年至少一次的检查与测试工作。
7.组织本部门(相关业务领域)/企业员工学习内控知识和相关的法律法规等要求,必要时将相关要求转化到管理文件中。
8.梳理部门(相关业务领域)/企业岗位的职责权限,编制岗位说明书。
9.组织本部门(相关业务领域)/企业的内部控制自我评价工作。
10.与本部门(相关业务领域)/企业有关的内控体系建设的其他工作。
第三章内部控制的整体框架和流程控制第七条内部控制整体框架的五要素按照《基本规范》及相关配套指引中的要求,并结合国际公认的COSO内部控制评估整合框架,集团公司内部控制的整体框架包含以下五大要素:(一)内部环境——是集团公司实施内部控制的基础,一般包括治理结构、机构设臵及权责分配、内部审计、人力资源政策、企业文化等。
(二)风险评价——是集团公司及时识别、系统分析经营活动与实现内部控制目标相关的风险,合理确定风险应对策略。
(三)控制活动——是集团公司根据风险评价结果,采用相应的控制措施,将风险控制在可承受度之内。
(四)信息与沟通——是集团公司及时、准确地收集、传递与内部控制相关的信息,确保信息在集团内部、集团与外部之间进行有效沟通。
(五)内部监督——是集团公司对内部控制建立与实施情况进行监督检查,评价内部控制的有效性,发现内部控制缺陷,应当及时加以改进。
第八条流程控制要点流程控制主要是指对业务流程及关键控制点的风险描述、操作程序描述以及控制活动。
集团公司各职能部门和各投资企业要按照《企业内部控制应用指引第1号——组织架构》等18项应用指引的具体规定开展内部控制建设和实施工作。
重点要把握业务流程及关键控制点的控制活动的几个要点:(一)不相容职务分离控制。
通过岗位职责分工,在业务流程中涉及到的授权、签发、核准、执行和记录等五个步骤中,确保每一步都有相对独立的人员或部门分别实施或执行。
(二)授权审批。
业务活动的权限,根据不同的业务性质,不同的岗位以及业务活动的重要性程度,按不同层次进行审批。
(三)记录的完整性。
对控制活动中的行为要进行记录,确保原始材料真实可查。
(四)监督和改进。
要定期和不定期对各业务流程和关键控制点进行梳理和监督检查,对存在的缺陷进行调整和改进。
第九条流程控制关键控制点以《基本规范》五要素为指引,按照《企业内部控制应用指引》,参照国内大中型企业内部控制的做法,集团公司确定了基本的业务流程及关键控制点,集团公司各职能部门和各投资企业要围绕(但不限于)此业务流程及关键控制点,建立本部门/企业的内部控制实施细则。
流程控制关键控制点及责任部门第四章内部控制评估工作程序第十条内部控制要素集团公司内部控制是由集团公司董事会、监事会、管理层、全体员工实施的、旨在实现控制目标的过程,其包括每个重要及子流程的交易发起、审批授权、记录、处理和报告的过程。
集团公司的内部控制要素包括:(一)发起——因一项交易的发生而产生的应承担的权力或义务、增加的资产或负债,即交易记录的起点。
(二)审批授权——在交易执行或记录之前,有独立的审批授权,对业务的执行进行授权批准。
内部控制参考文献15个

内部控制参考文献15个以下是 15 个关于内部控制的参考文献:1. Chen, Y., & Wang, Y. (2018). Internal control in Chinese corporate environments: A literature review. Journal of International Accounting Studies, 44(3), 327-346.2. Dong, H., & Zhou, X. (2017). The role of internal control in corporate financial reporting: An empirical study. Journal of Business Research, 61(6), 869-876.3. Gao, J. (2016). Internal control and corporate governance: A review of empirical research. Journal of Business Research, 60(1), 133-143.4. Guo, L., & Zhang, Y. (2019). The impact of internal control on financial performance: An empirical study of Chinese listed companies. International Journal of Economics, Commerce and Management, 2(3), 12-22.5. Hu, S., & Yang, Y. (2018). The role of internal control in improving corporate governance: An empirical study in China. Journal of Business Research, 62(5), 764-772.6. Jiang, H., & Liu, H. (2018). The impact of internal control on financial performance: A literature review. Journal of International Accounting Studies, 44(3), 309-325.7. Li, M., & Zhou, X. (2017). The relationship betweeninternal control and corporate governance: A review of international empirical research. Journal of Business Research, 60(7), 964-973.8. Li, Y., & Zhang, Y. (2019). The impact of internal control on firm value: An empirical study of Chinese listed companies. International Journal of Economics, Commerce and Management, 2(4), 1-10.9. Lu, D., & Zhou, X. (2016). The impact of internal control on corporate financial reporting: An empirical study. Journal of Business Research, 60(4), 584-592.10. Wang, H., & Zhang, Y. (2018). Internal control and corporate governance: A systematic literature review. Journal of International Accounting Studies, 44(3), 291-307.11. Zhang, Y., & Guo, L. (2019). The impact of internal control on corporate governance: An empirical study of Chinese small and medium-sized enterprises. International Journal of Economics, Commerce and Management, 2(2), 5-15.12. Zhang, Y., & Wang, Y. (2017). The impact of internal control on financial performance: An empirical study of Chinese listed companies. Journal of Business Research, 60(9),1098-1106.13. Zhao, Y., & Zhou, X. (2018). The relationship betweeninternal control and financial performance: An empirical study of Chinese private firms. Journal of International Accounting Studies, 44(3), 275-290.14. Zhu, M., & Zhou, X. (2017). The impact of internal control on corporate financial reporting: An empirical study of Chinese non-state-owned enterprises. Journal of Business Research, 61(4), 644-652.15. Zhang, X., & Zhou, X. (2019). The impact of internal control on financial performance: A systematic literature review of Chinese non-state-owned enterprises. International Journal of Economics, Commerce and Management, 2(1), 11-22.。
公司内控手册

资料范本本资料为word版本,可以直接编辑和打印,感谢您的下载公司内控手册地点:__________________时间:__________________说明:本资料适用于约定双方经过谈判,协商而共同承认,共同遵守的责任与义务,仅供参考,文档可直接下载或修改,不需要的部分可直接删除,使用时请详细阅读内容目录TOC \o "1-3" \h \z \u HYPERLINK \l "_Toc386984448" 第一部分:总论 PAGEREF _Toc386984448 \h 3HYPERLINK \l "_Toc386984449" 一、目的、意义及原则 PAGEREF _Toc386984449 \h 3HYPERLINK \l "_Toc386984450" 二、编制依据 PAGEREF_Toc386984450 \h 3HYPERLINK \l "_Toc386984451" 三、使用范围 PAGEREF_Toc386984451 \h 3HYPERLINK \l "_Toc386984452" 四、使用指南 PAGEREF_Toc386984452 \h 3HYPERLINK \l "_Toc386984453" 五、维护及更新 PAGEREF_Toc386984453 \h 4HYPERLINK \l "_Toc386984454" 第二部分:内部环境 PAGEREF _Toc386984454 \h 5HYPERLINK \l "_Toc386984455" 一、组织框架 PAGEREF_Toc386984455 \h 5HYPERLINK \l "_Toc386984456" 二、人力资源 PAGEREF_Toc386984456 \h 7HYPERLINK \l "_Toc386984457" 三、企业文化及社会责任 PAGEREF _Toc386984457 \h 7HYPERLINK \l "_Toc386984458" 第三部分:风险评估与控制活动PAGEREF _Toc386984458 \h 9HYPERLINK \l "_Toc386984459" 一、风险类别 PAGEREF_Toc386984459 \h 9HYPERLINK \l "_Toc386984460" 二、风险评估 PAGEREF_Toc386984460 \h 9HYPERLINK \l "_Toc386984461" 三、风险应对与控制的措施PAGEREF _Toc386984461 \h 10HYPERLINK \l "_Toc386984462" (一)外部风险应对措施 PAGEREF _Toc386984462 \h 10HYPERLINK \l "_Toc386984463" (二)内部风险控制措施 PAGEREF _Toc386984463 \h 11HYPERLINK \l "_Toc386984464" 四、具体业务风险与控制 PAGEREF _Toc386984464 \h 14HYPERLINK \l "_Toc386984465" (一)、组织架构 PAGEREF_Toc386984465 \h 14HYPERLINK \l "_Toc386984466" (二)、发展战略 PAGEREF_Toc386984466 \h 16HYPERLINK \l "_Toc386984467" (三)、全面预算 PAGEREF_Toc386984467 \h 19HYPERLINK \l "_Toc386984468" (四)、人力资源 PAGEREF_Toc386984468 \h 22HYPERLINK \l "_Toc386984469" (五)、研究开发 PAGEREF_Toc386984469 \h 24HYPERLINK \l "_Toc386984470" (六)、合同管理 PAGEREF_Toc386984470 \h 27HYPERLINK \l "_Toc386984471" (七)、工程项目 PAGEREF_Toc386984471 \h 29HYPERLINK \l "_Toc386984472" (八)、采购管理 PAGEREF_Toc386984472 \h 32HYPERLINK \l "_Toc386984473" (九)、销售业务 PAGEREF_Toc386984473 \h 35HYPERLINK \l "_Toc386984474" (十)、资金管理 PAGEREF_Toc386984474 \h 38HYPERLINK \l "_Toc386984475" (十一)、资产管理 PAGEREF _Toc386984475 \h 42HYPERLINK \l "_Toc386984476" (十二)、担保业务 PAGEREF _Toc386984476 \h 44HYPERLINK \l "_Toc386984477" (十三)、财务报告 PAGEREF _Toc386984477 \h 47HYPERLINK \l "_Toc386984478" (十四)、信息系统 PAGEREF _Toc386984478 \h 49HYPERLINK \l "_Toc386984479" 第四部分:信息传递与沟通PAGEREF _Toc386984479 \h 51HYPERLINK \l "_Toc386984480" 一、对外信息沟通 PAGEREF_Toc386984480 \h 51HYPERLINK \l "_Toc386984481" 二、内部信息传递 PAGEREF_Toc386984481 \h 54HYPERLINK \l "_Toc386984482" 第五部分:内部控制实施与监督PAGEREF _Toc386984482 \h 56HYPERLINK \l "_Toc386984483" 一、内部审计委员会职责与权限PAGEREF _Toc386984483 \h 56HYPERLINK \l "_Toc386984484" 二、内部控制有效性评价 PAGEREF _Toc386984484 \h 56第一部分:总论一、目的、意义及原则编制和实施《内部控制手册》(以下简称《手册》),是为了遵循国家相关法律法规,满足资本市场对公众公司内部控制监管的要求,进一步完善现代企业制度和法人治理结构,确保公司各项工作规范有序进行,最大化减少风险,提高公司经营管理水平,保障公司战略的实施。
内部控制参考文献2021年

内部控制参考文献2021年
针对内部控制的参考文献,2021年涌现了许多重要的研究和文献。
内部控制是公司管理和监督活动的一部分,旨在确保公司达成其目标。
2021年的参考文献主要涵盖了内部控制的各个方面,包括理论研究、实践案例和最佳实践指南。
在2021年的参考文献中,一些研究聚焦于内部控制的理论框架和概念。
这些文献探讨了内部控制对公司绩效和风险管理的影响,以及内部控制与公司治理、财务报告质量之间的关系。
这些研究有助于深入理解内部控制的重要性,以及其在公司运营中的作用。
此外,2021年的参考文献还包括了许多实践案例和经验分享。
这些文献涵盖了各行各业的公司,从中小型企业到跨国公司,从金融行业到制造业。
这些案例研究提供了宝贵的经验教训,帮助读者了解内部控制在不同环境下的应用和挑战。
最后,2021年的参考文献还包括了一些最佳实践指南和标准。
这些文献提供了关于内部控制设计和实施的具体建议,帮助公司更好地建立和改进其内部控制体系。
总的来说,2021年的内部控制参考文献涵盖了理论研究、实践案例和最佳实践指南,为读者提供了全面的了解和参考。
这些文献对于研究者、从业人员和决策者都具有重要的参考价值,有助于推动内部控制领域的发展和实践。
企业内部控制论文参考文献综述

[9] 邵军,刘志远. 企业集团内部资本市场对其成员企业融资约束的影响--来自中国企业集团的经验证据[J]. 中国会计评论. 2008(03)
[10] 周倩倩. 中国系族集团内部资本市场效率研究[D]. 北京交通大学 2010
[8] 吴大立. 输电线路保护新原理及实现技术的研究[D]. 华中科技大学 2008
[9] 张侃君. 特大型水轮发电机保护系统及其动模试验新技术[D]. 华中科技大学 2008
[10] 杨军. 高温超导电缆保护理论与技术研究[D]. 华中科技大学 2006
[11] 夏勇军. 大型水轮发电机故障暂态仿真及主保护优化的研究与应用[D]. 华中科技大学 2006
[13] 邵军,刘志远. 企业集团内部资本配置的经济后果--来自中国企业集团的证据[J]. 会计研究. 2008(04)
[14] 冯丽霞,孙源. 不同组织结构内部资本市场运行机制比较[J]. 财会通讯(学术版). 2008(02)
[15] 丁忠明,王振富. 公司董事会治理研究:综述与启示[J]. 上海经济研究. 2008(01)
企业内部控制是指一个单位为了实现其经营目标,保护资产的安全完整,确保经营方针的贯彻执行,保证经营活动的经济性、效率性和效果性而在单位内部采取的自我调整、约束、规划、评价和控制的一系列方法、手段与措施的总称。下面是
小编带来的关于企业内部控制论文参考文献的内容,欢迎阅读参考!
企业内部控制论文参考文献(一)
[3] 孔祥平,张哲,尹项根,王菲,何茂慧. 含逆变型分布式电源的电网故障电流特性与故障分析方法研究[J]. 中国电机工程学报. 2013(34)
企业内部控制管理手册
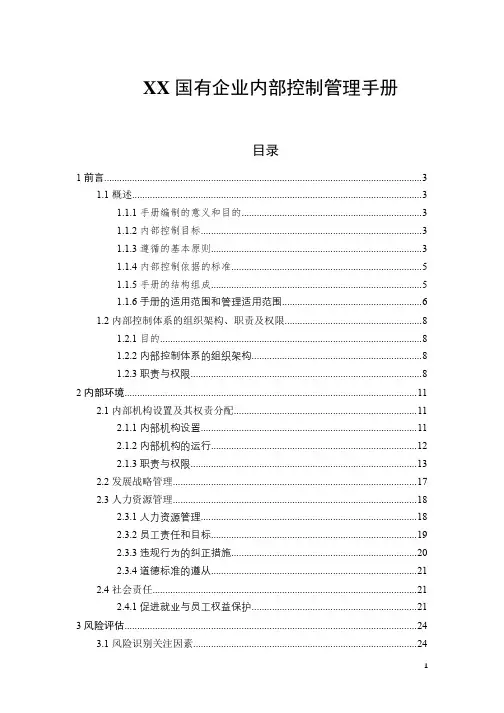
XX国有企业内部控制管理手册目录1前言 (3)1.1概述 (3)1.1.1手册编制的意义和目的 (3)1.1.2内部控制目标 (3)1.1.3遵循的基本原则 (3)1.1.4内部控制依据的标准 (5)1.1.5手册的结构组成 (5)1.1.6手册的适用范围和管理适用范围 (6)1.2内部控制体系的组织架构、职责及权限 (8)1.2.1目的 (8)1.2.2内部控制体系的组织架构 (8)1.2.3职责与权限 (8)2内部环境 (11)2.1内部机构设置及其权责分配 (11)2.1.1内部机构设置 (11)2.1.2内部机构的运行 (12)2.1.3职责与权限 (13)2.2发展战略管理 (17)2.3人力资源管理 (18)2.3.1人力资源管理 (18)2.3.2员工责任和目标 (19)2.3.3违规行为的纠正措施 (20)2.3.4道德标准的遵从 (21)2.4社会责任 (21)2.4.1促进就业与员工权益保护 (21)3风险评估 (24)3.1风险识别关注因素 (24)3.2风险类别 (24)3.3风险评估 (24)3.3.1风险评估目标 (24)3.3.2风险识别 (25)3.3.3风险分析 (26)4控制活动 (27)4.1控制活动分类与形式 (27)4.1.1控制活动的分类 (27)4.1.2控制活动的形式 (27)4.2内部控制要求及保障措施 (28)4.2.1公司业务流程总目录 (28)4.2.2各业务流程的关键控制目标和控制措施 (32)4.2.3资金活动日常资金活动管理 (32)4.2.4采购业务 (33)4.2.5资产管理 (34)4.2.6财务报告 (35)5信息与沟通 (38)5.1内控关注要点: (39)5.2控制措施: (39)5.3反舞弊机制 (41)6内部监督 (43)6.1目的 (43)6.2内部监督 (43)7附件 (45)1前言1.1概述1.1.1手册编制的意义和目的XX有限公司(以下简称公司)作为XX集团(以下简称集团)控股子公司, 为提高公司内部控制管理水平, 形成常态的规范化管理, 提高风险防范能力, 全面贯彻财政部、证监会、审计署、银监会、保监会等五部委颁布的《企业内部控制基本规范》及《企业内部控制配套指引》, 特编制《内部控制管理手册》, 作为建立、执行、评价及验证内部控制的依据, 确保公司从思想上提高管理水平, 增强风险防范能力, 保证公司协调、持续、快速发展。
关于内部控制的文献综述

关于内部控制的文献综述[摘要]内部控制,是指一个单位为了实现其经营目标,保护资产的安全完整,保证会计信息资料的正确可靠,确保经营方针的贯彻执行,保证经营活动的经济性、效率性和效果性而在单位内部采取的自我调整、约束、规划、评价和控制的一系列方法、手段与措施的总称。
企业单位经营、管理、活动的方方面面都贯穿着会计内部控制,会计内部控制制度属于社会经济发展到一定阶段的产物,是现代企业管理的重要手段。
而随着市场经济的建立与发展,企业的内部控制问题逐渐引起我国广泛的关注。
本文简要阐述了会计内部控制的含义,存在问题和解决措施,也对如今备受瞩目的国内外有关企业内部控制的相关文献进行了收集整合,发现国内外主要从内部控制的总体构想、内部控制的评价、内部控制信息的披露、等方面对企业内部审计进行了研究。
[关键词]会计内部控制文献综述概述内控评价随着我国经济的飞速发展,在为我们带来很多机遇的同时,也带来了更多的挑战和竞争。
为了能够在市场经济中屹立不倒、处于不败之地,这就对我们各个方面都有严肃的要求,特别是要有一套完整的制度体系。
而会计控制制度无疑是各种制度体系的重中之重。
所以企业均应加强、规范内部控制,才能提高公司经营管理水平和风险防范能力,从而更好地抵御当前严峻的市场形势,最终促进公司良性发展。
本文就搜集而来的关于企业会计内部控制各类文献进行了一部分的整合归纳,便于更好的了解内部控制意义所在,并对其所针对提出的问题进行了提炼整合,便于更为直观的认识内部控制并对其进行有利改进。
一、关于内部控制的简要概述在经济快速发展的当下社会,企业实施内部控制是如今新时代提高企业竞争力及企业经营效率的必然要求。
如果企业要想在竞争激烈的市场环境中立足并获得长远的发展,那么巩固基础、完善并加强企业内部控制实乃重中之重。
我们所说的企业会计内部控制是内部控制机构中非常重要的因素之一,在内部控制整个体系中能够发挥其重要作用。
(一)内部控制制度的基本含义我们所说的内部控制制度是指企业为了达到其预期的经营目标,为了资产得以完整安全,会计资料能够保持可靠和准确,使会计资料能够保持可靠和准确,使企业的经营方针得以确实贯彻的落实,使企业所有经营活动能够高效、经济而在企业内部开展并且实施一系列的自我评价、约束、控制、规划、调整等措施、手续、方法的总称。
企业内部会计控制制度参考文献
企业内部会计控制制度参考文献企业内部会计控制制度是企业为了确保财务报表的准确性、合规性和公正性而制定的一系列制度、规范和操作程序。
下面是一些与企业内部会计控制制度相关的参考内容。
1.《企业核算管理办法》这是财政部颁布的一项规范企业核算管理的文件,其中包括了企业内部会计控制制度的基本要求、会计处理规范和报表编制要求等方面的内容,对企业制定和执行内部会计控制制度提供了指导。
2.《会计基础工作制度》这是中国注册会计师协会发布的一项制度,规范了企业会计基础工作的流程和要求。
其中包括了企业内部会计控制制度的建立与完善、内部控制活动的执行和监督等方面的内容,对企业内部会计控制制度的建设提供了参考。
3.《企业内部控制基本规范》这是中国注册会计师协会发布的一项规范,详细阐述了企业内部控制的基本规范要求,其中包括了内控环境、风险评估、控制活动、信息与沟通以及监督等方面的内容,对企业内部会计控制制度的设计和执行提供了指导。
4.《企业内部会计控制制度框架与实施指南》这是中国注册会计师协会会计准则委员会发布的一项指南,旨在帮助企业建立健全的内部会计控制制度。
指南详细介绍了企业内部会计控制制度的框架、设计原则、具体内容和实施步骤,为企业内部会计控制制度的制定和改进提供了具体指导。
5.《内部会计控制与风险管理》这是林建华、杨丹主编的一本书,介绍了内部会计控制与风险管理的理论、方法和实践。
书中详细讲解了企业内部会计控制制度的设计与实施、内部控制风险评估与管理、风险溢价估计与内部控制评价等内容,为企业设计和实施内部会计控制制度提供了理论依据和操作指南。
通过参考以上文献,企业可以了解到企业内部会计控制制度建设的基本要求与原则,掌握企业内部会计控制制度设计的流程与步骤,同时也可以学习到如何评估与管理内部控制风险,为企业的财务管理提供更有效的保障。
企业可以根据自身情况,结合文献中提供的指导和经验,制定适合本企业的内部会计控制制度,确保企业财务报表的准确性、合规性和公正性。
内部控制管理手册两篇
内部控制管理手册两篇篇一:内部控制管理手册体系框架分册XXX公司二○XX年一月目录公司简介………………………………………………………………………………………手册说明………………………………………………………………………………………1总论…………………………………………………………………………………………1·1概述………………………………………………………………………………………1·2内部控制体系框架………………………………………………………………………1·3组织结构、职责与权限…………………………………………………………………2控制环境……………………………………………………………………………………2.1概述………………………………………………………………………………………2.2诚信与道德价值观………………………………………………………………………2.3发展目标…………………………………………………………………………………….2.4管理理念与企业文化………………………………………………………………………2.5风险管理策略…………………………………………………………………………….2.6董事会及下属委员会………………………………………………………………………2.7组织结构…………………………………………………………………………………..2.8权利和责任分配……………………………………………………………………………2.9人力资源政策与措施…………………………………………………………………………3.10员工胜任能力……………………………………………………………………………2.11反舞弊机制…………………………………………………………………………………3风险评估……………………………………………………………………………………3·1概述………………………………………………………………………………………3·2建立风险评估机制………………………………………………………………………3·3建立并完善风险管理体系………………………………………………………………4控制活动……………………………………………………………………………………4·1概述………………………………………………………………………………………4·2控制活动的实施…………………………………………………………………………5信息与沟通…………………………………………………………………………………5·1概述………………………………………………………………………………………5·2信息………………………………………………………………………………………5·3沟通………………………………………………………………………………………5·4信息系统总体控制………………………………………………………………………5·5信息系统应用控制………………………………………………………………………5·6信息披露…………………………………………………………………………………6监督…………………………………………………………………………………………6·1概述………………………………………………………………………………………6·2持续监督…………………………………………………………………………………6·3独立评估…………………………………………………………………………………6·4缺陷报告…………………………………………………………………………………附件《内部控制管理手册》(地区公司分册)编制规范……………………………………公司简介XXX公司(简称“XXX”)是于1999年11月5日在XXX天然气集团公司(简称“中油集团”)重组过程中,按照中华人民共和国公司法成立的股份有限公司。
企业内部控制论文参考文献综述(2)
企业内部控制论文参考文献综述(2)企业内部控制论文篇1浅谈企业内部控制制度建设对国有资产经营管理的影响如今,很多国有企业的内部控制制度并不完善,存在很多漏洞,对国有资产作用的发挥造成了严重影响。
因此,本文强调了企业内部控制的作用并提出了一系列的完善策略。
一、企业内部控制对国有资产管理的作用(一)提升企业效益通过内部控制,企业能够将会计、统计、生产、营销、财务等各部门结合起来,使各部门密切配合,发挥整体作用,进而使企业提高效益,实现可持续发展。
(二)保证资产安全在企业内部控制制度中,明确规定好企业资产的处理手续和程序,并完善制约机制,科学有效的监督和制约财产物资的采购,计量,验收等各个环节,及时纠正损失浪费现象,避免滥用职权,贪污腐败等现象的发生,同时强化企业资产安全保护工作,保证企业的正常运营和发展。
(三)保障会计信息真实性通过内部控制,相关人员可以发现会计审核、汇总、复查中的错误并进行及时纠正,使企业避免不必要的损失,从而确保企业会计信息的真实可靠,保证企业的正常发展。
二、国有资产经营管理内部控制的现状分析(一)思想重视不够一些企业的国有资产经营管理层仅仅重视经营性的国有资产管理,而忽视了非经营性的国有资产的管理,即忽视了那些无法直接投入到生产经营中去创造利润的国有资产。
这种思想上不重视直接导致了国有资产经营管理管理制度不完善的现状,大量国有资产的经营管理存在漏洞,难以转变为经营性资产,其安全性和可靠性也受到严重威胁,更妄谈国有资产保值增值。
(二)内控制度不规范首先,国有资产经营管理内部控制制度缺少,尤其是非经营性国有资产的控制制度缺少,一些来自事业单位的国有资产员工对控制制度态度冷漠,把这些制度当做纸面制度,没有进行积极落实。
其次,风险评估机制缺失,如资产盘点不够准确、盘点结果处理不当,资产租赁未经有效审批、租赁费用计算不合理,资产报废不符合规定、管理不善等。
(三)内部审计不健全很多企业的国有资产控制部门不设立内部审计制度,发挥不了内部审计的全面作用。
(完整版)内部控制英文文献目录
内部控制英文文献目录1.内部控制管制对盈余质量的影响:来自德国的证据(March 2008)The effect of internal control regulation on earnings quality: Evidence from Germany2.内部控制制度如何影响财务报告?(Altamuro,June 24, 2009)How Does Internal Control Regulation Affect Financial Reporting3.财务报告内部控制缺陷的决定因素(Doyle,May 15, 2006)Determinants of weaknesses in internal control over financial reporting4.应计质量与财务报告内部控制(Doyle,January 24, 2007)Accruals Quality and Internal Control over Financial Reporting5.SOX内部控制缺陷对公司风险与权益资本成本的影响(Ashbaugh-Skaife,June 10, 2008)The Effect of SOX Internal Control Deficiencies on Firm Risk and Cost of Equity6.审计委员会质量、审计师独立性与内部控制缺陷(Zhang)Audit Committee Quality, Auditor Independence, and Internal Control Weaknesses7.小企业受益于内部控制缺陷审计师认证吗Do Small Firms Benefit from Auditor Attestation of Internal Control Effectiveness8.内部控制缺陷的决定因素(Jahmani)Determinants of Internal Control Weaknesses In Accelerated Filers9.操控性应计项目能帮助区分内部控制缺陷和欺诈吗Do Discretionary Accruals Help Distinguish between Internal Control Weaknesses and Fraud10.财务报告质量对债务契约的影响:来自内部控制缺陷报告的证据(Costello,September 4, 2010)The impact of financial reporting quality on debt contracting: Evidence from internal control weakness reports11.重大内部控制缺陷与盈余管理Material Internal Control Weaknesses and Earnings Management in the Post-SOX Environment12.家族企业的内部控制(April 2013)Internal Controls in Family-Owned Firms()13.内部控制质量对企业并购绩效的影响研究Study on the Impact of the Quality of Internal Control on the Performance of M&A14.内部控制质量与信用违约互换利差(January 2014)Internal Control Quality and Credit Default Swap Spreads15.家族企业内部控制:特征和后果Internal Control in Family Firms: Characteristics and Consequences16.内部控制报告与会计信息质量:洞察”遵守或解释的“内部控制制度Internal control reporting and accounting quality:Insight "comply-or-explain" internal control regime 17.内部控制报告与会计稳健性Internal Control Reporting and Accounting Conservatism18.会计信息质量影响产品市场契约吗?来自政府合同授予的证据(March 2014)Does Accounting Quality Influence Product Market Contracting? Evidence from Government Contract Awards19.公司特征与财务报告质量:尼日利亚制造业上市公司的证据20.内部控制情况与专家审计师选择The Association between Internal Control Situations and Specialist Auditor Choices21.审计费用反应了控制风险的风险溢价吗(2013-07)Do Audit Fees Reflect Risk Premiums for Control Risk?22.内部控制质量与审计定价Internal Control Quality and Audit Pricing under the Sarbanes-Oxley Act23.内部控制缺陷与权益资本成本:来自萨班斯法案404节披露的证据Internal Control Weakness and Cost of Equity: Evidence from SOX Section 404 Disclosures24.内部控制缺陷与信息不确定性Internal Control Weaknesses and Information Uncertainty25.重大内部控制缺陷与股票价格崩溃危险:来自404条款披露的证据(May 2013)Material Weakness in Internal Control and Stock Price Crash Risk: Evidence from SOX Section 404 Disclosure26.SOX内部控制缺陷对公司风险与权益资本成本的影响The Effect of SOX Internal Control Deficiencies on Firm Risk and Cost of Equity27.信用评级、债务成本与内部控制信息披露:SOX302和SOX404法的比较28.萨班斯-奥克斯利法案对会计信息债务契约价值的影响The Effect of Sarbanes-Oxley on the Debt Contracting Value of Accounting Information29.财务报告内部控制的不利意见与审计师解聘/辞职Adverse Internal Control over Financial Reporting Opinions and Auditor Dismissals/Resignations30.新管理人员任命与随后的SOX法案404的意见Appointment of New Executives and Subsequent SOX 404 Opinion31.萨班斯奥克斯利:有关萨班斯法案404影响的证据Sarbanes-Oxley: The Evidence Regarding the Impact of Sox 40432.内部控制有效性自愿披露的经济决定因素及后果:从首次公开发行的证据(March 2013)Economic Determinants and Consequences of Voluntary Disclosure of Internal Control Effectiveness: Evidence from Initial Public Offerings33.非营利组织中内部控制问题的原因和后果The Causes and Consequences of Internal Control Problems in Nonprofit Organizations34.SOX内部控制披露在公司控制权市场中的价值The Value of SOX Internal Control Disclosures in the Market for Corporate Control35.内部控制缺陷与销售、一般的及行政费用的非对称性行为Internal Control Weakness and the Asymmetrical Behavior of Selling, General, and Administrative Costs 36.内部控制缺陷及补救措施披露对投资者感知的盈余质量的影响The Impact of Disclosures of Internal Control Weaknesses and Remediation on Investor-Perceived Earnings Quality37.内部控制缺陷与美国上市的中国公司与美国公司的审计师SOX Internal Control Deficiencies and Auditors of U.S.-Listed Chinese versus U.S. Firms38.内部控制信息披露与代理成本—来自瑞士的非金融类上市公司的证据(January 2013)Internal Control Disclosure and Agency Costs Evidence from Swiss listed non-financial Companies 39.萨班斯奥克斯利法案与公司投资:来自自然实验的新证据The Sarbanes-Oxley Act and Corporate Investment: New Evidence from a Natural Experiment40.国内投资者保护、所有权结构与交叉上市公司遵守SOX要求披露内部控制缺陷Home Country Investor Protection, Ownership Structure and Cross-Listed Firms’Compliance with SOX-Mandated Internal Control Deficiency Disclosure41.审计师对披露重大缺陷相关风险的看法Auditors’ Perceptio ns of the Risks Associated with Disclosing Material Weaknesses42.交叉上市公司提供与美国公司相同质量的披露?来自萨班斯-奥克斯利法案302条款下的内部控制缺陷信息披露的证据Do cross-listed firms provide the same quality disclosure as U.S. firms? Evidence from the internal control deficiency disclosure under Section 302 of the Sarbanes-Oxley Act43.内部控制缺陷与并购绩效Internal Control Weaknesses and Acquisition Performance44.萨班斯-奥克斯利法案302条款下的内部控制缺陷对审计费用的影响The Effect of Internal Control Weakness under Section 404 of the Sarbanes-Oxley Act on Audit Fees 45.审计师对财务报告内部控制的评价对审计费用、债务成本及净遵从收益The Effect of Auditors’ Assessment of Internal Control of over Financial Reporting on Audit Fees, Cost of Debt and Net Compliance Benefit46.上市公司披露的信息含量与萨班斯-奥克斯利法案Information Content of Public Firm Disclosures and the Sarbanes-Oxley Act47.财务错报与股票市场的契约:从增发的证据Financial Misstatements and Contracting in the Equity Market: Evidence from Seasoned Equity Offerings48.公司治理质量与SOX 302条款下内部控制报告Corporate Governance Quality and Internal Control Reporting Under Sox Section 30249.审计委员会质量、审计师独立性与内部控制缺陷Audit Committee Quality, Auditor Independence, and Internal Control Weaknesses50.SOX404条款的影响:成本,盈余质量与股票价格The Effect of SOX Section 404: Costs, Earnings Quality, and Stock Prices51.内部控制缺陷与银行贷款契约:来自SOX404条款披露的证据Internal Control Weakness and Bank Loan Contracting: Evidence from SOX Section 404 Disclosures 52.审计师对财务报告内部控制的决策:分析、综合和研究方向Auditors’ Internal Control Over Financial Reporting Decisions: Analysis, Synthesis, and Research Directions53.应计质量与财务报告内部控制(Doyle,The Accounting Review, forthcoming)Accruals Quality and Internal Control over Financial Reporting54.业绩基础CEO和CFO 薪酬对内部控制质量的影响The impact of performance-based CEO and CFO compensation on internal control quality55.内部控制重大缺陷与CFO 薪酬Internal Control Material Weaknesses and CFO Compensation56.财务报告内部控制缺陷的决定因素Determinants of weaknesses in internal control over financial reporting57.内部控制与管理指南Internal Control and Management Guidance58.2002萨班斯-奥克斯利法案302条款下内部控制缺陷的市场反应以及这些缺陷的特征Market Reactions to the Disclosure of Internal Control Weaknesses and to the Characteristics of those Weaknesses under Section 302 of the Sarbanes Oxley Act of 200259.自愿报告内部风险管理和控制系统的经济激励Economic Incentives for Voluntary Reporting on Internal Risk Management and Control Systems60.后萨班斯法案时代审计意见的信息含量The information content of audit opinions in the post-sox era61.上市公司披露的信息含量与萨班斯-奥克斯利法案(April, 2010)Information Content of Public Firm Disclosures and the Sarbanes-Oxley Act62.信息摩擦如何影响公司资产流动性的选择?萨班斯法案404条款的影响How d o Informational Frictions Affect the Firm’s Choice of Asset Liquidity? The Effect of SOX Section 40463.已审计的信息披露给资本市场参与者带来利益是什么(December 19, 2013)What are the benefits of audited disclosures to equity market participants64.诉讼风险与审计定价:公众股权的作用(January 7, 2013)Litigation Risk and Audit Pricing: The Role of Public Equity65.萨班斯-奥克斯利法案对IPO和高收益债券发行人的影响The Impact of Sarbanes-Oxley on IPOs and High Yield Debt Issuers66.来自金融危机的公司治理的经验教训The Corporate Governance Lessons from the Financial Crisis67.谁对企业欺诈吹口哨Who Blows the Whistle on Corporate Fraud68.内部控制缺陷与现金持有价值Internal Control Weakness and Value of Cash Holdings69.民族文化和制度环境对内部控制信息披露的影响The impact of national culture and institutional Environment on internal control disclosures70.财务报告质量与权益资本成本之间联系的讨论:一些个人的意见(June 6, 2013)Some Personal Observations on the Debate on the Link between Financial Reporting Quality and the Cost of Equity Capital71.使用盈利预测同时估计企业层面的权益资本成本和长期增长Using Earnings Forecasts to Simultaneously Estimate Firm-Specific Cost of Equity and Long-Term Growth72.高管薪酬差距与权益资本成本Executive Pay Disparity and the Cost of Equity Capital73.财务报告质量与公司债券市场(博士论文,Mingzhi Liu, 2011)Financial Reporting Quality and Corporate Bond MarketsReferencesAboody, D., J. Hughes, and J. Liu. (2005) Earnings quality, insider trading, and cost of capital. Journal of Accounting Research 43: 651–673.Akins, B., J. Ng and R. Verdi (2012) Investor competition over information and the pricing of information asymmetry. The Accounting Review 87(1): 35-58.Ali, A., A. Klein and J. Rosenfeld. (1992) Analysts’ use of information about permanent and transitory earnings components in forecasting annual EPS. The Accounting Review 67: 183-198.Amihud, Y., and H. Mendelson. (1986) Asset pricing and the bid-ask spread. Journal of Financial Economics 17: 223–249.Artiach, T. and P. Clarkson. (2011) Disclosure, conservatism and the cost of equity capital: A review of the foundation literature. Accounting and Finance 51(1): 2-49.Ashbaugh-Skaiffe, H., D. Collins, W. Kinney, Jr., and R. LaFond (2009) The effect of SOX internal control deficiencies on firm risk and cost of equity. Journal of Accounting Research 47(1): 1-43. Armstrong, C., J. Core, D. Taylor and R. Verrecchia (2011) When does information asymmetry affect the cost of capital? Journal of Accounting Research 49(1): 1-40.Balakrishnan, K., R. Vashishtha and R. Verrecchia (2012) Aggregate competition, information asymmetry and cost of capital: Evidence from equity market liberalization. Working paper, University of Pennsylvania.Barron, O., O. Kim, S. Lim and D. Stevens (1998) Using analysts forecasts to measure properties on analysts’ information environment. The Accounting Review 73: 421-433.Barry, C., and S. Brown. (1985) Differential information and security market equilibrium. Journal of Financial and Quantitative Analysis 20: 407–422.Barth, M., W. Beaver, and W. Landsman (2001) The relevance of value-relevance literature for financial accounting standard setting: Another view,” Journal of Accounting and Economics (Sept): 77-104. Barth, M., Y. Konchitchki and W. Landsman (2013) Cost of capital and earnings transparency. Journal of Accounting and Economics, forthcoming.Beyer A., D. Cohen, T. Lys and B. Walther (2010) The financial reporting environment: Review of the recent literature. Journal of Accounting and Economics 50: 296-343.Bhattacharya, N., F. Ecker, P. Olsson, and K. Schipper (2012) Direct and mediated association among earnings quality, information asymmetry, and the cost of capital, The Accounting Review 87(2): 449-482. Botosan, C. (1997) Disclosure level and the cost of equity capital. The Accounting Review 72: 323–350. Botosan, C., and M. Plumlee. (2002) A re-examination of disclosure level and the expected cost of equity capital. Journal of Accounting Research 40: 21–40.Botosan, C., M. Plumlee and Y. Xie (2004) The role of information precision in determining the cost of equity capital. Review of Accounting Studies 9 (2-3): 233-259.Botosan, C., and M. Plumlee. (2005) Assessing alternative proxies for the expected risk premium. The Accounting Review 80: 21-53.Botosan, C., M. Plumlee and H. Wen. (2011) The relation between expected returns, realized returns, and firm risk characteristics. Contemporary Accounting Research 28(4): 1085-1122.Brown, P. and T. Walter (2012) The CAPM: Theoretical validity, empirical intractability and practical applications. Abacus 1-7.Callahan, C., R. Smith and A. Spencer (2012) An examination of the cost of capital implications of FIN 46. The Accounting Review 87(4): 1105-1134.Chava, S., and A. Purnanandam (2010) Is default risk negatively related to stock returns? Review of Financial Studies 23: 2523-2559.Chen, S., B. Miao and T. Shevlin (2013) A new measure of disclosure quality: The level of disaggregation of accounting data in annual reports. Working paper, The University of Texas at Austin. Christensen, P., L. de la Rosa and G. Feltham (2010) Information and the cost of capital: An ex ante perspective. The Accounting Review 85(3): 817-848.Clarkson, P., J. Guedes and R. Thompson (1996) On the diversifiability, observability, and measurement of estimation risk. Journal of Financial and Quantitative Analysis 31: 69084.Claus, J., and J. T homas (2001) Equity premia as low as three percent? Evidence from analysts’ earnings forecasts for domestic and international stock markets. The Journal of Finance 56(5): 1629-1666. Clinch G., and B. Lombardi (2011) Information and the cost of capital: the Easley-O’Hara (2004) model with endogeneous information acquisition. Australian Journal of Management 36(5): 5-14.Coles, J., U. Loewenstein, and J. Suay. (1995) On equilibrium pricing under parameter uncertainty. The Journal of Financial and Quantitative Analysis 30: 347–374.Core, J., (2001) A review of the empirical disclosure literature: Discussion. Journal of Accounting and Economics 31: 441-456.Core, J., W. Guay and R. Verdi, (2008) Is accruals quality a priced risk factor? Journal of Accounting and Economics 46: 2-22.Daniel, K. and S. Titman, 1997, Evidence on the characteristics of cross-sectional variation in common stock returns. Journal of Finance 52, 1-33.Daske, H., L Hail, C. Leuz and R. Verdi (2008) Mandatory IFRS reporting around the world: Early evidence on the economic consequences. Journal of Accounting Research 46: 1085-1142.Daske, H., L Hail, C. Leuz and R. Verdi, (2013) Adopting a label: Heterogeneity in the economic consequences around IAS/IFRS adoptions. Journal of Accounting Research 51(3):495-548. Dechow, P. and I. Dichev. (2002) The quality of accruals and earnings: the role of accrual estimation errors. The Accounting Review 77 (Supplement): 35-59.Dechow, P., W. Ge and C. Schrand (2010) Understanding earnings quality: A review of the proxies, their determinants and their consequences. Journal of Accounting and Economics 50: 344-401. Dhaliwal, D., L. Krull and W. Moser (2005) Dividend taxes and implied cost of equity capital. Journalof Accounting Research 43(5): 675-708.Dhaliwal, D., L. Krull and O. Li (2007) Did the 2003 Tax Act reduce the cost of equity capital? Journal of Accounting and Economics 43(1): 121-150.Diamond, D., and R. Verrecchia. (1991) Disclosure, liquidity, and cost of capital. Journal of Finance 46: 1325–59.Dye, R., (2001) An evaluation of “essays on disclosure” and the disclosure literature in accounting. Journal of Accounting and Economics 32: 181-235.Easley, D., S. Hvidkjaer and M. O’Hara. (2002) Is information risk a determinant of asset returns. Journal of Finance 57: 2185-2221.Easley, D., and M. O’Hara. (2004) Information and the cost of capital. Journal of Fi nance 59: 1553–1583.Easton, P. (2004) PE ratios, PEG ratios, and estimating the implied expected rate of return on equity capital. The Accounting Review 79(1): 73-96.Easton, P., and S. Monahan. (2005) An evaluation of accounting based measures of expected returns. The Accounting Review 80: 501–538.Easton, P., and S. Monahan. (2010) Evaluating accounting-based measures of expected returns: Easton and Monahan and Botosan and Plumlee redux. Working paper, University of Notre Dame.Ecker, F., J. Francis, I. Kim, P. Olsson, and K. Schipper (2006). A returns-based representation of earnings quality. The Accounting Review 81: 749–780.Fama, E., and J. MacBeth. 1973. Risk, return, and equilibrium: Empirical tests. Journal of Political Economy 81: 607–636.Fama, E., and K. French. (1992) The cross-section of expected stock returns. Journal of Finance 47(2): 427-465.Fama, E., and K. French. (1993) Common risk factors in the returns on bonds and stocks. Journal of Financial Economics 33: 3–56.Francis, J., LaFond, R., Olsson, P., and K. Schipper. (2004) Costs of equity and earnings attributes. The Accounting Review 79: 967-1010.Francis, J., LaFond, R., Olsson, P., and K. Schipper. (2005) The market pricing of accruals quality. Journal of Accounting & Economics 39: 295-327.Francis, J., Nanda, D., and P. Olsson. (2008) Voluntary disclosure, information quality, and costs of capital. Journal of Accounting Research 46 (1): 53-99.Gebhardt,W., C. Lee and B. Swaminathan (2001) Towards an ex ante cost of capital. Journal of Accounting Research 39(1): 135-176.Goh, B-W., J. Lee, C-Y. Lim and T. Shevlin (2013) The effect of corporate tax avoidance on the cost of equity. Working paper, Singapore Management University.Gow, I., G. Ormazabal and D. Taylor (2010) Correcting for cross-sectional and time-series dependence in accounting research The Accounting Re view 85(2): 483-512.Gray, P., P. Koh and Y. Tong (2009) Accruals quality, information risk and cost of capital: Evidence from Australia. Journal of Business Finance and Accounting 36(1-2): 51-72.Guay, W., S.P. Kothari and S. Shu (2011) Properties of implied cost of capital using analysts’ forecasts. Australian Journal of Management 36(2): 125-149.Hail, L. (2002) The impact of voluntary corporate disclosure on the ex-ante cost of capital for Swiss firms European Accounting Review 11: 741-773.Hail, L., and C. Leuz. (2006) International differences in the cost of equity capital: Do legal institutions and securities regulation matter? Journal of Accounting Research 44(3): 485-531.Healy, P., and K. Palepu (2001) Information asymmetry, corporate disclosure, and the capital markets: A review of the empirical disclosure literature. Journal of Accounting and Economics 31: 405-440. Hirshleifer, D., K. Hou, and S.H. Teoh (2012) The accrual anomaly: Risk or mispricing? Management Science (58-2); 320–335.Holthausen, R., and R. Watts (2001) The relevance of value-relevance literature for financial accounting standard setting. Journal of Accounting and Economics (Sept): 3-75.Hribar, P. and T, Jenkins. (2004) The effect of accounting restatements on earnings revisions and the estimated cost of capital. Review of Accounting Studies 9(2-3): 337-356.Hughes, J. S., J. Liu, and J. Liu. (2007) Information asymmetry, diversification, and cost of capital. The Accounting Review 82: 705–729.Hughes, J. S., J. Liu, and J. Liu. (2009) On the association between expected returns and implied cost of capital” Review of Accounting Studies 14: 246-259.Hutchens, M. and S. Rego (2013) Tax risk and the cost of equity capital. Working paper, Indiana University.Hwang, L-S., W-J. Lee, S-Y. Lim and K-H. Park, (2013) Does information risk affect the implied cost of equity capital? An analysis of PIN and adjusted PIN. Journal of Accounting and Economics 55(2-3): 148-167.Kim, D., and Y. Qi (2010) Accruals quality, stock returns, and macroeconomic conditions. The Accounting Review 85(3): 937-978.Klein, R., and V. Bawa. (1977) The effect of estimation risk on optimal portfolio choice. Journal of Financial Economics 3: 215–231.Kothari, S.P., X. Li and J. Short. (2009) The effect of disclosures by management, analysts, and financial press on cost of capital, return volatility, and analyst forecasts: A study using content analysis. The Accounting Review 82(5): 1255-1297.Kravet, T. and T. Shevlin. (2010) Accounting restatements and information risk. Review of Accounting Studies 15: 264-294.Kyle, A. (1985) Continuous auctions and insider trade. Econometrica 53(6): 1315-1335.Lambert, R., C. Leuz, and R. Verrecchia. (2007) Accounting information, disclosure, and the cost of capital. Journal of Accounting Research 45(2): 385–420.Lambert, R., C. Leuz, and R. Verrecchia. (2012) Information asymmetry, information precision, and the cost of capital. Review of Finance 16: 1-29.Lambert, R., (2009) Discussion of “on the association between expected returns and implied cost of capital” Review of Accounting Studies 14: 260-268.Leuz, C., and R. Verrecchia (2004) Firms’ capital allocation choices, information quality, and the cost of capital. Working paper, University of Pennsylvania.Li, V., T. Shevlin and D. Shores (2013) Revisiting the AQ measure of accrual quality. Working paper, University of Washington.Lys, T., and S. Sohn. (1990) The association between revisions of financial analyst’ earnings forecasts and security price changes. Journal of Accounting and Economics 13: 341-363.Mashruwala, C. and S. Mashruwala (2011) The pricing of accrual quality: January versus the rest of the year. The Accounting Review 86(4): 1349-1381.McInnis, J. (2010) Earnings smoothness, average returns and implied cost of equity capital. The Accounting Review 85(1): 315-341.Mohanram, P., and D. Gode (2013) Removing predictable analyst forecast errors to improve implied cost of equity estimates. Review of Accounting Studies 18: 443-478.Ogneva, M., K.R. Subramanyam, and K. Raghunandan (2007) Internal control weakness and cost of equity: Evidence from SOX Section 404 disclosures. The Accounting Review 82(5):1255-1297. Ogneva, M., (2012) Accrual quality, realized returns, and expected returns: The importance of controlling for cash flow shocks, The Accounting Review 87(4): 1415-1444.Petersen, M., (2009) Estimating standard errors in finance data panels: Comparing approaches. Review of Financial Studies 22(1): 435-480.Petkova, R. (2006) Do the Fama-French factors proxy for innovation in predictive variables? Journal of Finance 61: 581-612.Reidl, E., and G. Serafeim (2011) Information risk and fair values: An examination of equity betas. Journal of Accounting Research 49(4): 1083-1122.Strobl, G., (2013) Earnings manipulation and the cost of capital. Journal of Accounting Research, forthcoming.Verrecchia, R. (2001) Essays on disclosure. Journal of Accounting and Economics 32: 97-180. Vuolteenaho, T. (2002) What drives firm-level stock returns? The Journal of Finance 57: 233–264.How Do Various Forms of Auditor Rotation Affect Audit Quality? Evidence from China内部控制质量、企业风险与权益资本成本——理论分析与实证检验1.Accruals Quality and Internal Control over Financial Reporting.Accounting Review, Oct2007, V ol.82 Issue52.Audit Committee Quality and Internal Control An Empirical Analysis.FullAccounting Review,Apr2005, Vol. 80 Issue 23.Balancing the Dual Responsibilities of Business Unit Controllers Field and Survey Evidence.Accounting Review, Jul2009, Vol. 84 Issue44.Corporate Governance and Internal Control over Financial Reporting A Comparison ofRegulatory Regimes Accounting Review, May2009, Vol. 84 Issue 35.Earnings Management of Firms Reporting Material Internal Control Weaknesses under Section404 of the Sarbanes-Oxley Act. Auditing, Nov2008, Vol. 27 Issue 26.Economic Incentives for V oluntary Reporting on Internal Risk Management and Control Systems.Auditing, May2008, V ol. 27 Issue 67.Firm Characteristics and Voluntary Management Reports on Internal Control. Auditing, Nov2006,Vol. 25 Issue28.Former Audit Partners on the Audit Committee and Internal Control Deficiencies. AccountingReview, Mar2009, V ol. 849.Internal Control Quality and Audit Pricing under the Sarbanes-Oxley Act. Auditing, May2008, Vol.2710.Internal Control Weakness and Cost of Equity Evidence from SOX Section 404 DisclosuresAccounting Review, Oct2007, Vol. 8211.Internal Control Weaknesses and Information Uncertainty. Accounting Review, May2008, Vol. 8312.Internal Controls and the Detection of Management Fraud. Journal of Accounting Research,Spring99, Vol. 3713.Reducing Management's Influence on Auditors Judgments An Experimental Investigation of SOX404 Assessments Accounting Review, Nov2008, V ol. 8314.SOX Section 404 Material Weakness Disclosures and Audit Fees.Full Auditing, May2006, Vol.2515.The Effect of SOX Internal Control Deficiencies and Their Remediation on Accrual Quality.Accounting Review, Jan2008, Vol. 8316.The Impact of SOX Section 404 Internal Control Quality Assessment on Audit Delay in the SOXEra. Auditing, Nov2006, Vol. 25Ashbaugh-Skaife, H., Collins, D. W., & Kinney Jr., W. R. (2007). The discovery and reporting of internal control deficiencies prior to SOX-mandated audits. Journal of Accounting and Economics, 44(1–2), 166–192.Ashbaugh-Skaife, H., Collins, D. W., Kinney Jr, W. R., & Lafond, R. (2009). The Effect of SOX Internal Control Deficiencies on Firm Risk and Cost of Equity. Journal of Accounting Research, 47(1),1–43.Bahramian, A. (2011), Evaluation of the effectiveness of internal controls in an Investment Company, Master Thesis in Imam Hossein University, Iran.Daraby, M, (2006), analyzing the effect of strengthening internal controls, audit reports of companies listed on the Stock Audit, Master Thesis in Azan Islamic university.Doyle, J., Ge, W., & McVay, S. (2007). Determinants of weaknesses in internal control over financial reporting. Journal of Accounting and Economics, 44(1–2), 193–223.Feng, M., Li, C., & McVay, S. (2009). Internal control and management guidance. Journal of Accounting and Economics, 48(2–3), 190–209.Maham K., Poriya Nasab, A. (2000), Internal control) Integrated Framework( , Report of the Committee of the Commission Tardy, azman Hesabresy, Pages 118, 135.Ogneva, M., Subramanyam, K. R., & Raghunandan, K. (2007). Internal control weakness and cost of equity: evidence from SOX Section 404 disclosures. The Accounting Review, 82(5), 1255-1297.Rezaie Jahangoshaee, H, (1996). A analytical study of the degree of reliance of independent auditors on firms internal controls, Master Thesis, shahid Beheshti University, Iran.。