
两指标局部鞅_霍永亮
= Z 1n∧·
Z
2 n
∩1
Zn
↑2
Zn
× 1R+2
F 现验证 XZn为 ( Zzn ) -鞅, z≤ z′∈ 1R+2 , 有
F F F E (XZz′n| Zzn )= E (X z′| | Zz′n ) Zzn
F = E (X z′| ) Zzn
F F = E (X z′| | Zz1n ) Zzn F F F = E (X z′| | Zz1n′ | Zzn1 ) Zzn
T F 显然
Tm↑
× 1R+2 . 往证 X Tm 为一致可积 (
T z
m
)
-鞅。
G 由文 [ 4]定理 2. 6及 ( F4 )条件, z≤ z′∈ 1RZ+ ,
F F F E (XTz′m|
Tzm )= E (X Tz′m |
| Rz m, m
) T
z
m
·
F F = E (X zzm′∧ | Rm, m | Rzm, m ) Tzm
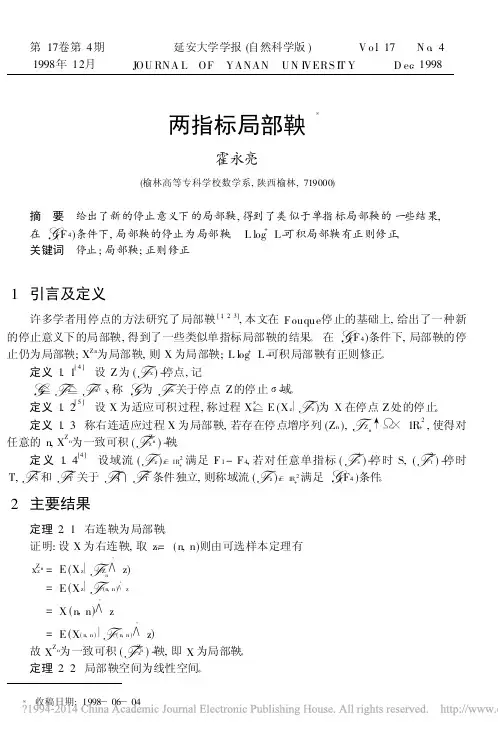
z ) z∈ 1R+2 满足 F 1 - F 4, 若对任意单指标 (
1 s
)
-停
时
S,
(
2 t
)
-停
时
F F F F F G T,
1 S
和
2 T
关于
S1∩
2 T
条件独立,
则称域流
(
z ) z∈ 1R+2 满足
( F4 )条件。
2 主要结果
定理 2. 1 右连鞅为局部鞅。
证明: 设 X 为右连鞅, 取 zn= ( n, n)则由可选样本定理有
F 定义
1.
2[ 5 ] 设
X
为适应可积过程,
称过程
X
z z
E ( X z|
z z
)为
X 在停点
Z 处的停止。
T 定义 1. 3 称右连适应过程 X 为局部鞅, 若存在停点增序列 ( Zn ),
Z
↑
n
× 1R+2 , 使得对
F 任意的 n, XZn为一致可积 ( Zzn ) -鞅。
F F F 定 义 1. 4[4] 设域流 (
L oca lM artingales of Two- param eter
H uo Y ong liang
( D epartm en t, ofM athem atics, Y ul in N orm al College, Shanx i 719000 ) A rstract T h is pape r g ives the tw o- param ete r loca l m ar ting ales unedr new stopp ing co ntex t, and hence certa in resu lts a re sim ilar to the lo ca l m ar ting ales o f onepa ram e ter ob tained. U nde r g ( F 4 ) cond it io n, the sto pp ing o f tw o- param ete r lo ca l m ar ting ale s is local m ar t ing ale s. T he local m ar t ing ale s o f L lo g+ L - in teg ra ls po s-
F F = E (X | Zz1n | Zz1n ) Zzn
F = E (X | Zz1n ) Zzn
F F = E (X z| | Zz1n ) Zzn
F = E (X z| ) Zzn
=
XZ z
n
由题设
XZ
具 1
n
有一
致可
积性
,
而
F (X Zz1n )Zn=
E
(
XZz
| 1
n
) Z
z
n
F F =
ε 3
取 N= m ax {N z, N z′}, 当 n> N 时上两式成立。 由 XZn的正则性, 当 z和 z′以 Q+ - , Q - + ,
Q - - 趋于某个 z0 时, 有
|X z -
X z′|≤|Xz -
XZz n|+
|X
Zn z
-
XZZ′n|+
|X Zz′n|-
X Z′|
<
ε3+
ε3 +
G G 由 XZn为一致可积
Z z
n
-鞅,
则 X
= Zz n
E (XZ∞n|
Zzn ),
F G F 故 E (XZ∞n|
Z z
n
)=
E (XZ∞n| | ∞Zn
) Zz n
F F = E (XZ∞n|
| ·
z∧ zn
) Zzn
F = E (XZ∞n|
) · ·
z∧ zn∧ z
G = E (XZ∞n| ) Zzn
令
k
·
Tm, k= ∨ ( Zn∧ Rn, m ),
m= 1
× 1R+2 , 使得 ( XZn )Rn, m
— 14 — 延安大学学报 (自然科学版 ) 第 17卷
则由 ( Zn )和 ( Rn, n )的递增性, 有
m
·
·
Tm Tm, m= ∨ ( Zk∧ Rk, k )= Zm∧ Rm, m, k= 1
F F =
E ( ( X zz′m )Rm, m |
| Rz m, m
) T
z
m
F = E ( ( X zzm )Rm, m | ) Tzm
F = E (X Tzm | ) Tzm
=
XT z
m
由于 (X Zm ) Rm, m= XTm , 故 X Tm一致可积。
因此, X 为局部鞅。
定理 2. 5 X 为局部鞅且 L log+ L -可积, 则 X 有正则修正 。
F 证明: 由题设及文 [ 5]定理 3, XZn为 L log+ L -可积 (
Z z
n
)
-鞅
,
根据
正则
性定
理,
XZn有正则
修正 (见文 [ 6 ]定理 9. 1), 仍记为 XZn。
由文 [ 7]系 2. 18, 有
F n→lim∞ XZzn=
n→lim∞ E( X z|
) Z
z
n
F = E ( X z|∨ ) Zzn n
F T 证明: 设 X 为局部鞅。 Z 为 ( z ) -停点。 令 ( Zn )为 X 的停点增序列,
Z
↑
n
× 1R+2 。
G F 由文 [ 4]定理 2. 6及 ( F4 )条件, 有 (X z ) Zn= (XZn ) z。 而 XZn为一致可积 ( Zzn ) -鞅, 由文 [ 5 ]
G F 定理 4及 ( F4 )条件, ( XZn ) z为一致可积 ( Zzn ) -鞅, 故 XZ 为局部鞅。
定理 2. 7 X 为 Gz 局部鞅, 则在 G( F4 )条件下, X 为局部鞅。
G G T 证明: 由 X 为 z 局部鞅, 故存在 z -停点增序列 ( zn ),
Z
↑
n
× 1R+2 , 使 X Zn为一致可
G F 积 ( Zzn ) -鞅。 由文 [ 4]定理 2. 1, zn 为 z -停点。
) Zzn
F =
E ( aX z+
bY z|
) Z
z
n
F F =
aE( X z|
Z z
n
)+
bE ( Y z|
) Zz n
= aXZzn+ bXZzn
F 从而 ( aX+ bY ) Zn为一致可积 (
Z z
n
)
-鞅。
即 ( aX+ bY )为局部鞅。
定理 2. 3 在 G( F4 )条件下, 局部鞅的停止为局部鞅。
第 4期 霍永亮: 两指标局部鞅
— 15 —
T F 证明: X 为局部鞅, 则存在停点增序列 ( Zn ),
Zn↑ × 1R+2 , 使 XZn为一致可积 (
Z z
n
)
-鞅,
G G 由文 [ 5]定理 4及文 [ 4 ]定理 2. 6, ( Xz) Zn为一致可积 (
Z z
n
)
-鞅,
但
Zn 不一定为
ε 3
=ε
于是 X 具有 Q+ - , Q -+ , Q - - 三个象限极限, 由于 X 为局部鞅, 故 X 为右连续的, 因此 X
具有正则修正 。
F G F 定理 2. 6 X 为局部鞅, z为 ( z ) -停点, 则在 ( F4 )条件下, Xz 为 z 关于停点 Z 的停止 σ-域 Gz 局部鞅。
1983, 13: 561- 577. 2 陈培德. 随机场一般理论. 中国科学院应用数学研究所, 1975 3 郑东. 两参数过程的停止与局部鞅. 陕西师范大学数学系硕士论文, 1988 4 霍永亮. 两指标停点 σ-域与停点的关系. 纺织基 础学报, 1998, ( 2). 5 霍永亮. 两指标过程的停止。 湛江师范学院学报, 1977, 18( 2) 6 P. Im k er lle r. T w o - param eter m a r ting a les and their quadra tic v a ria to n. L, N, M 1308, 1980 7 严加安. 鞅与随机积分引论. 上海科技出版社, 1981
随机规划经验逼近问题最优解集的几乎处处下半收敛性
随机规划经验逼近问题最优解集的几乎处处下半收敛性霍永亮
【期刊名称】《应用数学》
【年(卷),期】2012(25)1
【摘要】本文给出了随机规划经验逼近最优解集几乎处处下半收敛的一个充分条件,并由此得到随机规划经验逼近最优解集几乎处处Hausdorff收敛的一个充分条件.
【总页数】4页(P220-223)
【关键词】随机规划;最优解集;几乎处处下半收敛性;几乎处处Hausdorff收敛【作者】霍永亮
【作者单位】重庆文理学院数学与统计学院
【正文语种】中文
【中图分类】O221.5
【相关文献】
1.随机规划经验逼近最优解集序列的几乎处处上半收敛性 [J], 霍永亮;刘三阳
2.随机规划逼近问题最优解集的下半收敛性 [J], 霍永亮;刘三阳
3.概率约束规划逼近问题最优解集的下半收敛性 [J], 霍永亮
4.概率约束规划逼近最优解集的几乎处处上半收敛性 [J], 王俊林
5.随机规划经验逼近问题ε-最优解集的几乎处处Hausdorff收敛性 [J], 霍永亮因版权原因,仅展示原文概要,查看原文内容请购买。
求二层线性规划最优解的极点方法

求二层线性规划最优解的极点方法赵礼阳;霍永亮【摘要】根据二层线性规划的最优解一定可以在约束集的极点找到这一理论,给出了求解二层线性规划的极点方法,通过上层目标函数值的排序,避免了盲目验证极点这一缺陷,最后通过算例描述了算法求解过程,并验证了算法的有效性.【期刊名称】《重庆工商大学学报(自然科学版)》【年(卷),期】2015(032)011【总页数】4页(P89-92)【关键词】二层线性规划;约束条件;全局最优解;极点【作者】赵礼阳;霍永亮【作者单位】重庆师范大学数学学院,重庆401331;重庆文理学院数学与财经学院,重庆402160【正文语种】中文【中图分类】O221.5考虑如下二层线性规划问题(LBP):s.t. Ax+Bx≤b其中x∈X⊂Rn,y∈Y⊂Rm,X⊂Rn,Y⊂Rm是变量x,y的定义域.F:X×Y→R,以及f:X×Y→R均是线性函数.分别是约束函数的系数矩阵.二层线性规划问题是二层规划问题中最简单的一种类型,在二层线性规划问题中,其目标函数和约束条件都是线性存在的[1,2].对于二层规划,由于下层目标函数要以上层决策变量作为参数,上层又要以下层最优解反馈作为条件达到上层的最优,使得二层规划比一般的数学规划为更为复杂[3].Candler[4]和Townsley[5]在研究上层为无约束,且下层有唯一解的二层线性规划时得到一个有趣的性质:假设二层线性规划的最优解个数为有限个,那么在约束集的极点(顶点)处,至少存在一个极点是该问题的最优解.之后,Bard在约束集有界的前提下,证明了这是二层线性规划的一个共性[6].此处根据二层线性规划的全局最优解一定可以在约束域极点找到的理论,首先求出约束域的所有极点,根据极点处上层目标函数的值由小到大进行极点排序,然后按照这个顺序进行最优解检验,最终确定问题的全局最优,此处最后通过算例验证了算法的有效性.记为式(1)的约束域.下层问题对每个给定的上层变量x的可行集为S(x)}.上层变量的决策空间为,∃y∈Y,s.t.Ax+By≤b,x,y≥0}.下层问题对于给定的上层变量 x的合理反应集为(x)}}.定义1IR={(x,y):(x,y)∈S,y∈P(x)}为式(1)的可归纳域(可行集).为了保证式(1)有解,假设S为非空有界闭集;并且对于任意给定的上层决策变量,下层都只有唯一最优解反馈给上层.定义2 称(x*,y*)为问题(LBP)的全局最优解,简称最优解.如果存在(x*,y*)∈IR,使得对任意的(x,y)∈IR,都有F(x*,y*)≤F(x,y)成立[7].定义3 如果(x0,y0)是S的任意一个极点(顶点),则对于 S中相异于(x0,y0)的任意两点(x1,y1),(x2,y2)∈S,以及任意的实数λ>0,λ∈(0,1),下面等式(2)不成立.定理1 如果(x0,y0)是式(1)的唯一最优解,则(x0,y0)必是式(1)约束集的极点.证明反证法.假设(x0,y0)是式(1)的唯一最优解,但(x0,y0)不是式(1)约束集的顶点,则由定义3可得,存在( x1,y1),(x2,y2)∈S,且(1,y1)≠(x0,y0),(x2,y2)≠(x0,y0),存在一正数λ∈(0,1),等式(3)成立:于是有λx1+(1-λ)x2=0,λy1+(1-λ)y2=y0,那么(λx1+(1-λ)x2,λy1+(1-λ)y2)也是式(1)的最优解,显然成立等式(4):又因为(x0,y0)是式(1)的唯一最优解,则λ与(1-λ)分别乘入式(5)(6),相加得这就与F(x0,y0)=F(λx1+(1-λ)x2,λy1+(1-λ)y2)矛盾,故定理得证.定理2 如果(x0,y0)是式(1)的全局最优解,假设存在(x0,y1)是下层线性规划问题最优解,则y0=y1.证明因为(x0,y0)是线性规划式(1)的全局最优解,则上层给定的 x0,y0是下层问题的最优解.又因为存在(0,y1)是下层问题的最优解,则当x=x0,y1也是下层问题的最优解.于是,对于上层给定一个决策 x0,y0和y1均是下层问题y的最优解,这与假设上层任意给定决策x,下层都只有唯一反馈最优解矛盾,所以y0=y1.定理3 若(0,y0)是问题的最优解,( x0,y1)是问题的最优解,则 y0=y1当且仅当F(x0,y0)=F(x0,y1).证明必要性.如果(x0,y0)是问题的最优解,并且 y0=y1,那么(x0,y1)也是问题的最优解.于是成立等式:充分性:因为F(x0,y0)=F(x0,y1),于是(x0,y0)和(x0,y1)都是问题的最优解.对于上层给定 x0,下层反馈最优解为y0,y1,并且y0≠y1,这与假设任意给定x以后,下层只有唯一最优解反馈给上层矛盾,故得证.因为线性二层规划的全局最优解一定出现在该问题约束集的极点处,因此在约束集空间的极点上面就能搜索到问题的全局最优解.基于这种思想,设计一种快速极点算法,具体步骤描述如下:第1步:求出二层线性规划约束集合S的所有极点(xi,yi),i=1,2,…,n,不妨假设对于任意(xp,yp)和(xq,yq),满足p<q,则成立F(xp,yp)≤F(xq,yq),p,q∈N+,转第2步;第2步:给定问题一个初始解( xi,yi),i=1,i≤n,转第3步;第3步:把xi带入下层目标函数f(x,y),求解f(xi,y)在约束集S中的最优解yi+1,转第4步;第4步:比较yi+1和yi值,如果yi+1=yi,停止计算,输出全局最优解( xi,yi);否则令i=i+1,转第3步.例1s.t.y+2x≤122y-3x≥-4y-2x≤0很容易,能得到约束域S如图1所示.于是,根据文献[8]计算极点的算法,并且按照极点对应的上层目标函数值从小到大的顺序排列得到有序极点为(3,6),(4,4),(1,2),(2,1).然后开始检验,当x=3时,下层最优解为≠6,重新寻找初始点迭代.当x=4时,下层最优解为y=4,于是停止迭代.则问题最优解为(4,4),这与参考文献[9]中的最优解一致.因为二层线性规划问题反馈最优解集的非凸性,给求解二层线性规划问题带来了一定困难,此处给出的求解二层规划全局最优解的方法,简单易行,并且具有一定的应用价值.针对极点的重新排序,相对随机取初始迭代点,此方法能更快的找到全局最优解,最后的算例验证了算法的有效性.[1] BENSION H P. On the Structure and Properities of a Linear Multilevel Programming Problem[J]. Journal of Operation Theory and Applications,1989(60):353-373[2] BEREANU B. Stable Stochastic Linear Programs and Applications[J]. Mathematischen Operation for Schung and Statistik,1975,6(4):593-607 [3] BIALAS W F,KARWAN M H. Two-level Linear Programming[J]. Managenment Science,1984,30(8):1004-1020[4] CANDLER W,Norton R. Mulilevel Programming and Development Policy[R]. Technical Report 258,World Bank Staff,Washington DC,1977 [5] CANDLER W, TOWNSLEY R. A Linear Two-level Programming Problem[J]. Computers and Operations Research,1982,9(1):59-76[6] BARD,J F. An Investigation of the Linear Three Level Programming Problem[J]. IEEE Transaction System,Man and Cybernetics,1984,14(5):711-717[7] BRACKEN J,MCGILL J T. Mathematical Programs with Optimization Problems in the Constraints[J]. Operation Research,1973,21(1):37-44 [8] 陶玉洁,张永,杨杰.二层线性规划求顶点的算法[J].通化师范学院学报,2007,28(4):8-10[9] 胡长英.双层规划理论及其在管理中的应用[M].北京:知识产权出版社,2012[10] 李宏卫,王军.三次型非线性包装系统跌落冲击响应分析[J].包装工程:工程版,2015(19):18-22Key words: bilevel linear programming; constraint condition; globle optimal solution; exeme point。
两指标局部鞅_霍永亮
z ) z∈ 1R+2 满足 F 1 - F 4, 若对任意单指标 (
1 s
)
-停
时
S,
(
2 t
)
-停
时
F F F F F G T,
1 S
和
2 T
关于
S1∩
2 T
条件独立,
则称域流
(
z ) z∈ 1R+2 满足
( F4 )条件。
2 主要结果
定理 2. 1 右连鞅为局部鞅。
证明: 设 X 为右连鞅, 取 zn= ( n, n)则由可选样本定理有
第 4期 霍永亮: 两指标局部鞅
— 13 —
证明: 设 X、Y 为两个局部鞅, 现证明 aX+ bY 为局部鞅, 其中 a, b∈ R。
·
事实上, 设 ( Z1n )、 ( Z2n )分别为 X、 Y 的停点增序列, 令 Zn= Zn1∧ Z2n。 由文 [ 1 ]命题 8,
T T T T Zn=
F 证明: 由题设及文 [ 5]定理 3, XZn为 L log+ L -可积 (
Z z
n
)
-鞅
,
根据
正则
性定
理,
XZn有正则
修正 (见文 [ 6 ]定理 9. 1), 仍记为 XZn。
由文 [ 7]系 2. 18, 有
F n→lim∞ XZzn=
n→lim∞ E( X z|
) Z
z
n
F = E ( X z|∨ ) Zzn n
定理 2. 7 X 为 Gz 局部鞅, 则在 G( F4 )条件下, X 为局部鞅。
G G T 证明: 由 X 为 z 局部鞅, 故存在 z -停点增序列 ( zn ),
企业价值评估中行业β系数的计算方法

企业价值评估中行业β系数的计算方法
徐海成; 白武钰
【期刊名称】《《财会月刊(综合版)》》
【年(卷),期】2010(000)003
【摘要】运用收益法评估企业价值时,如何科学准确地估算β系数是一个至关重要的问题。
本文以酒店行业为例,对行业β系数计算方法和参数的选择以及β系数的稳定性进行了分析。
【总页数】3页(P48-50)
【作者】徐海成; 白武钰
【作者单位】长安大学经济与管理学院西安 710061
【正文语种】中文
【相关文献】
1.新兴行业中的企业价值评估--现金流量贴现法的应用 [J], 吴月琴;冯耕中
2.企业价值评估市场法中可比公司选择研究——以文化传媒行业为例 [J], 王晓婷;毕盛
3.价值系数在企业价值评估中的应用与比较 [J], 金鲜花;胡玄能;柯曼綦
4.企业投入产出分析中完全消耗系数的计算方法 [J], 刘善军
5.期权定价法在房地产行业并购目标企业价值评估中的应用 [J], 张燕; 吴伟容因版权原因,仅展示原文概要,查看原文内容请购买。
鞅在一类推广后的负二项风险模型中的应用
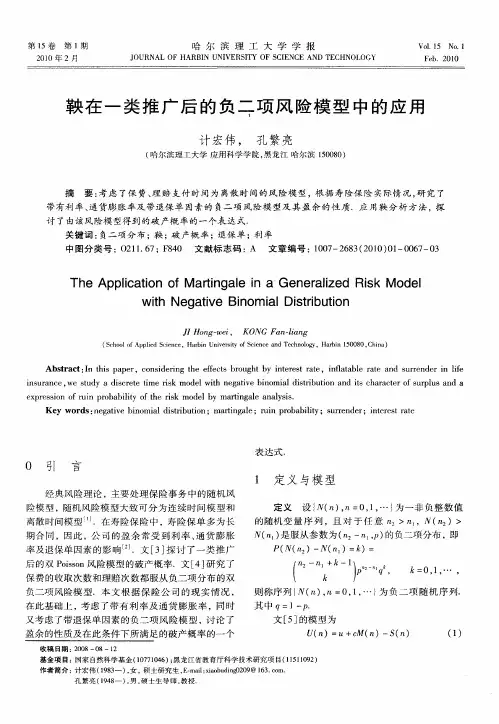
( col f pidSine HabnU i rt o cec n eh o g , ri 10 8 C ia Sho l c c , ri nv sy f i ea dT c nl y Habn 50 0, hn ) o Ap e e e i S n o
后 的双 Pi o os n风险模 型 的破 产概 率 .文 [ ] 究 了 s 4研
保费 的收 取次 数 和理赔 次 数都 服从 负 二项 分布 的双
负二项 风 险模 型 .本 文 根 据 保 险公 司 的 现 实 情 况 ,
( ) , =・ , 凡 + 一 。, 2 一 g 一 p , …
鞅 在 一 类 推 广 后 的 负 二 项 风 险 模 型 中 的 应 用
计 宏 伟 , 孔 繁 亮
( 尔 滨 理 工 大 学 应 用 科 学 学 院 , 龙 江 哈 尔 滨 10 8 ) 哈 黑 50 0
摘 要 : 考虑 了保 费、 赔 支付 时 间 为 离散 时 间 的风 险模 型 , 据 寿 险保 险 实际情 况 , 究 了 理 根 研
期合 同 ,因此 ,公 司 的盈 余 常受 到 利 率 、 货 膨 胀 通 率及 退保 单 因素 的 影 响 .文 [ ] 3 探讨 了一 类 推 广
N( . 是 服从 参数 为 ( : P 的负 二项分 布 ,即 n) n 一n , )
P( , )一 n )= N(z N( ): 2
带有利 率 、 通货 膨胀 率及 带 退保 单 因素 的 负二 项 风 险模 型 及 其 盈 余 的性 质 .应 用鞅 分 析 方 法 ,探 讨 了 由该 风险模 型得到 的破 产概 率 的一 个表 达 式.
鞅变换及其相关问题的开题报告
鞅变换及其相关问题的开题报告
鞅变换是概率论中经典的技术之一,它是通过将一些已知的鞅转化为另一个鞅来解决一些问题。
鞅变换具有广泛的应用,包括金融工程、统计学、计算机科学等领域。
在本次论文中,我们将主要研究鞅变换及其相关问题,探讨其理论基础和实际应用。
具体内容如下:
第一部分:鞅的基础知识
我们将介绍鞅的基本概念、性质和定理,包括:
1. 随机过程的定义和性质
2. 鞅的定义和性质
3. 鞅停时的定义和性质
4. 马尔可夫性和条件期望
第二部分:鞅变换的基本原理
我们将介绍鞅变换的基本定义和性质,包括:
1. 鞅变换的定义和性质
2. 鞅变换的基本操作(如线性组合、指数操作等)
3. 鞅变换的基本定理(如Doob-Meyer分解定理、可测时间变换定理等)
第三部分:鞅变换的应用
我们将介绍鞅变换在一些实际问题中的应用,包括:
1. 金融领域中的鞅变换,如对数变换、风险中性测度等
2. 统计学中的鞅变换,如最大似然估计、贝叶斯统计等
3. 计算机科学中的鞅变换,如随机算法、马尔可夫链蒙特卡罗方法等
第四部分:结论和展望
我们将总结鞅变换及其相关问题的重要性和成果,同时展望鞅变换在未来的发展方向和应用前景。
本次论文将涵盖鞅的基础知识、鞅变换的基本原理、鞅变换的应用以及结论和展望四个方面,旨在对鞅变换及其相关问题进行深入研究。
鞅、鞅差和市场有效性
弱式有效
可实施性。 [参 考 文 献]
[1]陈灯塔,洪永森.中 国 股 市 是 弱 式 有 效 的 吗 —基 于 一 种
同理可以证明半强式有效市场 强式有效市场
新方法的实证研究[J].经济学(季刊),2003(3)
性质二: 定义在(Ω,I,P)以及滤基(In)n 上的市场 M 是有效的市
[2]张亦春,周颖刚。中国股市弱式有效吗[J].金融研究,2001 (3)
1965 年 Fama 在 总 结 前 人 研 究 的 基 础 上 , 在 The Theory Of Stock Market Price 中 定 义 了 有 效 市 场 的 价 格 行 为,Samuelson(1965)、Mandelbrot(1966)和 Roberts(1967)在不 同的领域完善了市场有效性理论, 并根据价格对信息的 反应程度,把有效市场分为:弱有效市场、半强式有效市 场和强式有效市场。 Fama(1970)最终完成了有效市场的完 整框架,正式形成了有效市场理论,认为有效市场的核心 是能够及时、准确的对市场信息做出反应的市场,信息是 有效市场的核心。
第 2012 年第 11 期 ( 总第 409 期)
[文章 编 号] 1009- 6043( 2012)11- 0030- 02
商业经济 SHANGYE JINGJI
鞅、鞅差和市场有效性
No.11,2012 Total No.409
刘辉
( 上海理工大学 管理学院 , 上海 200093)
[摘 要] 市场有效性理论是现代经济学和金融学的基础定理之一,主流的资本市场理论均以其为基础。 通过探
随着分析技术的发展, 随机分析技术被广泛应用于 价格行为研究和金融指标分析, 但这些研究却发现价格 Pt 的对数增量 Xt=lnPt-lnPt-1 似乎是独立的(满足特定的假 设的条件下),Cowles(1933)以及随后的 Working(1934)等均 得出了类似结论 。 随后,Kendall 发现金融市场价 格 波动 具 有 完 全 随 机 性 ,无 周 期 、无 趋 向 行(即 Sn=S0Exp(∑Xt), 其中 Xt=lnPt-lnPt-1,Xt 独立同分 布), 并在 The Analys is Of Economic Time-Serial 中描述了市场价格行为的形态及其 随机过程特征。 在其基础上,学者不断完善分析的方法并 构 造 随 机 过 程 模 型 来 描 述 价 格 行 为 (Robert,Osborne 和 Samuelson 等)。 这 一 系 列 研 究初 步 构 建 了 有效 市 场 理 论 (Efficient Capital Market Theory)的雏形。
优越,以回归的名义
优越,以回归的名义
虚怀
【期刊名称】《科学与财富》
【年(卷),期】2007(000)012
【摘要】11月5日,沪市6,000点的高度在“中国石油”的面前显得空旷寂静,在我的印象中,除了六年前“虹桥机场债券”上市遭遇尴尬之外,上海证交所内千余次上市仪式无一例外地大获成功。
当“中国石油”带着“亚洲最赚钱公司”的荣耀回归之际,任何悬念都是多余的。
【总页数】1页(P120)
【作者】虚怀
【作者单位】无
【正文语种】中文
【中图分类】F426.22
【相关文献】
1.人民币名义有效汇率对货币替代的影响——基于门限回归模型的研究 [J], 贺晓波;郝颖
2.非配对设计多值名义资料一水平多重Logistic回归分析 [J], 巩晓文; 李长平; 胡良平
3.复杂抽样调查设计多值名义资料一水平多重Logistic回归分析 [J], 刘媛媛; 李
长平; 胡良平
4.非配对设计多值名义资料多水平多重Logistic回归模型 [J], 李长平; 张甜甜; 宋
德胜; 胡良平
5.论债权执行中对次债务人执行名义正当性的回归 [J], 姜龙
因版权原因,仅展示原文概要,查看原文内容请购买。
鞅在期权定价中的应用
The Annals of Applied Probability1999,Vol.9,No.2,504–528PRICING CONTINGENT CLAIMS ON STOCKSDRIVEN BY L´EVY PROCESSES1By Terence ChanHeriot-Watt UniversityWe consider the problem of pricing contingent claims on a stock whose price process is modelled by a geometric L´e vy process,in exact analogy withthe ubiquitous geometric Brownian motion model.Because the noise pro-cess has jumps of random sizes,such a market is incomplete and there isnot a unique equivalent martingale measure.We study several approachesto pricing options which all make use of an equivalent martingale measurethat is in different respects“closest”to the underlying canonical measure,the main ones being the F¨o llmer–Schweizer minimal measure and the mar-tingale measure which has minimum relative entropy with respect to thecanonical measure.It is shown that the minimum relative entropy measureis that constructed via the Esscher transform,while the F¨o llmer–Schweizermeasure corresponds to another natural analogue of the classical Black–Scholes measure.1.Introduction.We consider the problem of pricing contingent claims on a stock whose price at time t,S t,is modelled by a geometric L´e vy processdS t=σt S t−dY t+b t S t−dtwhere Y is a general L´e vy process(satisfying some additional conditions)and not merely a Brownian motion.The classical option pricing theory of Black and Scholes relies on the fact that the payoff of every contingent claim can be duplicated by a portfolio consisting of investments in the underlying stock and in a bond paying a riskless rate of interest;in other words,the risk of buying or writing an option can be completely hedged against.In such complete mar-kets,there is a unique measure which is equivalent to the canonical measure (the“real world”measure)and which makes the discounted price process a martingale.The unique fair price of a contingent claim is then the expectation under this martingale measure of the discounted payoff at maturity,which is essentially the content of the famous Black–Scholes formula.For the stock prices described above,there are many equivalent measures under which the discounted price process is a martingale,in contrast to the geometric Brownian model.In other words,such a market is incomplete—that is,contingent claims cannot in general be hedged by a suitable portfolio. Because there does not exist a unique equivalent martingale measure,it is not possible simply to use the martingale measure to price a contingent claim in the manner just described.Instead,additional criteria must be used to select Received April1997;revised November1997.1Supported in part by the Carnegie Trust for the Universities of Scotland.AMS1991subject classifications.Primary90A09,60G35;secondary60J30,60J75.Key words and phrases.Option pricing,incomplete market,equivalent martingale measures.504OPTION PRICING WITH L´EVY PROCESSES505an appropriate martingale measure from among the uncountably many such measures with which to price a contingent claim.Many different approaches to this problem have been proposed in recent years but there is as yet no definitive way of pricing contingent claims in incomplete markets which is preferable to the other possible methods in all situations.Moreover,compared to the large body of work devoted tofinding new approaches to option pricing in incomplete markets,relatively little seems to have been done to compare and to investigate the relationship between the various approaches.Part of the aim of this paper is to go a little way toward redressing the balance.For our particular model,we shall concentrate on various approaches to pricing options which are all based on the idea of using an equivalent martingale measure that is in different respects“closest”to the underlying canonical measure,the main ones being the F¨o llmer–Schweizer minimal measure and the martingale measure which has minimum relative entropy with respect to the canonical measure.2.Description of the model.Before describing the model,wefirst re-view some preliminary results concerning L´e vy processes.For a more detailed treatment,the reader is referred to Protter(1990),Jacod and Shiryaev(1987) and Liptser and Shiryayev(1989).A L´e vy process Y t is simply a process with stationary and independent increments:in other words,Y s+t−Y s is independent of Y u u≤s and has the same distribution as Y t−Y0.All L´e vy processes are semimartingales and throughout this paper we adopt the convention that all L´e vy processes are right continuous with left limits(cadlag).Since Y has stationary independent increments,its characteristic function must take the formE exp −iθY t =exp −tψ θfor some functionψ,called the L´e vy exponent of Y.The L´e vy–Khintchine formula says that2 1 ψ θ =c22θ2+iαθ+ x <1 1−e−iθx−iθx ν dx + x ≥1 1−e−iθx ν dxforα,c∈R and for someσ-finite measureνon R\ 0 satisfying2 2 min 1 x2 ν dx <∞The measureνis called the L´e vy measure of Y.The L´e vy–Khintchine formula(2.1)is intimately connected to the structure of the process Y itself,in particular to the L´e vy decomposition of Y,which we describe below.From the L´e vy–Khintchine formula we can deduce that Y must be a linear combination of a Brownian motion and a quadratic pure jump process X which is independent of the Brownian motion.[A process is506T.CHANsaid to be quadratic pure jump if the continuous part of its quadratic variation X c≡0,in which case its quadratic variation becomes simplyX t= 0<s≤t X s 2where X s=X s−X s−is the jump size at time s.]It will be convenient to explicitly separate out the Brownian component from the quadratic pure jump component X and we therefore write2 3 Y t=cB t+X twhere B is a standard Brownian motion on R and X is quadratic pure jump. We now proceed to describe the L´e vy decomposition of X[the full L´e vy de-composition of Y is then obtained by combining this with(2.3)].Let Q dt dx be a Poisson measure on R+×R\ 0 with expectation(or intensity)measure dt×ν whereνis the L´e vy measure introduced earlier and dt denotes Lebesgue measure.The measureν(or more precisely dt×ν)is also sometimes called the compensator of Q.The L´e vy decomposition of X says that2 4 X t= x <1 x Q 0 t dx −tν dx + x ≥1 x Q 0 t dx +t E X1− x ≥1 xν dx= x <1 x Q 0 t dx −tν dx + x ≥1 x Q 0 t dx +αtwhere we have putα=E X1− x ≥1 xν dxThe parameterαis called the drift of the L´e vy process X.For the purposes of our model,we require the process Y to satisfy certain additional conditions.The key assumption we require of Y is that2 5 E exp −hY1 <∞for all h∈ −h1 h2 ,where0<h1,h2≤∞.This implies that Y t hasfinite moments of all orders, and in particular,E X1 <∞.In terms of the L´e vy measureνof X we havex ≥1 e−hxν dx <∞(2.6a)x ≥1 xγe−hxν dx <∞∀γ>0(2.6b)x ≥1 xν dx <∞(2.6c)OPTION PRICING WITH L´EVY PROCESSES507 for all h∈ −h1 h2 .[Note that as(2.6a)holds for all h in an open interval, (2.6b)and(2.6c)follow from(2.6a).]With these assumptions in mind,(2.4)can be rewritten as2 7 X t= R x Q 0 t dx −tν dx +t E X1 =M t+atwhere M t= R x Q 0 t dx −tν dx is a martingale and a=E X1 .Ob-serve that(2.7)gives the Doob decomposition of X as the sum of a martingale and a previsible process offinite variation.Even though a is not the drift of X in the sense in which the term is usually understood(αis the drift in the technical sense),we shall see later that a plays the role of a drift contribution from the jump component of Y.We refer to a(or more correctly,the process t→at)as the previsible part of X.In addition,(2.5)implies that instead of the characteristic function,one could consider the Laplace transform of Y t instead.By a slight abuse of nota-tion,we also useψto denote the“L´e vy exponent”and write E exp −θY t = exp −tψ θ .Bearing in mind the simplified decomposition(2.7)for processes satisfying(2.5),the L´e vy–Khintchine formula(2.1)now becomes2 8 ψ θ =−c2θ22+aθ+ R 1−e−θx−θx ν dxA very similar analysis can be carried out for more general semimartingales with jumps and in particular for processes with independent but not neces-sarily stationary increments.Jacod and Shiryaev(1987)have a full treat-ment.A random measure Q dt dx is also associated with such a process, but it is not necessarily a Poisson measure.As in the case of L´e vy processes, the measure Q describes the mechanism by which jumps of the process oc-cur.The compensator of Q is the unique previsible measureν dt dx such that Q 0 t −ν 0 t is a martingale for any Borel set ⊂R\ 0 .If the process in question has independent increments,the measureνis neces-sarily deterministic,so Q is an inhomogeneous Poisson measure.[For L´e vy processes,the stationarity of increments implies thatν dt dx =dtν dx .] The compensator can also be characterized as the unique previsible measure such that2 9 E 0 t × H s x Q ds dx =E 0 t × H s x ν ds dxfor any Borel set and any previsible process H.We also have an analogue of the L´e vy–Khintchine formula:E exp −θX t =exp −ψX t θ where 2 10 ψX t θ =a tθ+ R 1−exp −θx −θx ν 0 t dxwhere a t=E X t is the previsible part of X.Together with the quadratic variation of the continuous part of X(which is zero if X is quadratic pure jump as in our case),the compensator measure and previsible part form the508T.CHANthree components of the characteristics of a semimartingale.The following result is also worth noting:for any measurable function f t x ,2 11 0<s≤t f s X s = t0 R f s x Q ds dxNext,we recall Itˆo’s formula for cadlag semimartingales.If X1 X2 X n are cadlag semimartingales and f a C2function,thenf X1t···X n t −f X10···X n0= t0f i X1s−···X n s− dX i s+12 t0f i j X1s−···X n s− d X i X j c s+ 0<s≤t f X1s···X n s −f X1s−···X n s− −f i X1s−···X n s− X i swhere X i X j c is the continuous part of the mutual variation of X i and X j, f i=∂f/∂x i,f i j=∂2f/∂x i∂x j and we have used index summation convention. This will often be abbreviated tod f X1t X2t···X n t=f i X1t−···X n t− dX i t+12f i j X1t−···X n t− d X i X j c t+f X1t···X n t −f X1t−···X n t− −f i X1t−···X n t− X i t Turning now to a description of the model,on a probability space t P ,let Y t=cB t+X t=cB t+M t+at be a L´e vy process of the form described earlier,satisfying the condition(2.5).We assume that thefiltration t is the minimal one generated by Y.The stock price S t is the solution of the stochastic differential equation2 12 dS t=σt S t−dY t+b t S t−dt=σt S t− c dB t+dM t + aσt+b t S t−dtwhere the coefficientsσt and b t are deterministic continuous functions.Equa-tion(2.12)has an explicit solution[see Protter(1991)]given by2 13 S t=S0exp t0σs dY s+ t0 b s−c2σ2s2 ds× 0<s≤t 1+σs Y s exp −σs Y s=S0exp t0cσs dB s+ t0σs dM s+ t0 aσs+b s−c2σ2s2 ds × 0<s≤t 1+σs M s exp −σs M sFrom this we see thatσ S u u≤t = t and so a contingent claim T expiring at time T may be regarded as a nonnegative T-measurable random variable.OPTION PRICING WITH L´EVY PROCESSES509 The Doob decomposition of Y suggests that b t+aσt rather than b t should be regarded as the drift in(2.12).Although in practice,a and b cannot be estimated separately and consequently there is no need to add a drift to X separately from b in(2.12),we have chosen to consider the parameters a and b separately for convenience,because the value of a is often implicit in the specification of a particular process as X and so cannot be chosen indepen-dently(e.g.,if we specify that X be a Poisson process of rateλ,this forces a=λ).In order to ensure that S t≥0for all t almost surely,we needσt M t≥−1 for all t.This in turn implies that the jumps of X must be bounded on at least one side,that is,either bounded from below or bounded from above. Suppose that X t= M t∈ −c1 c2 which is equivalent to saying that the L´e vy measureνis supported on −c1 c2 where c1,c2≥0and one(but not both)of c1,c2may be infinite.This implies that at least one of h1,h2in(2.5) must be infinite.In order to ensure that S t≥0we need2 14 −1c2≤σt≤1c1for all t.As far as the Brownian component of Y is concerned,the sign of the volatilityσis inconsequential,but if one were to keep to the usual convention thatσ>0, then(2.14)shows that the jumps of X should be bounded from below(i.e., c1<∞).The conditions(2.5)and(2.14)will of course rule out any processes with“fat-tailed”distributions such as stable processes.However,the allowable L´e vy processes here include all the processes considered in Gerber and Shiu (1994):for example the gamma,the inverse Gaussian,the Poisson and the difference of two independent Poisson processes.The riskless rate of interest is given by a deterministic continuous function r t and the value P t of a bond or bank account paying this rate of interest evolves according to the ODE˙P t=r t P tAs withσand b,we could also allow r to be adapted to t ,although this is a less useful generalization in practice.For notational convenience,we denote byˆS t the discounted stock price defined by2 15 ˆS t=exp − t0r s ds S tIt will be seen in the next section that,in this model,there are many mea-sures,equivalent to the underlying canonical measure P,which makesˆS t a martingale.We conclude this section by briefly mentioning some other similar models which have been considered by various authors.Bardhan and Chao(1993)con-sidered a similar model where the noise consists of several Brownian motions and several point processes whose jumps are all of size1but whose intensities510T.CHANmay not be time-homogeneous and may be random.However,the contingent claims they considered are on more than one stock,where the number of stocks exactly equals the total number of noise terms(Brownian motions and point processes).This,together with the fact that the jump sizes arefixed,ensure that their model is complete.Aase(1988)is essentially an attempt at a more general model than that of Bardhan and Chao,where the point process may have random jump sizes but still afinite number of jumps in anyfinite time interval.Unfortunately,Aase(1988)claims that the model is also complete even though there are more than one equivalent martingale measure;this is false because it contradicts a well-known theorem of Harrison and Pliska (1981,1983)to the effect that completeness of the market is equivalent to uniqueness of the equivalent martingale measure.Indeed,Aase(1988)claims that every martingale can be represented as an integral with respect toˆS t,in the form2 16 t0θs dˆS swhereθt is a previsible process.(The existence of such a representation is equivalent to completeness.)This is false,as the martingale representation theorem[see,e.g.,Jacod and Shiryaev(1987)]for the jump processes consid-ered in Aase(1988)(which includes certain classes of L´e vy processes)says that every martingale has the representationt0H s x ˜Q ds dx −˜ν ds dxwhere˜Q ds dx is a random jump measure whose compensator is˜ν—analogous,respectively to the Poisson and L´e vy measures associated with a L´e vy process—and where H s x is a previsible Borel function(see the next section for a precise definition).We shall see in the next section that, under any equivalent martingale measure,the jump part ofˆS t has the representationt0γs d˜M s= t0 Rγs x ˜Q ds dx −˜ν ds dxHence,in order that the representation(2.16)holds,we need H s x =θsγs x, which of course is not true in general.Finally,Gerber and Shiu(1994)con-sider the case where the stock price is modelled by a process of the form exp σY t+bt ,whereσand b are constants and Y is a L´e vy process satisfying (2.5).This has many similarities with our present model and both are obvious generalizations of the geometric Brownian model.The program carried out in the next section can be equally well carried out for the Gerber–Shiu model, often with only fairly minor modifications.Each model has its own advantages and disadvantages.The main advantage of the Gerber–Shiu model is that the jumps of X can be of any size and do not have to be bounded from one side. The present model based on(2.12)describes the price dynamics in a mannerOPTION PRICING WITH L´EVY PROCESSES511 which is intuitively more natural and is also more appealing in other mathe-matical respects.This is because the starting point of the classical geometric Brownian model is(2.12);that the price S t also has the form exp σ Y t+b t isa direct consequence of the stochastic calculus involved,in particular,Itˆo’s for-mula.For discontinuous L´e vy processes,Itˆo’s formula is rather different and so a model which takes as its starting point a differential equation like(2.12) and then takes account of the differences in the underlying stochastic calculus in the subsequent computations is more likely to lead to simpler calculations and more attractive results.This point is illustrated in Section3.3in relation to the Esscher transform and minimum relative entropy measure.Gerber and Shiu(1994)deal only with pricing contingent claims by Esscher transforms, without explaining why the Esscher transform is a particularly appropriate martingale measure to use.[However,in their response to the discussions that follow their paper,they give a justification of the Esscher transform in terms of utility;see page175of Gerber and Shiu(1994).]We shall show that it is the martingale measure which has minimum relative entropy with respect to the canonical measure.3.Equivalent martingale measures and pricing formulas.We be-gin by characterizing all equivalent martingale measures Q under which the discounted price processˆS defined at(2.15)is a t -martingale.To this end, wefirst need to characterize all the measures which are absolutely continuous with respect to P.We continue to use the notation established in the previous section.In particular,Y t=cB t+X t is a L´e vy process satisfying(2.5)and X t is a quadratic pure jump L´e vy process with L´e vy measureνsupported on a subset of −c1 c2 ,where at least one of c1,c2isfinite.The Doob–Meyer decompo-sition of X is given by X t=M t+at,where M is a quadratic pure jump martingale with M0=0and a=E X1 .If Q dt dx is the Poisson measure associated with X,let M dt dx =Q dt dx −dtν dx denote the compen-sated measure.Thus,for example,the martingale part of X can be written as M t= t0 R x M ds dx .Further,expectations under the canonical measure P will be denoted by E · while expectations with respect to any other measure Q will be denoted by Q · .Let denote the previsibleσ-algebra on ×R+associated with thefiltra-tion t and let˜ = × ,where is the Borelσ-algebra on R.A function H ω t x which is˜ -measurable will be called Borel previsible.Thus,sup-pressing the explicit dependence onω,a Borel previsible function or process H t x is one such that the process t→H t x is previsible forfixed x and the function x→H t x is Borel-measurable forfixed t.Lemma3.1.Let G t and H t x be previsible and Borel previsible processes respectively.Suppose thatE t0G2s ds <∞512T.CHANand H≥0,H t 0 =1for all t≥0.Let h t x be another Borel previsible process such that3 1 R H t x −1−h t x ν dx <∞Define a process Z t by3 2 Z t=exp t0G s dB s−12 t0G2s ds+ t0 R h s x M ds dx− 0 t ×R H s x −1−h s x ν dx ds × 0<s≤t H s X s exp −h s X sThen Z is a nonnegative local martingale with Z0=1and Z is positive if and only if H>0.Remark.The process h referred to in Lemma3.1is,of course,not unique. However,given H,it is essentially unique in the following sense:suppose that h t x and f t x are two Borel previsible processes such that(3.1)holds;then because R f t x −h t x ν dx <∞,it is an easy exercise to check that the process Z is unchanged if h is replaced by f in(3.2):simply write f= h+ f−h .[However,note that it is crucial that R f t x −h t x ν dx <∞: the terms involving h in(3.2)do not cancel precisely because R h t x ν dx may diverge.]Thus,once H isfixed,Z does not depend on the choice of the process h satisfying(3.1).Of course,the easiest and most obvious choice of h is h≡H−1 However,in the present context,particularly in connection with the Esscher transform discussed below,it is useful to allow more general choices of h.In the case where x→H t x is twice-differentiable,the natural choice of h t x ish t x =x ∂H∂x t 0 =h t x say,for then H t x ∼1+h t x+O x2 as x→0and because of(2.6c)we simply have to choose H so thatx ≥1H t x ν dx <∞We shall henceforth assume that h t x =h t x is related to H t x in this way.Proof of Lemma3.1.It is clear that Z is nonnegative(resp.,positive)if and only if H≥0(resp.,H>0).That Z is a local martingale is a simpleOPTION PRICING WITH L´EVY PROCESSES513consequence of Itˆo’s formula;indeed,noting that Z t−Z t−=Z t− H t X t −1 ,Itˆo’s formula givesZ t=1+ t0G s Z s−dB s+ t0 R h s x Z s−M ds dx− t0 R Z s− H s x −1−h s x ν dx ds+ 0<s≤t Z s− H t X t −1−h s X s=1+ t0G s Z s−dB s+ t0 R h s x Z s−M ds dx+ t0 R Z s− H s x −1−h s x M ds dx=1+ t0G s Z s−dB s+ t0 R Z s− H s x −1 M ds dxThis last expression is a local martingale.2The processes G,H and h can be chosen so that E Z t =1for all t,in which case Z is a martingale.The next result is essentially a summary of Theorems3.24and5.19in Chapter III of Jacod and Shiryaev(1987)as they apply to the present setting.Theorem3.2.Let˜P be a measure which is absolutely continuous with re-spect to P on T.Thend˜Pd P T=Z Twhere Z is as in Lemma3.1,for some G,H and h for which E Z T =1. Moreover,under˜P,the process3 3 ˜B t=B t− t0G s dsis a Brownian motion and the process X is a quadratic pure jump process with compensator measure given by˜ν dt dx =dt˜νt dx ,where3 4 ˜νt dx =H t x ν dxand previsible part given by3 5 ˜a t=˜P X t =at+ t0 R x H s x −1 ν dx dsRemark.Jacod and Shiryaev(1987)treat only the case that h≡H−1 for the process Z in Lemma3.1.Also,in their treatment of characteristics of general semimartingales,Jacod and Shiryaev(1987)introduce truncation functions,and the corresponding results in Theorem3.24of that book depend514T.CHANin part on the choice of truncation function.In the present situation,assump-tion(2.6c)renders the introduction of truncation functions unnecessary.Turning now to the problem of pricing a contingent claim T,we wish to find an equivalent measure Q under which the discounted price processˆS t as defined in(2.15)is a martingale;the price of T is then Q exp − T0r s ds T . By Theorem3.2,under Q,X has Doob–Meyer decomposition3 6 X t=˜M t+at+ t0 R x H s x −1 ν dx dswhere˜M is a Q-martingale.In fact,˜M t=M t− t0 R x H s x −1 ν dx dswhere M is the P-martingale in the Doob–Meyer decomposition of X under P. Note that ˜M t= M t.Therefore,writing the discounted share priceˆS t in terms of the Q-martingale˜M and Q-Brownian motion˜B,we haveˆS t=S0exp t0cσs dB s+ t0σs dM s+ t0 aσs+b s−r s−c2σ2s2 ds × 0<s≤t 1+σs M s exp −σs M s=S0exp t0cσs d˜B s+ t0σs d˜M s+ t0 aσs+cσs G s+b s−r s−c2σ2s2 ds+ t0σs R x H s x −1 ν dx ds × 0<s≤t 1+σs ˜M s e−σs ˜M sSinceexp t0cσs d˜B s+ t0σs d˜M s− t0c2σ2s2ds 0<s≤t 1+σs ˜M s exp −σs ˜M sis a Q-martingale,a necessary and sufficient condition forˆS to be a martingale under Q is the existence of G and H for which the process Z in Lemma3.1isa positive martingale and such that3 7 cσs G s+aσs+b s−r s+ Rσs x H s x −1 ν dx =0for all s,almost surely.Note that h does not appear in(3.7),which is another reflection of the fact that h is essentially unique,given H,in the sense of the remark following Lemma3.1.It will turn out that G and H are in fact deterministic functions in all the cases considered in the sequel;in this case, (2.5)ensures that Z in Lemma3.1is a positive martingale and the key con-dition for an equivalent martingale measure is then(3.7).Moreover,B andOPTION PRICING WITH L´EVY PROCESSES515 X are still independent and have independent increments under Q in this connection,note that˜νis a deterministic measure.Of course,(3.7)does not specify G and H,and hence the equivalent martin-gale measure Q,uniquely.Below,we examine various approaches to choosingG and H based on other criteria,additional to(3.7).3.1.The F¨o llmer–Schweizer minimal measure.Recall that when the noise Y in(2.12)is just a standard Brownian motion,the unique equivalent mar-tingale measure Q is obtained by3 8 d Q d P T=Z Twhere Z satisfiesdZ t=γt Z t dB tand the processγis chosen so as to makeˆS a martingale under Q.In the present setting,a natural analogue of this would be to use the martingale measure Q defined by(3.8),where the Radon–Nikodym derivative Z is now given bydZ t=γt Z t− c dB t+dM tor equivalently3 9 Z t=1+ t0γs Z s− c dB s+dM sIn other words,the Brownian motion in the classical Black–Scholes setting has been replaced by the martingale part of the noise process Y.We saw in the proof of Lemma3.1that,in general,Z t=1+ t0G s Z s−dB s+ t0 R Z s− H s x −1 M ds dx Comparing this last expression with(3.9),we see that we require3 10 H s x −1=c−1G s x=h s xso thatγs=c−1G s.[When c=0,this just boils down to G≡0 H s x −1=γs x.]To obtain a martingale measure,we now use the martingale condition (3.7)together with(3.10).Puttingv= R x2ν dxit is easily verified that the solution to(3.7)and(3.10)is3 11G s=c r s−b s−aσsσs c2+v H s x −1= r s−b s−aσsσs c2+vx516T.CHANIn(3.9),we therefore have3 12 γs=r s−b s−aσsσs c2+vFinally,we need some conditions to ensure that H s X s >0;otherwise, the measure we have obtained will not be a probability measure but only a signed measure.Since we are assuming throughout this paper that the jump size X∈ −c1 c2 ,we require the right-hand side of(3.11)of be greater than −1for all x∈ −c1 c2 ,which is equivalent to the condition that3 13 −1c2< r s−b s−aσsσs c2+v<1c1So far,we have done nothing more than show that one can obtain an equiv-alent martingale measure by drawing an obvious analogy with the classical Black–Scholes setting.It turns out,however,that the martingale measure given by(3.8),(3.9)and(3.12)is precisely the F¨o llmer–Schweizer minimal measure introduced in F¨o llmer and Schweizer(1991),which we shall proceed to show.The minimal measure is closely connected to a hedging portfolio,which minimizes the risk involved in trying to duplicate a contingent claim T(pro-vided such a portfolio exists).We briefly sketch the main ideas below,following closely the treatment in F¨o llmer and Schweizer(1991)but omitting some of the technical assumptions not essential to the exposition.We adopt the notational convention that for any quantity f t,the discounted quantity will be denoted byˆf t=exp − t0r s ds f t.The value V t of any hedg-ing portfolio can be written as V t=ξt S t+ηt exp t0r s ds and hence the discounted value isˆV t=ξtˆS t+ηtwhereξandηare,respectively,the number of units of stock and bond.Only strategies for which V T= T P-a.s.are admissible.Define the cumulative cost at time t byC t=ˆV t− t0ξs dˆS sand the remaining risk byE C T−C t 2 t(In complete markets,C t is constant and hence the risk is zero.)The idea is to look for strategies ξ η which minimizes the remaining risk in a local sense: the risk is minimal under all“infinitesimal perturbations”of the strategy at time t.This is equivalent to the following precise technical definition.Definition3.1.An admissible strategy ξ η is called optimal if the asso-ciated cost C is a square-integrable martingale orthogonal to the martingale part(in the Doob decomposition)ofˆS under P.。
风险中性定价下的权证定价模型
风险中性定价下的权证定价模型
贺强;王建军
【期刊名称】《西安邮电学院学报》
【年(卷),期】2006(011)002
【摘要】通过中性定价法,在考虑权证行权时对股价的不同影响,以及股利发放对股价的影响的基础上,推导出类似Black-Scholes模型的欧式股本权证定价模型.并给出了在实际运用中的举例.
【总页数】4页(P80-82,98)
【作者】贺强;王建军
【作者单位】西北大学,经济管理学院,陕西,西安,710127;西北大学,经济管理学院,陕西,西安,710127
【正文语种】中文
【中图分类】F830.91
【相关文献】
1.非风险中性定价意义下幂函数族期权定价模型 [J], 潘坚;郭豫芳
2.非风险中性定价下的指数期权定价模型 [J], 肖艳清
3.非风险中性定价意义下幂函数族期权定价模型 [J], 潘坚;郭豫芳;;
4.非风险中性定价意义下幂函数族期权定价模型 [J], 潘坚;郭豫芳
5.风险中性和损失规避下银行存货质押定价模型 [J], 张宇慧
因版权原因,仅展示原文概要,查看原文内容请购买。